Japanese cosmetics giant's profit surges by 28%
Kao Group, which just announced the closure of Sofina's Tmall and Douyin official flagship stores a few days ago, released its financial report for the third quarter of 2026 on November 5.
According to the financial report, Kao Group's revenue in the first three quarters of 2026 reached 1.3193 trillion yen (equivalent to about 55.411 billion RMB), a year-on-year increase of 7.1%; operating profit was 146.5 billion yen (equivalent to about 6.155 billion RMB), a year-on-year increase of 28.1%; net profit attributable to parent company owners was 105.1 billion yen (equivalent to about 4.436 billion RMB), a year-on-year increase of 24.0%.
Looking at the third quarter alone, Kao Group's revenue was 447.4 billion yen (equivalent to about 18.885 billion RMB), a year-on-year increase of 5.8%; operating profit was 50.7 billion yen (equivalent to about 2.140 billion RMB), a year-on-year increase of 12.1%; net profit attributable to parent company owners was 39.4 billion yen (equivalent to about 1.663 billion RMB), a year-on-year increase of 12.3%.
While the group's direct online sales channels of its brands are shrinking during the "Double 11" window period, the group's revenue and profit both achieved double growth. Behind this contradictory contrast, what is the actual recent situation of Kao Group?
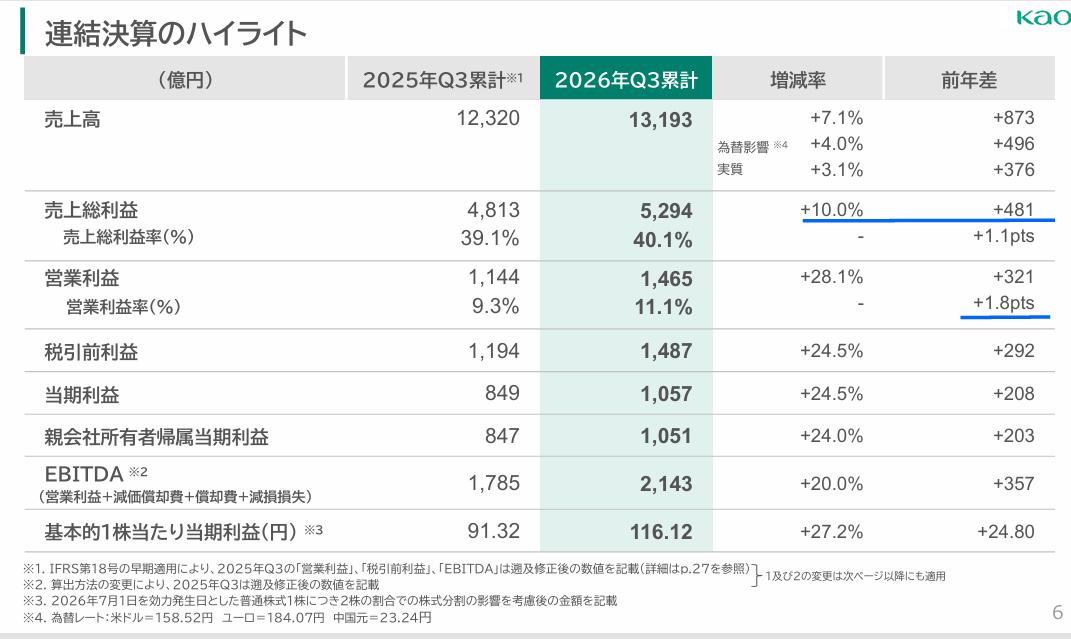
△ Source: Official financial report of Kao Group
Revenue and operating profit hit the highest level in nearly five years
When extending the timeline to the cumulative performance of the first three quarters in nearly five years, Kao Group's performance track is not a smooth upward line.
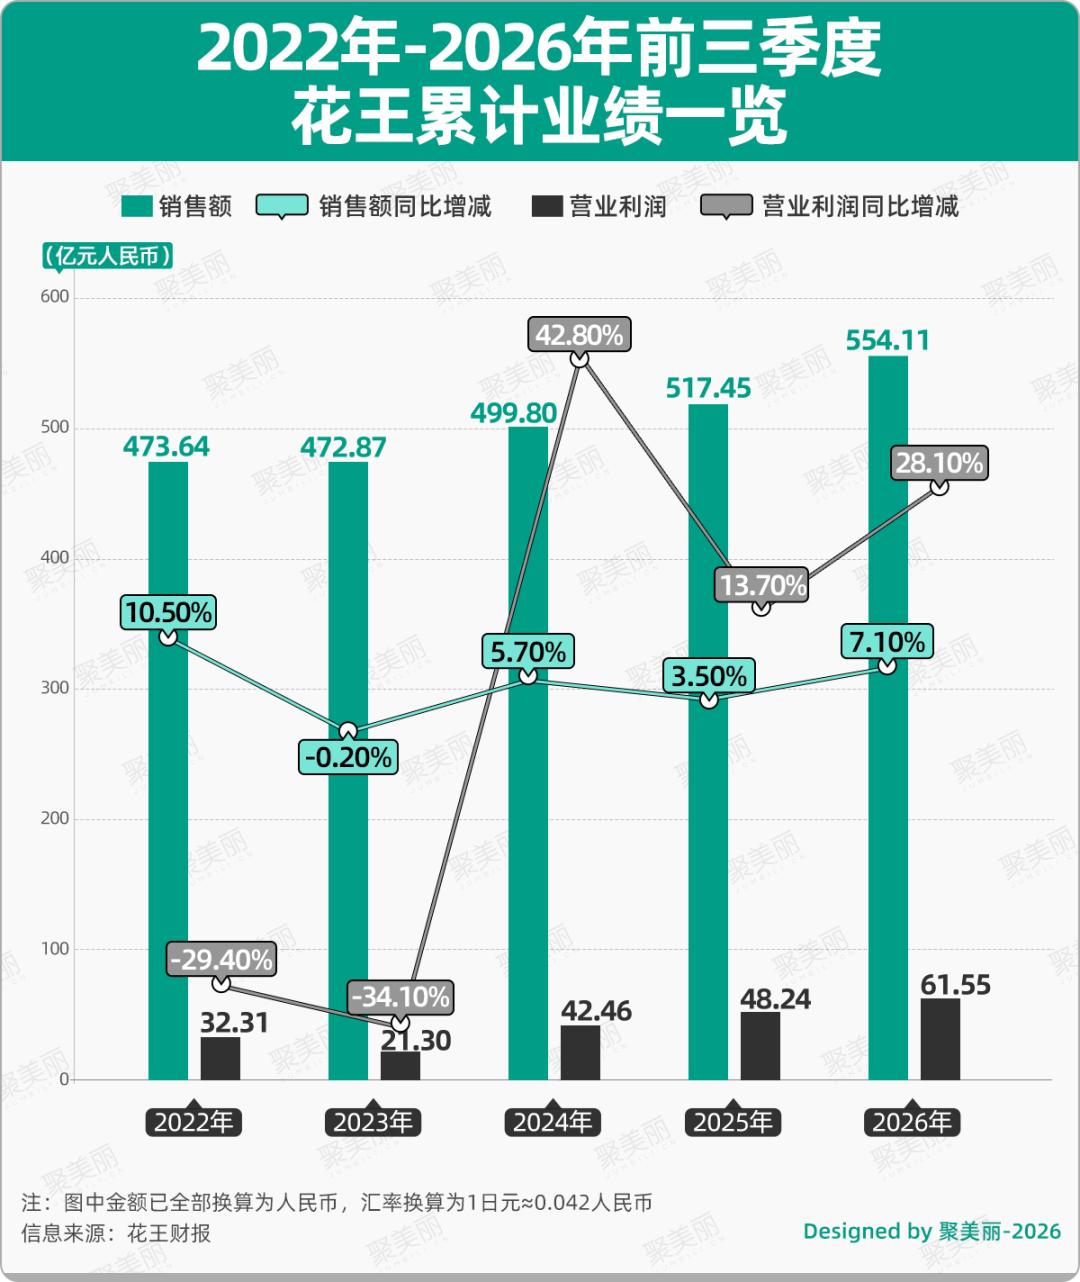
In the first three quarters of 2022, revenue was 1,127.71 billion yen (equivalent to about 47.364 billion RMB), up 10.5% year on year; operating profit was 76.917 billion yen (equivalent to about 3.231 billion RMB), down 29.4% year on year. Affected by raw material price fluctuations and exchange rate movements, the profit decline was nearly 30% compared with the same period of the previous year.
After that, revenue in the first three quarters of 2023 was basically flat at 1,125.883 billion yen (equivalent to about 47.287 billion RMB), down 0.2% year on year, and operating profit further dropped to 50.705 billion yen (equivalent to about 2.130 billion RMB), down 34.1% year on year.
A turning point emerged in 2024. From 2024 to 2026, the revenue of the first three quarters increased from 1,190.011 billion yen (equivalent to about 49.980 billion RMB) to 1.3193 trillion yen (equivalent to about 55.411 billion RMB), and the operating profit increased from 101.100 billion yen (equivalent to about 4.246 billion RMB) to 146.5 billion yen (equivalent to about 6.155 billion RMB). The double growth trend continued in 2025.
In the first three quarters of 2026, both revenue and operating profit hit a new high in nearly five years, and the operating profit margin rebounded from 6.8% in 2022 to 11.1%.
From the perspective of focused business segments, Kao Group has two major divisions: the Consumer Products Division and the Industrial Chemicals Division. Among them, the Consumer Products Division includes four business segments: Hygiene & Life Care, Health & Beauty Care, Life Care, and Cosmetics.
△ Source: Official financial report of Kao Group
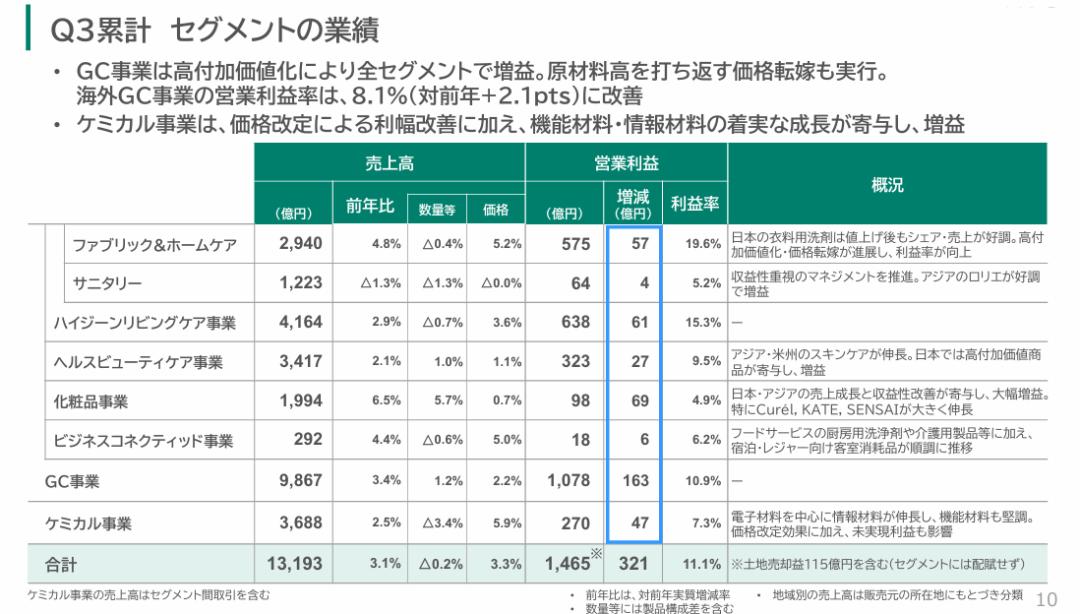
The Consumer Products Division remains the core business base. According to the financial report, the revenue of the Consumer Products Division reached 986.7 billion yen (equivalent to about 41.649 billion RMB) in the first three quarters of 2026, accounting for nearly 75% of the total revenue, while the Industrial Chemicals Division accounts for about 25%.
Among them, in the first three quarters of 2026, the Hygiene & Life Care segment recorded revenue of 416.4 billion yen (equivalent to about 17.576 billion RMB), up 4.6% year on year, with operating profit of 63.8 billion yen (equivalent to about 2.693 billion RMB), an increase of 6.1 billion yen (equivalent to about 257 million RMB); the Health & Beauty Care segment generated revenue of 341.7 billion yen (equivalent to about 14.423 billion RMB), up 6.2% year on year, with operating profit of 32.3 billion yen (equivalent to about 1.363 billion RMB), an increase of 2.7 billion yen (equivalent to about 114 million RMB).
The cosmetics segment posted the most remarkable growth rate. Its revenue in the first three quarters of 2026 reached 199.4 billion yen (equivalent to about 8.417 billion RMB), up 10.1% year on year; operating profit was 9.8 billion yen (equivalent to about 414 million RMB), an increase of 6.9 billion yen (equivalent to about 291 million RMB) year on year. The financial report attributes the growth of cosmetics sales to the strong driving force of domestic Japanese brands such as "Curél", "KATE" and "SOFINA BASIC+", the consolidation of the profit base in China, and the brand cultivation in Thailand.
However, it is worth noting that the operating profit margin of this segment is only about 4.9%, which is the lowest among the five segments, compared with 15.3% of the Hygiene & Life Care segment, 9.5% of the Health & Beauty Care segment, 7.3% of the Chemicals Business segment and 6.2% of the Business Interconnection segment.
Regional differentiation, Asia achieves double-digit growth
Returning from the overall performance and category performance to the regional layout, Kao Group's major markets show different performance trends.
In the first three quarters of 2026, Japan remains the largest market, with revenue of 730.8 billion yen (equivalent to about 30.847 billion RMB), up 5.1% year on year, with a real growth of 2.2%; Asia (excluding Japan) recorded revenue of 269.1 billion yen (equivalent to about 11.302 billion RMB), up 10.8% year on year, with a real growth of 2.2%; Americas generated revenue of 168.8 billion yen (equivalent to about 7.125 billion RMB), up 9.5% year on year, with a real growth of 0.6%; Europe posted revenue of 150.6 billion yen (equivalent to about 6.357 billion RMB), up 7.9% year on year, but with a real decline of 2.9%, making it the only market with negative real growth among the four major regions.
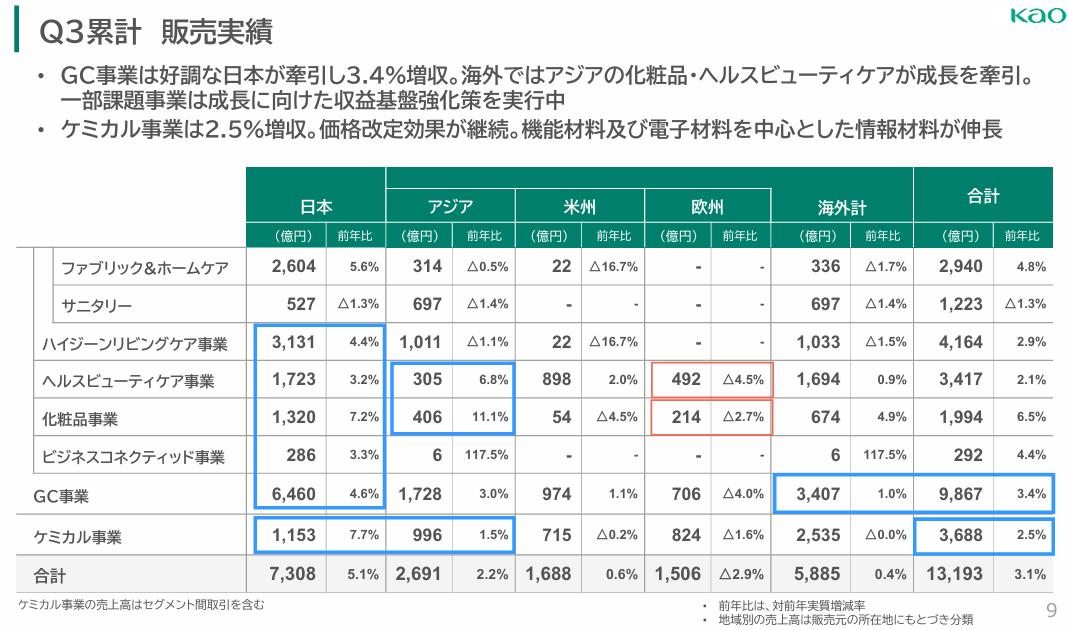
△ Source: Official financial report of Kao Group
Among them, the Asia region where the Chinese market is located occupies a slightly delicate position in this financial report.
On the one hand, this region is the fastest-growing region year on year; the financial report also mentions that sales in Asia are "significantly higher than the same period of the previous year", and the consolidation of China's profit base "has made progress".
On the other hand, it needs to be specially pointed out that the revenue of 269.1 billion yen (equivalent to about 11.302 billion RMB) and the growth rate of 10.8% in the first three quarters of 2026 are results under the new statistical caliber after restructuring, and the covered business scope has been expanded compared with before. If we extend the timeline, the sales in Asia under the old statistical caliber had recorded negative growth for three consecutive years from 2023 to 2025.
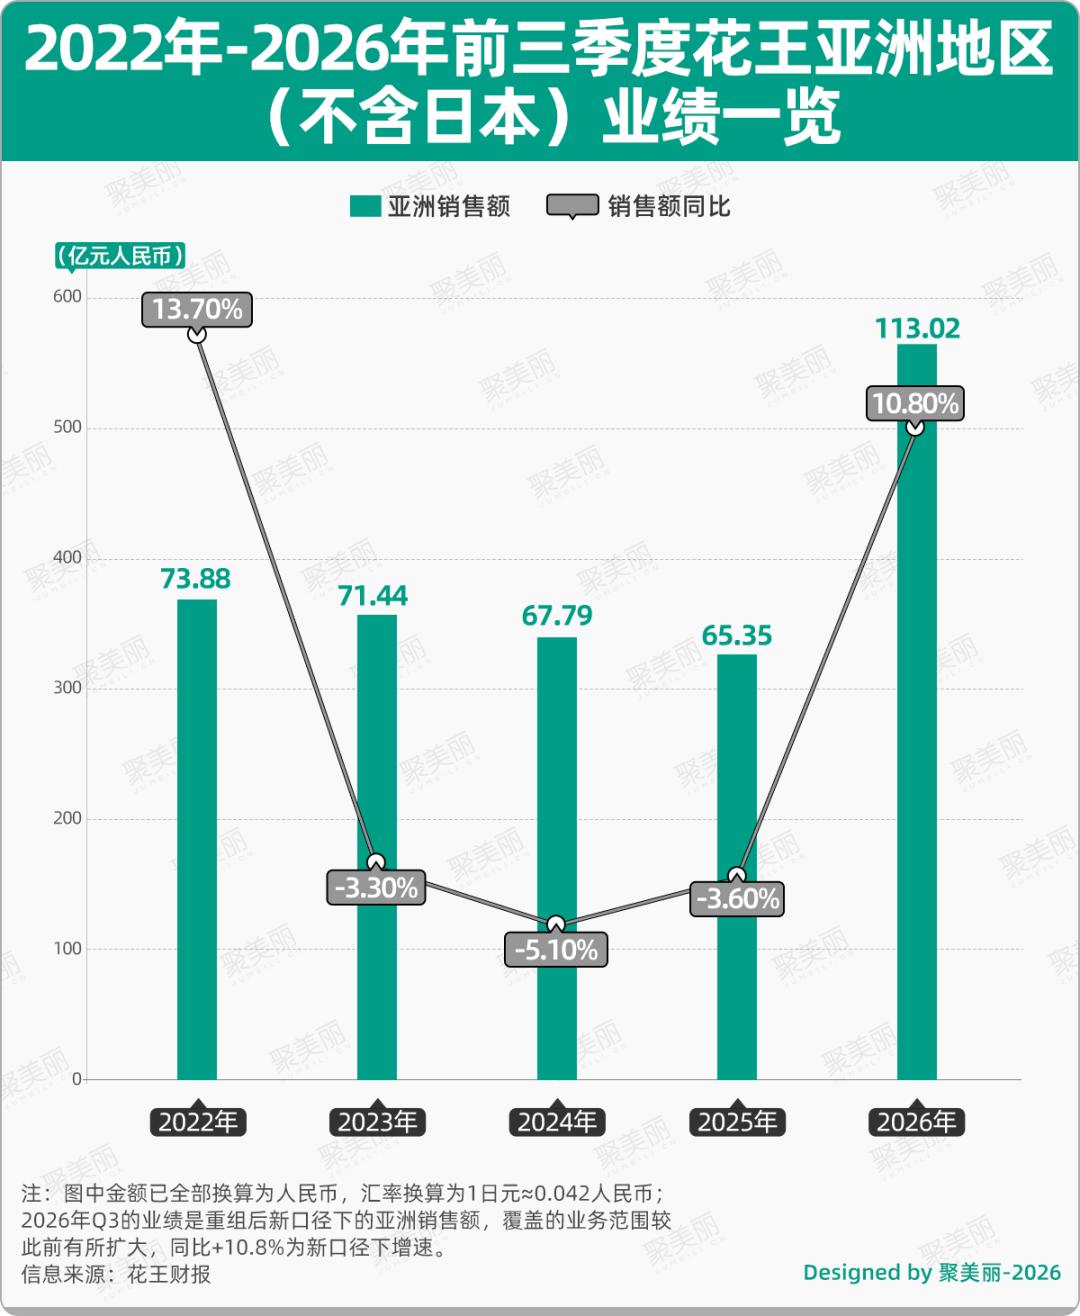
Combined with the switch of the new statistical caliber and the recent intensive measures in China, it can be found that Kao Group is continuously promoting the "consolidation of China's profit base" initiative in the Chinese market, and further focusing on "key brands and strategic fields"[1].
On the one hand, KATE closed its Tmall and Douyin official flagship stores in April 2026, and Sofina announced the official launch of the store closure process in November due to brand strategy upgrading and business layout adjustment, and officially stopped the sales of products in its flagship stores from December 1, 2026[2].
On the other hand, freeplus moved its global headquarters to Shanghai to promote full-link localization, and Curél is also expanding its product lines for Chinese consumers[3].
Turning back to Kao Group's financial report itself, the significant recovery of the profit statement in the first three quarters is one aspect, but Kao Group also admits that factors such as current tariff policies and rising raw material prices will still have an impact on it, which means that its upcoming challenges still exist.
Facing future challenges, Kao Group revealed in this financial report briefing that the future focus is not only to continue to improve profitability, but also to promote the growth of global sales, ensure the completion of the mid-term plan "K27", and lay a foundation for long-term development in the future.
Note: The exchange rate conversion in the article is calculated at 1 Japanese yen ≈ 0.042 RMB
Source:
[1] Page 6 of the main text of Kao Group's 2026 Q3 financial report;
[2] Kao Group's 2026 Q3 financial report, KATE's "Store Closure Notice", Kao's response to China Business Herald, Sofina's "Store Closure Notice";
[3] Kao Group China official website, "freeplus presses the acceleration button of localization and starts a new cycle of 'Chinese-style evolution'", Page 18 of the main text of Kao Group's 2026 Q3 financial report, 21st Century Business Herald.
This article is from the WeChat official account "Jumeili" (ID: jumeili-cn), written by Shui Jin, published with authorization from 36Kr.