New World Development continues to sell properties and land assets while replenishing its cash reserves.
On October 6, New World Development released its financial results for the 2026 fiscal year on the Hong Kong Stock Exchange.
The picture presented in this annual report is rather complex: both revenue and losses expanded, but recurring operating indicators improved significantly; core operating profit hit a new high in recent years, while the net debt ratio continued to rise.
The divergence between various data forms the core clue to understanding the current operating status of New World Development.
Performance Report
The composition of losses is worthy of disassembly first.
The annual report shows that non-cash impairment losses and net provisions related to the 11 SKIES project reached HKD 18.322 billion, which is an important part of the losses for the year. In addition, impairment losses recognized on properties held for development, under development and held for sale amounted to about HKD 7.979 billion, and changes in the fair value of investment properties also resulted in losses.
After the end of the financial year, the company reached a final agreement with the Airport Authority Hong Kong on September 30, 2026 to terminate the 11 SKIES agreement in advance. The market has shown a generally positive interpretation around this termination arrangement.
On October 2, UBS published a research report pointing out that the termination of the 11 SKIES contract is a positive news in the initial stage, and the contingent liability that the company originally promised to provide a minimum HKD 1.8 billion annual rent sharing guarantee to the Airport Authority from June 2027 to September 2066 will be exempted.
UBS also mentioned that the company's core profit for FY2026 was HKD 851 million, which was better than its original expectation. Large-scale impairments and provisions were fully recorded in the current profit and loss, resulting in an annual loss of HKD 26.818 billion. However, from the perspective of recurring indicators, the company's operating performance improved compared with the previous fiscal year.
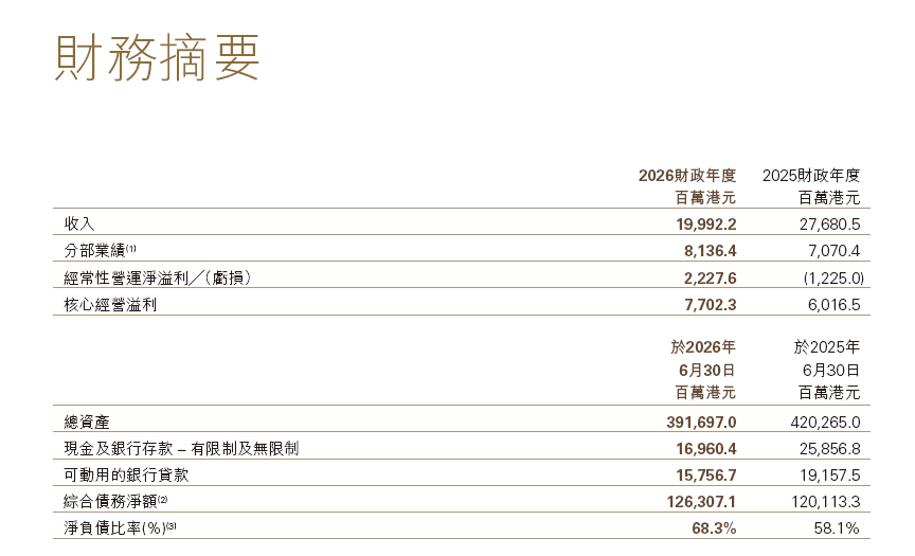
In FY2026, the company's recurring net operating profit turned from a loss of HKD 1.225 billion to a profit of HKD 2.228 billion; core operating profit increased from HKD 6.017 billion to HKD 7.702 billion. At the same time, the group continued to reduce costs: capital expenditure was HKD 11.8 billion, down 6% year on year, general administrative and other operating expenses were HKD 2.8 billion, down 19% year on year, and financial expenses decreased from HKD 5.421 billion to HKD 4.710 billion.
This part of the improvement is related to the Hong Kong property market and the sales performance of the company's own projects.
In this fiscal year, the performance of New World Development's property development segment was HKD 6.010 billion, up about 8% year on year. Among them, the performance of the Hong Kong property development segment rose from HKD 877 million in the previous fiscal year to HKD 3.828 billion; the performance of the mainland China property development segment was HKD 2.182 billion. The performance of the property investment segment reached HKD 3.475 billion, up about 7% year on year.
The sales performance of the Hong Kong market is relatively outstanding. From July 2025 to June 2026, the total value of residential property sale and purchase agreements in Hong Kong increased by about 49% year on year to HKD 657 billion, the number of residential property sale and purchase agreements increased by about 38% year on year to 74,695, and the private residential property price index rose by about 13% in the same period.
New World Development's sales mainly come from a number of residential projects. The Pavilia Farm III was relaunched for sale in April 2026, and recorded contracted sales of about HKD 5 billion as of June 30; after The Pavilia Farm III was launched in May, its contracted sales reached about HKD 2.7 billion as of June 30. By September 25, the cumulative contracted sales of The Pavilia Farm III was about HKD 5.9 billion, and that of The YOHO HILL was about HKD 2.8 billion; The YOHO Town and The Pavilia Forest recorded contracted sales of about HKD 7.3 billion and HKD 6.5 billion respectively during the review period.
The company also has a certain reserve of projects for future revenue recognition. As of June 30, 2026, New World Development's share of unrecorded contracted property sales in Hong Kong was about HKD 20.914 billion, which is expected to be recognized in FY2027 and FY2028; the relevant unrecorded contracted sales in mainland China was about RMB 3.4 billion.
Investment properties provide another part of relatively stable operating income. In FY2026, the company's property investment income in Hong Kong was HKD 3.424 billion, and its property investment income in mainland China was HKD 1.915 billion. Among them, the occupancy rate of K11 MUSEA reached 99% by the end of the period, and the shopping mall sales increased by about 23% year on year.
From these data, the improvement of operating profit in FY2026 mainly comes from the increased contribution of the Hong Kong property development business, the improved performance of the property investment business, and the reduction of costs and financing expenses.
However, the improvement of operating profit did not bring a synchronous reduction in net debt.
Source: Official Enterprise Release
As of June 30, 2026, New World Development's consolidated debt was HKD 143.268 billion, down about HKD 2.7 billion from HKD 145.970 billion in the previous fiscal year; however, cash and bank deposits decreased from HKD 25.857 billion to HKD 16.960 billion in the same period, so the consolidated net debt rose from HKD 120.113 billion to HKD 126.307 billion, and the net debt to equity ratio rose from 58.1% to 68.3%.
Cash flow data also shows this change.
In FY2026, net cash generated from operating activities of New World Development was HKD 477 million, compared with HKD 10.322 billion in the previous fiscal year; net cash generated from investing activities was HKD 3.550 billion, while financing activities recorded a cash outflow of HKD 10.425 billion. Cash and cash equivalents at the end of the period were HKD 12.735 billion.
The debt maturity structure also constitutes an issue that needs to be continuously addressed in the coming period. As of June 30, 2026, the company's bank borrowings, other borrowings, fixed-rate bonds and notes payable due within one year totaled HKD 23.237 billion, HKD 41.751 billion due in the second year, and HKD 41.601 billion due in the third year.
"Enhancing cash flow and reducing overall debt levels" is currently still listed as the top priority by New World Development. The CEO's report in the annual report proposed "seven measures to reduce debt", including accelerating property sales, asset disposal, unlocking the value of agricultural land, increasing rental returns, optimizing capital and operating expenditures, suspending dividend payments and deferring perpetual bond distributions, and adopting prudent financial management strategies.
Asset disposal has become one of the specific measures. In September, New World Development submitted a commercial real estate REIT registration and listing application to the China Securities Regulatory Commission and the Shanghai Stock Exchange, intending to use the Shanghai New World Tower as the underlying asset, with an expected offering size of about RMB 3.818 billion, and estimated net proceeds of about RMB 3.240 billion; in the same period, the company announced the disposal transaction of partial assets involving the Ningbo Tower and the Wangjiang New Town project in Hangzhou, with an amount of more than RMB 1.7 billion.
Land reserve has also been included in the asset value unlocking plan. As of June 30, 2026, the company held about 2.49 million square feet of attributable property development land reserve in Hong Kong; the attributable land area of agricultural land reserve in the New Territories was about 12.45 million square feet, of which about 10.3 million square feet is located in the Northern Metropolis. The company expects that the converted and planned-to-convert agricultural land reserves can provide about 10.6 million square feet of attributable floor area.
At the same time, New World Development still needs to arrange funds for ongoing operations. The independent auditor listed "going concern assessment" as a key audit matter in the report. The report shows that as of June 30, 2026, the company's total borrowings were HKD 148.587 billion, of which HKD 24.509 billion had to be repaid within the next 12 months; in the same period, it held cash and bank balances of HKD 16.960 billion, and had HKD 3.950 billion of undrawn term loan facilities. The board of directors finally concluded that it is appropriate to prepare the consolidated financial statements on a going concern basis.
This article is from the WeChat official account "Future Habitat", written by Zhang Guohao, authorized by 36Kr for release.