These 21 Chinese companies generated over 100 million yuan in IP derivative revenue in the first half of 2026.
On September 22, DreamIsland released its financial results for the previous quarter and the full fiscal year. By this calculation, its operating revenue in the first half of 2026 was about 292 million yuan. Among all IPs, WAKUKU, SIINONO, and ZIYULI generated revenues of 150 million yuan, 60.551 million yuan, and 27.137 million yuan respectively in the first half of the year.
As of June 2026, DreamIsland's IP matrix has expanded to 22, including 13 self-owned IPs and 9 exclusively licensed IPs. This quarter, it launched new IPs such as YONNNA, IMPOPO PIX, FLUFFY LILI, and Xiao Ao, covering diverse styles including cool-cute, adorable, and fashionable.
DreamIsland continues to promote product expansion and lifestyle integration of trendy play IPs. For example, SIINONO has launched a co-branded limited white peach flavored sparkling water with Genki Forest. In terms of the integration of culture, business, sports and tourism, DreamIsland designed the official mascot "Zhibao" WAKUKU for the World Humanoid Robot Games, and became the partner of the China Open for the second time. It jointly built the first IP immersive themed cruise park "Dream Hong Kong WAKUKU" (the maiden voyage is scheduled for October 1) with Chu Kong Shipping Enterprises in Hong Kong.
In terms of user reach, DreamIsland currently operates 7 directly-operated brand image stores in 4 core cities, 25 vending machine stores in 6 cities, and has also held pop-up stores at Shanghai PRISMA New Jia Center and Hangzhou Tower.
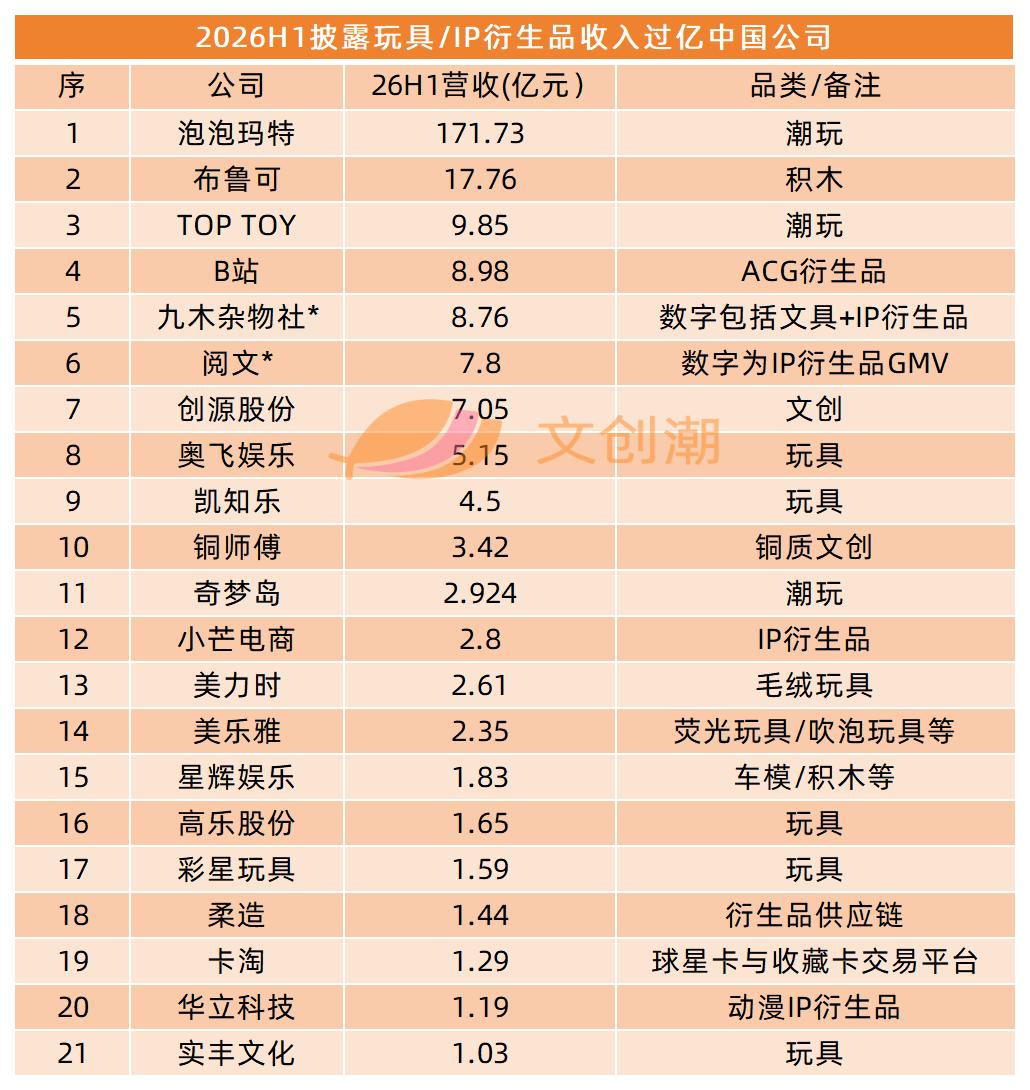
According to the statistics of the figures disclosed by various parties, Trendy Cultural Notes found that there are already 21 Chinese companies whose revenue from toys/trendy play/IP derivatives exceeded 100 million yuan in the first half of 2026. They are Pop Mart, Bloks, TOP TOY, Bilibili, M&G Stationery Jiumu Sundry Society, Yuewen, Chanyuan Co., Ltd., Alpha Group, Kidsland, Copper Master, DreamIsland, Xiaomang E-commerce, Mainland Toys, Meileya, Xinghui Entertainment, Goldlok Holdings, Playmates Toys, SoftCreate, KaTao, Wahlap Technology, and Shifeng Culture.
Among them, Pop Mart, Yuewen, Alpha Group, DreamIsland, Xiaomang, etc. focus on original IPs, while more companies are mainly engaged in manufacturing, production, sales and distribution.
We can see a rather "cruel" reality: the revenue of Pop Mart is twice the sum of the other 20 companies, and all 21 companies have their own difficulties to overcome — Pop Mart needs to respond to investors' expectations with increasingly impressive results, and the other 20 companies also need to find their own competitive barriers respectively.
For example, although TOP TOY achieved a revenue of 985 million yuan, a year-on-year increase of 32.7%, the expansion of stores and investment in IP development led to operating losses; the first financial report released by Copper Master after its listing also saw a sharp drop of 95.8% in net profit due to aggressive offline expansion; Kidsland, Goldlok Holdings and many other companies have explored many directions but still remain unprofitable.
At the same time, some manufacturers have achieved better profitability in their advantageous track. For example, Alpha Group's net profit in the first half of the year increased by 370.7% year-on-year, Bloks achieved double growth in revenue and net profit in the first half of the year, veteran toy OEM Mainland Toys, retail channel M&G Jiumu Sundry Society and other companies successfully turned losses into profits.
Pop Mart/TOP TOY: Growing Pains of China's Trendy Play Industry
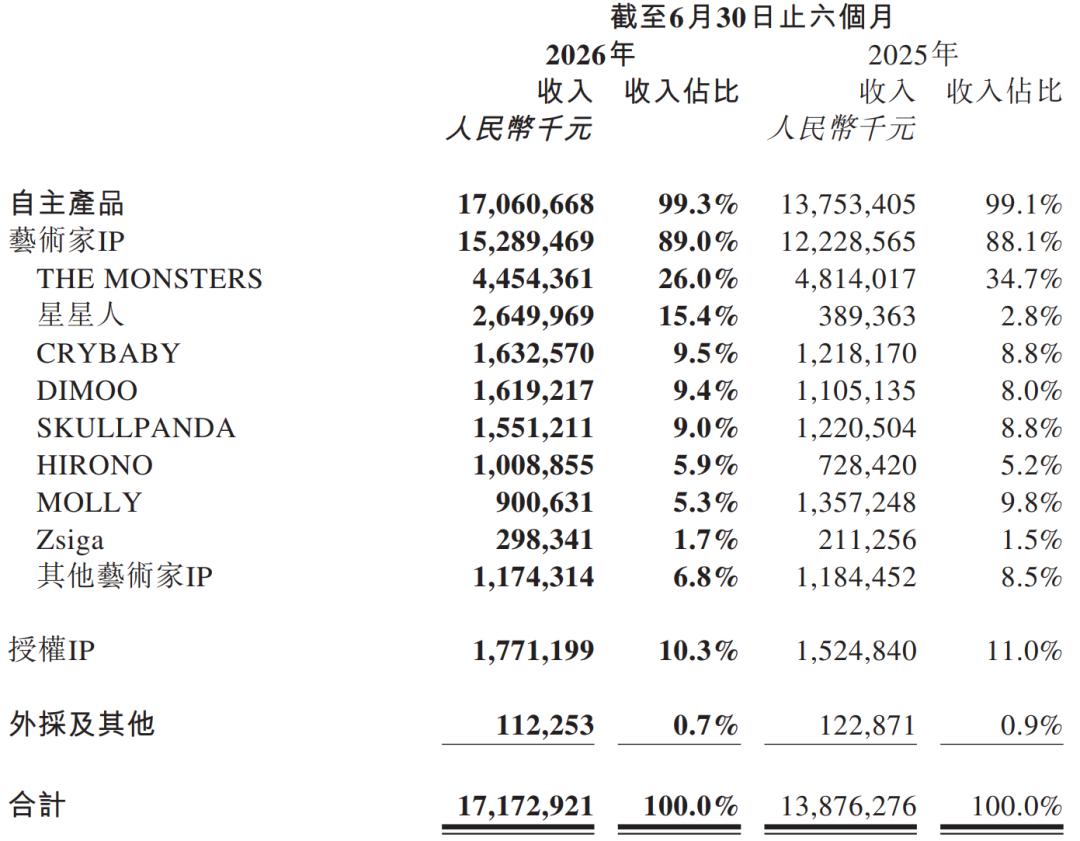
Pop Mart achieved a revenue of 17.173 billion RMB in the first half of the year, a year-on-year increase of 23.8%; the adjusted net profit was 5.156 billion yuan, a year-on-year increase of 9.5%, and the profit growth rate was significantly lower than the revenue growth rate.
The core reason is that the proportion of revenue from overseas high-gross-margin regions dropped from 36.3% to 29%, coupled with rising raw material costs, resulting in the overall gross margin falling by 0.6 percentage points to 69.7%. At the same time, sales and administrative expenses rose rigidly due to global store expansion (a net increase of 46 to 676 stores) and the growth of the number of employees (sales employees increased to 9734 people), rental and labor costs increased by 43.3% and 45.7% respectively, eroding the profit space.
As the absolute leader of the industry, Pop Mart's current volume is second only to Lego in the world, and it has multiple IPs with annual revenue of over 100 million yuan. Review: Top 20 Global Toys & IP Derivatives (2026 Half-Year Performance Version)
However, its performance failed to satisfy investors, and its market value fell from 400 billion to 200 billion in the past year.
The dilemma faced by Pop Mart is, to some extent, the growing pain of the entire Chinese trendy play industry: first, how to further improve the performance of character IPs like LABUBU after becoming a viral topic on social media; second, as a Chinese cultural and creative company, how to compete in the global market.
In the first half of the year, Pop Mart carried out a lot of marketing activities for THE MONSTERS (LABUBU). The top priority was the World Cup co-branding launched in April. Then LABUBU participated in the MV recording of the official World Cup song, and appeared at the opening ceremony and closing ceremony of the event successively.
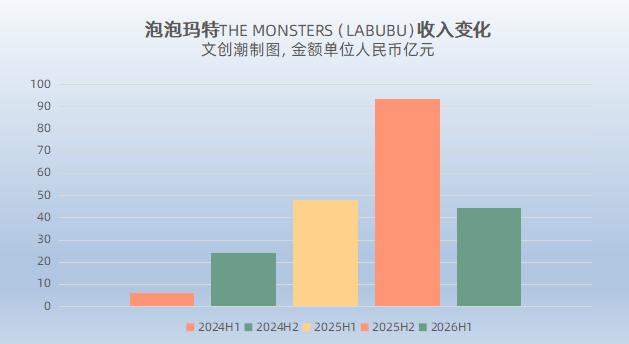
The return on these investments did not meet expectations. The IP's half-year revenue was 4.454 billion yuan, which is still Pop Mart's most profitable IP, but it dropped by 7.5% compared with the global boom last year; compared with the second half of last year, it fell by more than half.
Even, the sales of the co-branded product of SKULLPANDA and Hasbro's animation IP *My Little Pony* exceeded 600 million yuan, making it the best-selling product of Pop Mart in the first half of the year. Does this mean that even Pop Mart's trendy play IPs have to rely on the content of established giants such as Disney and Hasbro?
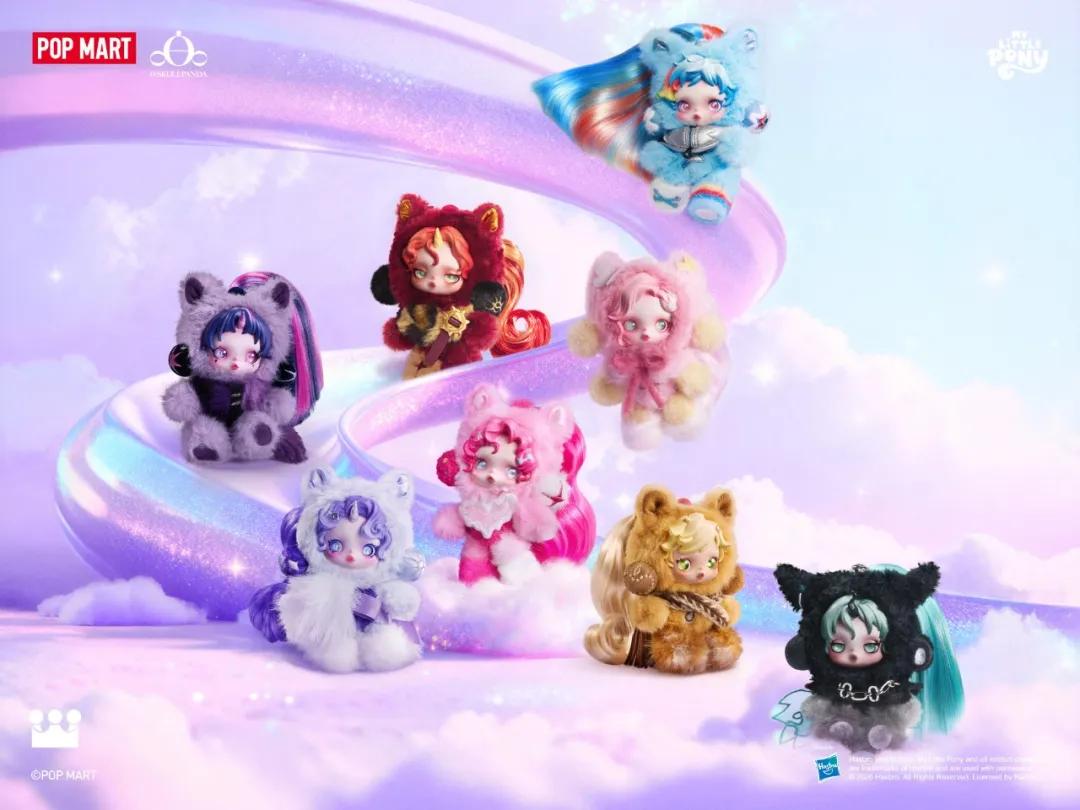
Co-branding of SKULLPANDA and *My Little Pony*
At the same time, Pop Mart's overseas expansion is also paying tuition. In the first half of the year, its overseas revenue fell by about 10.67% year-on-year, and the inventory turnover days surged from 123 days at the end of 2025 to 201 days at the end of June 2026. The turnover efficiency deteriorated significantly, mainly due to pre-stocking for overseas market expansion.
Among them, in the Americas market with the United States as the core, Pop Mart added 22 net new stores in the first half of the year (a 30% increase), but the overall revenue fell by 16.5%, which is in sharp contrast to the +17% growth of the overall North American market. The main reason is that the revenue of official channels was nearly halved year-on-year (down 44.6%), and other online channels dropped by 80%.
Even, exchange rate fluctuations led Pop Mart to record a foreign exchange loss of 720 million yuan in the first half of the year, while it recorded a foreign exchange gain of 120 million yuan in the same period last year, which had a great impact on profits.
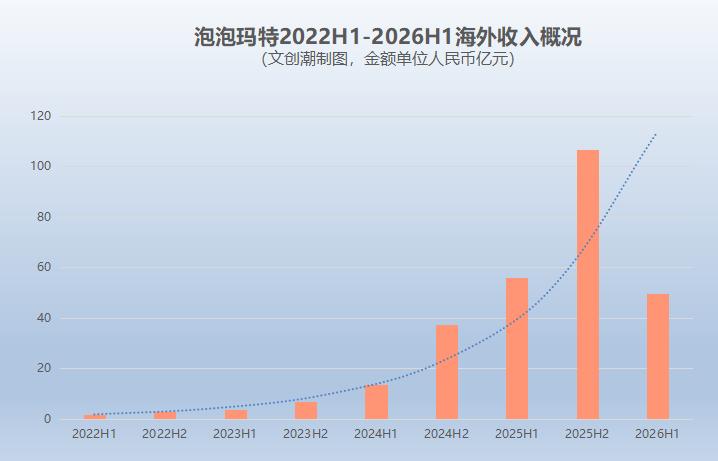
TOP TOY, whose core IPs are not original self-owned ones, is also facing growing troubles.
TOP TOY's main business model used to be attracting franchisees, which is quite effective in many consumer goods industries and has created many 10,000-store chain brands, but it cannot be well applied to the non-essential IP derivative field.
According to the financial report, TOP TOY's revenue from franchisee channels is somewhat "chicken ribs" — not worth the effort. After several years of development, TOP TOY chose to increase investment in self-owned IPs and self-operated channels. Review: Loss of hundreds of millions and global expansion, TOP TOY speeds up "learning" from Pop Mart | Trendy Cultural Express
The other side of expanding self-operation is to bear the costs by itself.
In 2025, TOP TOY's team labor costs, rental and logistics expenses surged. In the first half of 2026, its revenue increased but it recorded an operating loss of 72.34 million yuan (a profit of 51.03 million yuan in the same period last year). The main reasons are the increase in sales expenses brought by store expansion, investment in IP development, and non-cash losses from changes in the fair value of redemption liabilities generated by the issuance of preferred shares for strategic financing in 2025.
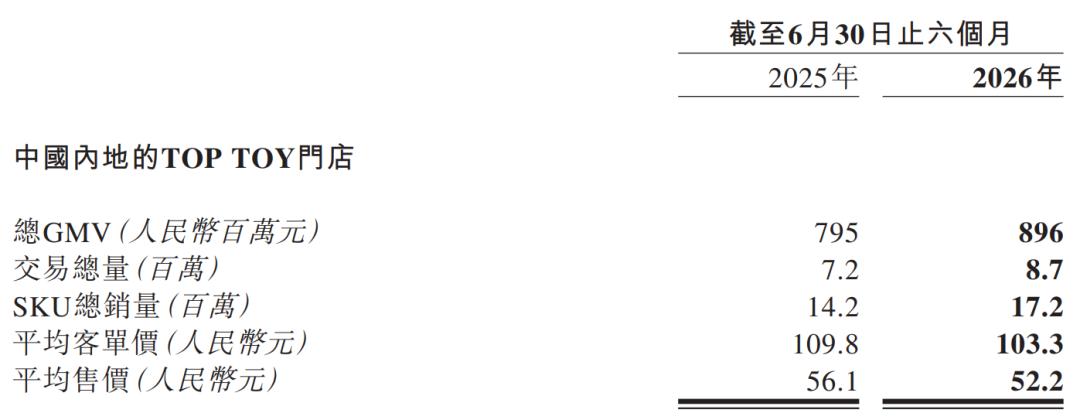
In the first half of 2026, TOP TOY achieved a total GMV of 1.332 billion yuan, of which stores in Chinese mainland contributed 896 million yuan, a year-on-year increase of about 12.6%. The total transaction volume and SKU sales increased simultaneously, but the average customer unit price and average selling price decreased slightly; overseas stores contributed 62 million yuan, online channels contributed 167 million yuan, and other channels contributed 207 million yuan.
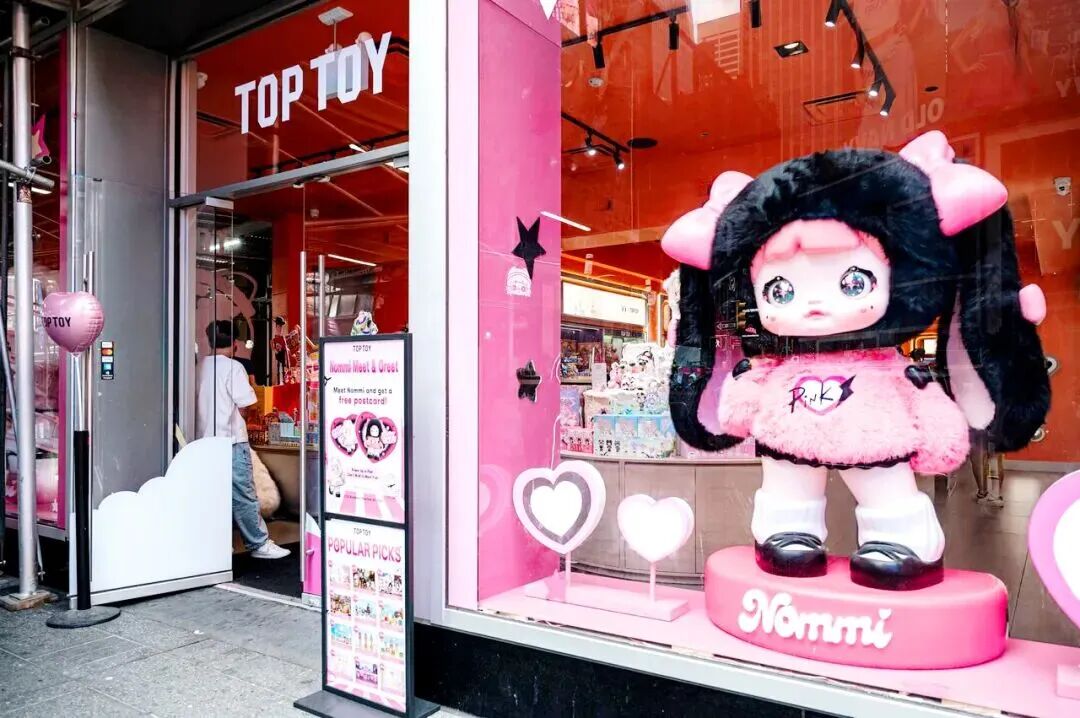
In terms of IP ecology, the total number of TOP TOY's self-owned IPs has now exceeded 30. The best-performing one in terms of revenue is "Nuomier", which was acquired in July 2025. Its GMV has exceeded 200 million yuan last year. The Hangzhou pop-up store of the new IP "yuyu" launched this year achieved a monthly GMV of over 15 million yuan.
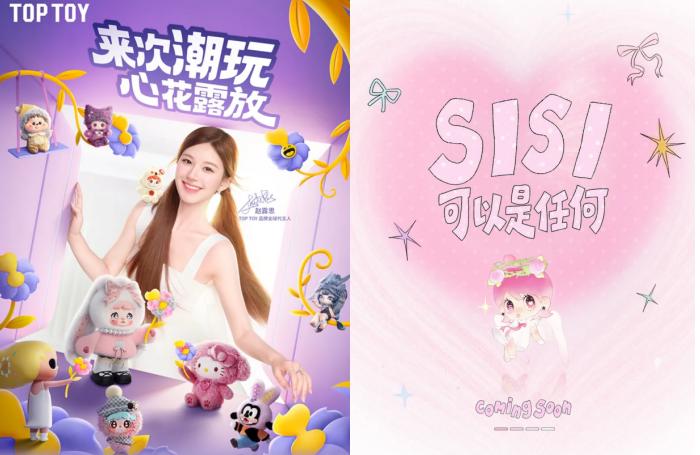
In addition to external acquisitions and signings, TOP TOY also pins its growth hopes on star marketing: in April this year, it officially announced Zhao Lusi as its global brand spokesperson, and exclusively created a new IP "SISI" for the spokesperson, set as a rose girl who escaped from the glass castle, which has accumulated more than 20,000 fans on Xiaohongshu.
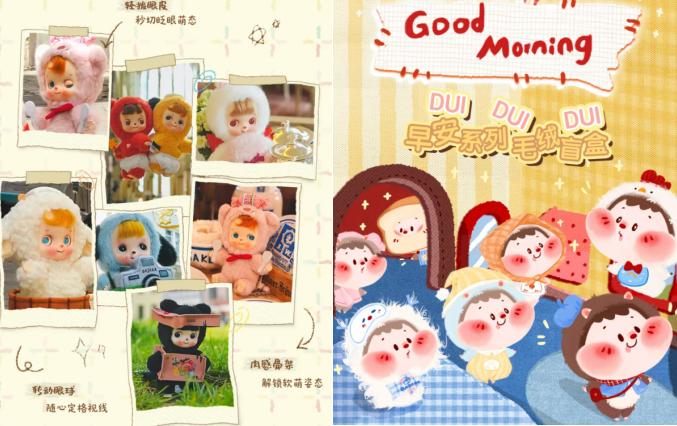
In July, TOP TOY announced two new healing-style IPs "Duiduidui" and "Basaka". The former launched the Good Morning series of plush blind boxes, which means leaving troubles behind yesterday and welcoming the small happiness of the morning; the latter is set as a mysterious group from the extremely cold forest in the north, and launched the "My Favorite Thing Is to Be Happy" series of plush blind boxes.
Bloks, Alpha Group, Xinghui Entertainment, SoftCreate, Jiumu Sundry Society: Deep Cultivation of Their Own Tracks
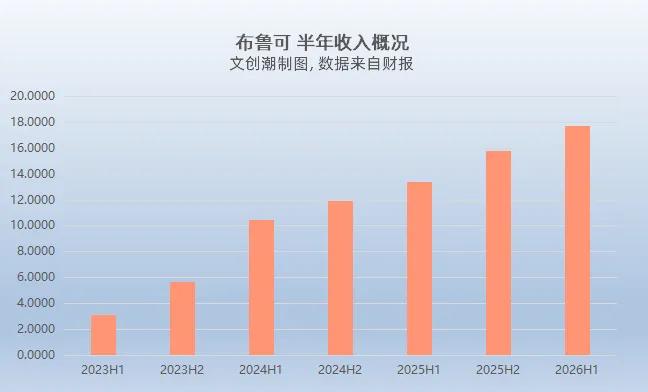
Bloks achieved double growth in revenue and profit in the first half of 2026, with a total revenue of 1.776 billion yuan, a year-on-year increase of 32.7%. The adjusted profit and period profit also achieved year-on-year growth of 25.1% and 30.5% respectively.
Details review: Bloks' revenue of 1.8 billion yuan and profit of 400 million yuan in the first half of the year | Trendy Cultural Express
The path chosen by Bloks is to focus on the building toy category, gain market share by relying on classic Japanese and American IPs, and take product R&D as the core internally. Its R&D expenditure in the first half of the year reached 131 million yuan, accounting for 7.4% of the total revenue, and the R&D team accounts for more than 60% of the total employees.
In terms of IP matrix, Bloks already has 75 licensed IPs, including *Dungeons & Dragons*, Ford, *Cyberpunk 2077*, *Toy Story*, *Zootopia*, *Star Wars*, DC Heroes