The second-generation successors in the pharmaceutical industry are intensively taking over leadership positions, and the power over hundreds of billions of assets is being passed to the post-1995 generation.
A number of "second-generation" successors have stepped onto the front stage in the healthcare industry.
On September 19, both Healthyuan and Livzon Pharmaceutical announced the nomination of Ms. Zhu Linlin as a candidate for non-independent director. Zhu Linlin is the daughter of Zhu Baoguo, the actual controller of Healthyuan and Livzon Pharmaceutical. Born in 1995, Zhu Linlin holds a master's degree in applied economics from Johns Hopkins University. She once served as the deputy marketing director of the Health Products Division of Healthyuan Pharmaceutical Group Co., Ltd., and currently serves as the chairman of Petpal Animal Health (Guangdong) Co., Ltd.
Recently, it is not uncommon for the second-generation successors of pharmaceutical entrepreneurs to enter the management team, from Cai Lei, the eldest son of Cai Dongchen, founder of CSPC Pharmaceutical Group, who took over as the group's CEO at the end of 2025, and Li Xinyi, the daughter of Li Xiaobo, actual controller of Sinocare, who took over as general manager, to Brian Chang, son of Chang Zhaohua, founder of MicroPort Medical, who served as the chairman of the board of MicroPort CardioFlow in 2026, Peng Ling, daughter of Peng Yixing, chairman of Sancheng Medical, who was promoted to executive chairman, then to Yuan Feni, daughter of Yuan Jiandong, actual controller of Bora Pharmaceutical, who joined the board of directors, and Che Yuxuan, son of Che Fengsheng, chairman and controlling shareholder of Sihuan Pharmaceutical, who took office as a new non-independent director — a number of second-generation successors in the healthcare industry are accelerating their march to the core of power.
However, the protagonists who are taking over the power transfer have tacitly chosen to reduce external exposure, and most of the information about the second-generation successors who have entered the management team only comes from the announcements of listed companies. In fact, this group of second-generation successors has quietly led a number of mergers and acquisitions, and has become key figures behind many important cooperations.
According to statistics from VCBeat, among the medical enterprises listed on A-shares and Hong Kong Stock Exchange, many enterprises have completed the second-generation succession or arranged the second-generation members into the core management team.
This power transfer is in sync with the industrial transformation of the pharmaceutical industry, as the domestic medical industry is shifting to innovation-driven development. As the glory of the older generation of entrepreneurs gradually fades, these successors standing in the spotlight are facing their own major tests. How will they lead the enterprises to go through the industry cycle and deliver qualified results?
01
Panorama of Succession in Pharmaceutical Enterprises
In the intergenerational inheritance of the pharmaceutical industry, the age of founders has become the core consideration for enterprises to decide to carry out power transfer. According to statistics from VCBeat, among the 511 domestic A-share listed pharmaceutical companies, the average age of the leaders has reached 57.0 years old, of which those aged 50 to 59 are the absolute main force, accounting for more than 40%; if the scope is expanded to 50 to 69 years old, this proportion is as high as 74.6%.
Even for the Sci-Tech Innovation Board, which represents the innovative force, the average age of the leaders of 108 listed pharmaceutical companies has reached 58.8 years old.
The first generation of private entrepreneurs in China's pharmaceutical industry mostly started from scratch in the 1980s and 1990s, and completed the leap from generic drug following to innovation transformation in 30 years; now, they are generally in the age range of 60 to 75, and corporate governance must directly face inheritance and succession.
There are certain differences between Hong Kong Stock Exchange and A-share markets. A considerable number of the 232 listed pharmaceutical companies on the Hong Kong Stock Exchange are 18A biotech companies (about 50 companies including Innovent Biologics, Akesobio, BeiGene, Zai Lab, Nuocheng Jianhua, Rontan Biological, etc.), whose founders are mostly overseas returnee scientists who have long served as chairman and CEO. This type of company has the smallest number of second-generation members entering the management team.
Since their birth, 18A companies have been highly institutionalized, with early investors and cornerstone shareholders having strong voice in corporate governance. The replacement of management follows market-oriented logic rather than family logic, so 18A biotech companies mostly choose professional management instead of family governance mode.
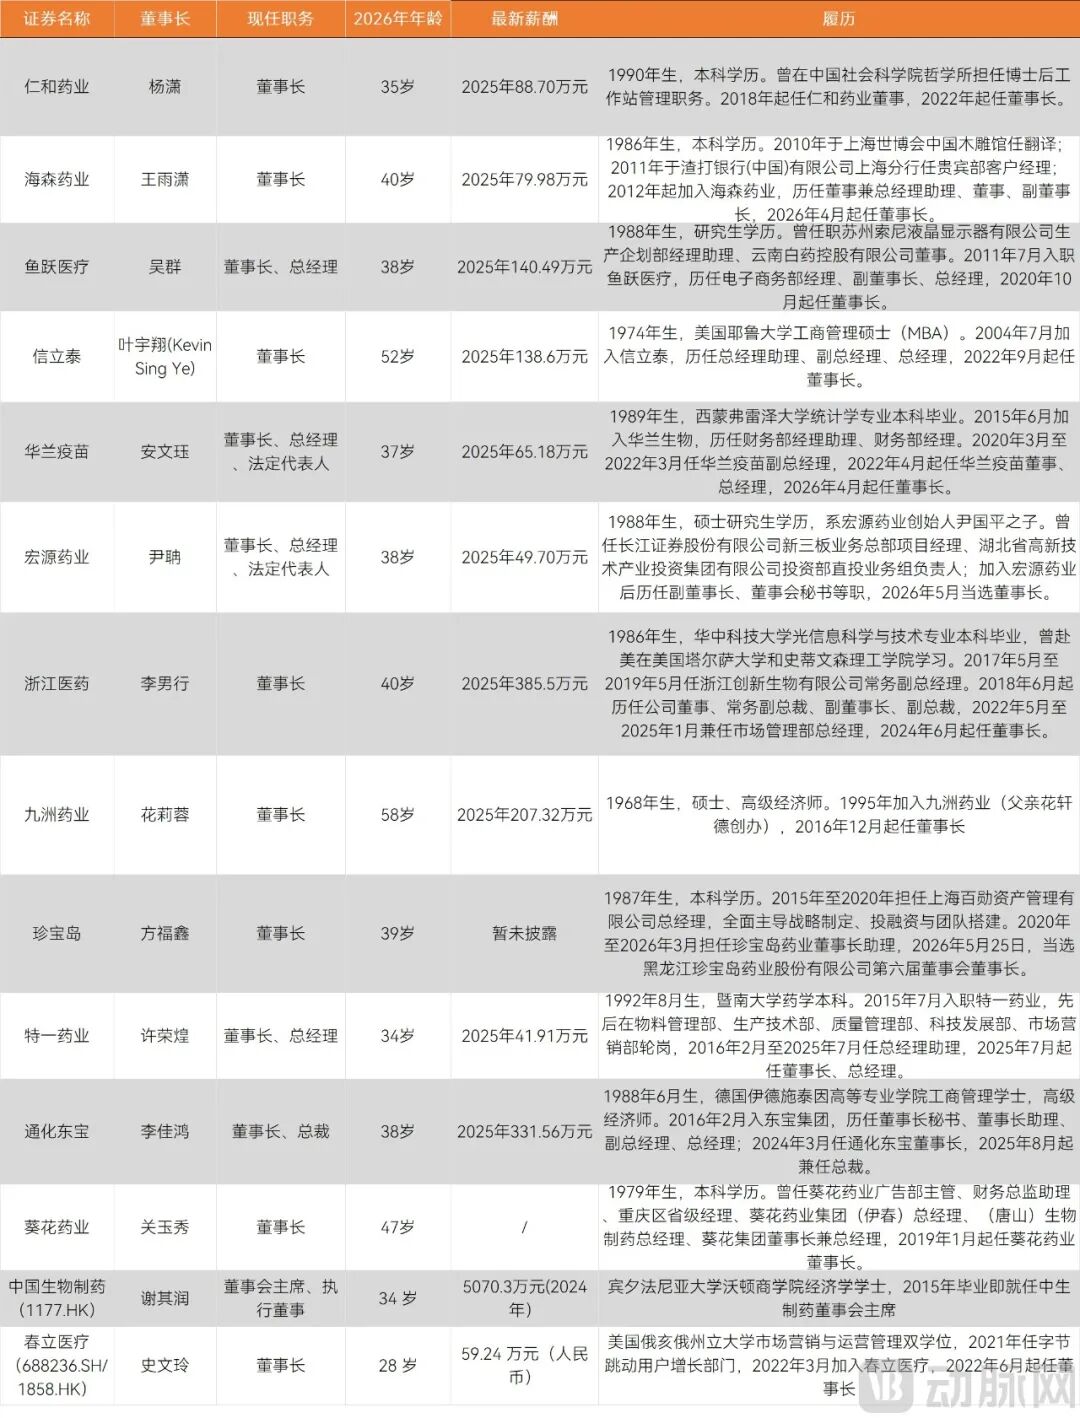
Some listed pharmaceutical companies that have completed second-generation succession
In this round of collective succession, a number of enterprises have taken the lead in completing the second-generation succession, such as Yang Xiao of Renhe Pharmaceutical, Wang Yuxiao of Haisen Pharmaceutical, Wu Qun of Yuwell Medical, Ye Yuxiang of Salubris, An Wenjue of Hualan Vaccine, etc.
Among the enterprises that have completed succession, the completion of succession is usually marked by the dual transfer of power and equity. Most of the second-generation successors obtain actual control or the status of persons acting in concert while taking over the business operation, realizing the inheritance that matches the name and reality.
In terms of educational background, the first generation of entrepreneurs mostly came from industry, pharmaceutical technology and grassroots management, and their knowledge structure was formed in the initial stage of the industry — they understand products, production and market, and rely on the industrial intuition and resource network accumulated from decades of front-line work; while the second-generation successors generally study business, economics, finance, statistics and MBA, forming a composite capability of "international vision + capital operation + modern management".
It is also worth noting that some second-generation successors choose to "follow their parents' footsteps" and continue to study medicine-related majors. In innovative pharmaceutical enterprises, second-generation successors with medical and pharmaceutical backgrounds tend to get involved in R&D and pipeline decision-making earlier, and build a moat for family governance by forging professional barriers.
In terms of succession years, second-generation successors usually need to go through about 9 to 10 years of experience before taking over completely, and they can fully take over after being able to handle affairs independently, so as to ensure a smooth transition of intergenerational handover of the company.
More listed pharmaceutical companies have arranged second-generation members into the management team to prepare for future succession. In our statistical sample, more than 20 A-share companies have completed this layout. These "quasi-successors" have mostly taken core positions such as general manager, vice chairman, and president, forming a co-governance mode with the founders who are still in office.
It can be predicted that with this group of second-generation successors gradually completing their experience, the pharmaceutical industry will usher in a wave of second-generation succession in the next five to ten years.
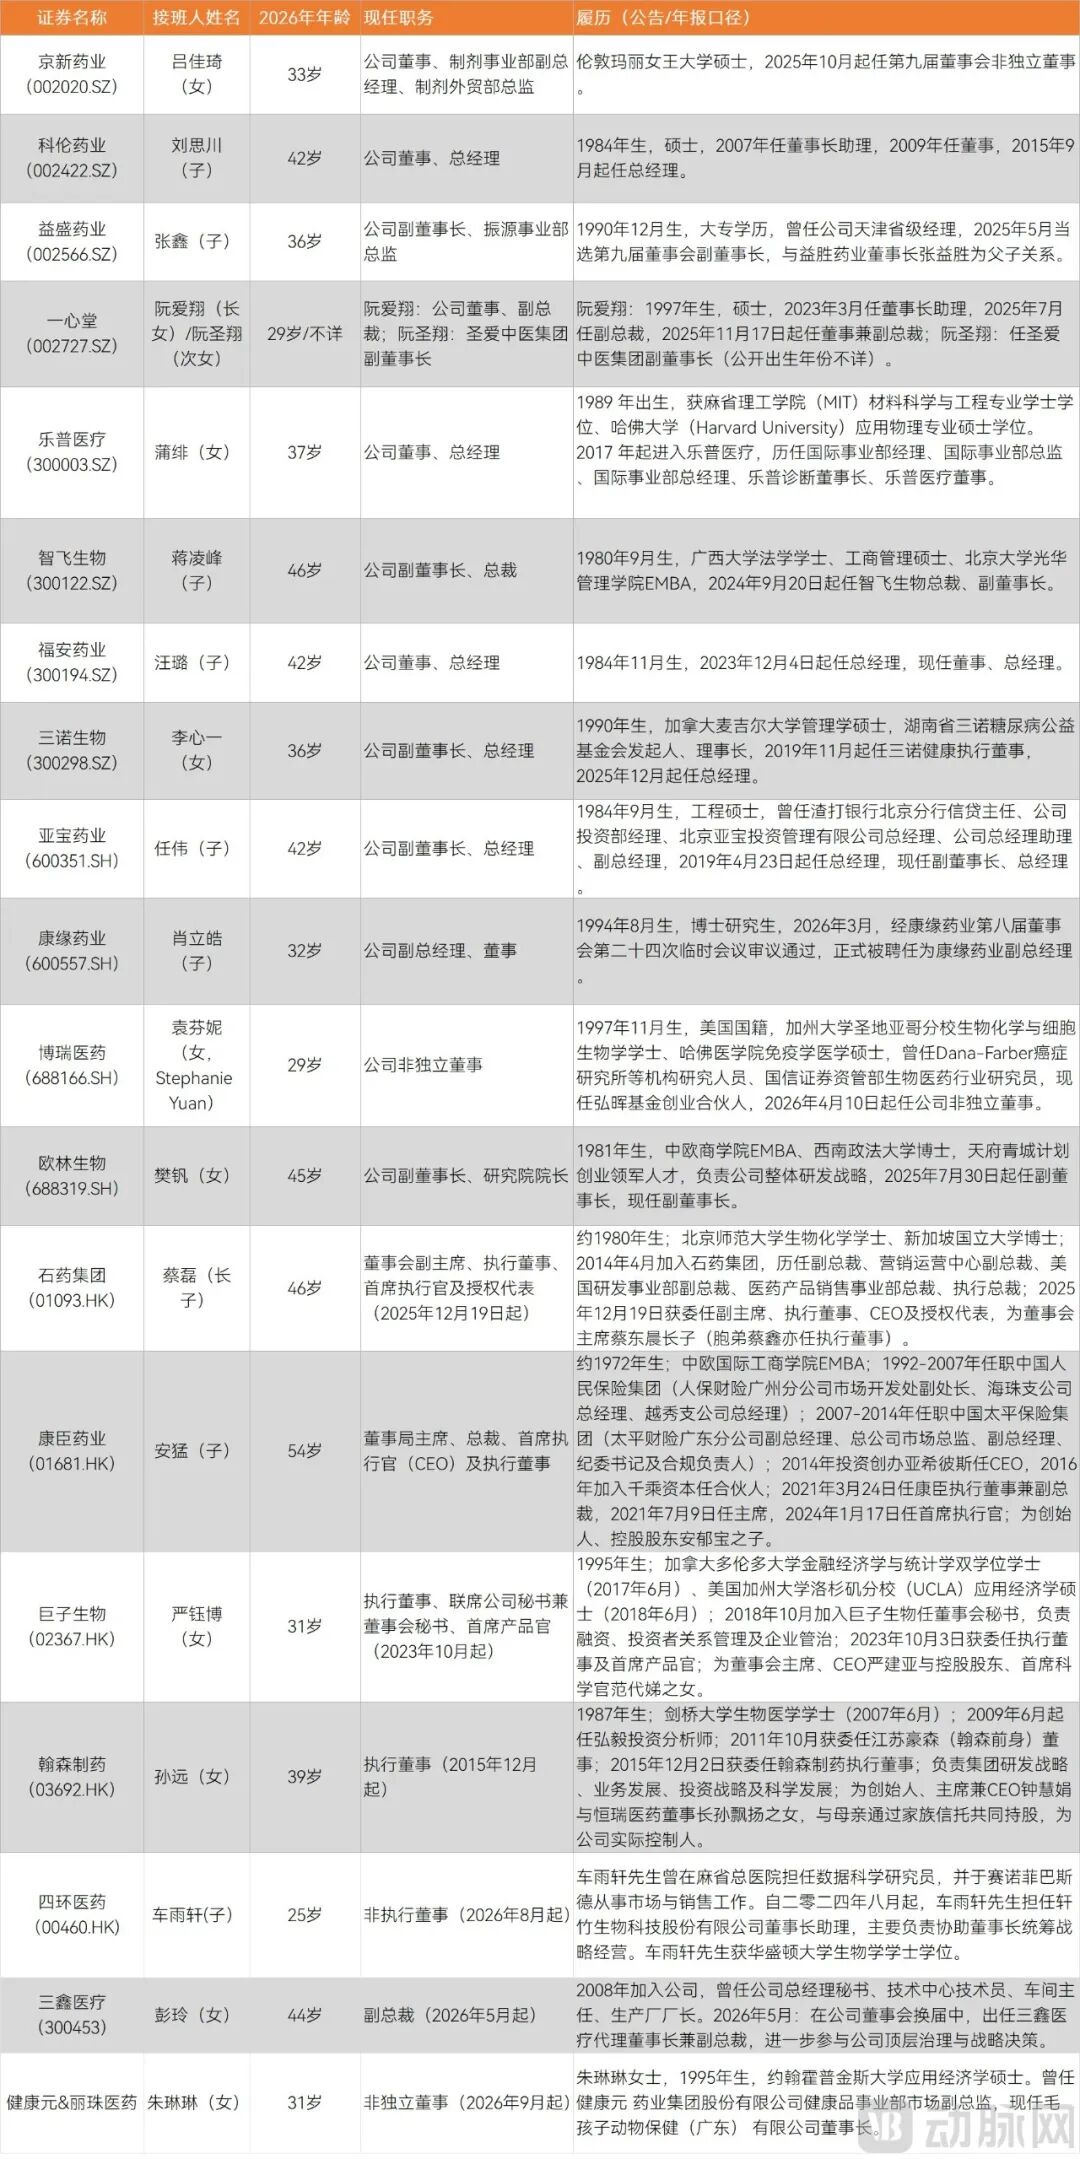
Some listed medical enterprises whose second-generation successors have entered the management team
02
Two Main Paths for Second-generation Succession
Looking forward to the next decade, as a number of "second-generation entrepreneurs" who have entered the core management team gradually complete full succession, the governance model of family enterprises is facing profound reshaping.
In the game between family governance and professional manager governance, many enterprises have made choices in advance to push their children to the front stage for experience. Looking at the current succession groups that have entered the management team, their succession paths present two distinct characteristics: one is "technology-oriented succession" which takes professional technology as the entry point, and the other is "operator-oriented succession" which takes capital operation as the core.
Brian Chang (Chang Yang), son of Chang Zhaohua, founder of MicroPort Medical, is a typical sample of "technology-oriented succession". Dr. Chang is a physician-scientist and engineer with more than 10 years of experience in the medical technology industry. He has co-founded and led the early research, development and business strategy of many medical technology enterprises.
Prior to that, Dr. Chang served as a postdoctoral fellow and lecturer at the Massachusetts Institute of Technology ("MIT"), where he supervised interdisciplinary research teams and developed courses in cardiovascular physiology and medical technology. His academic research focuses on cardiac assist devices and extracorporeal life support systems. He has written 17 peer-reviewed academic papers and is the inventor of a number of patents related to cardiovascular and extracorporeal life support technologies. Dr. Chang has received many honors, including the Paul & Daisy Soros Fellowship, the Seidman Prize for Outstanding Thesis, and teaching awards from Harvard Medical School and MIT.
Dr. Chang received his bachelor's and master's degrees in mechanical engineering from Carnegie Mellon University in December 2013 and May 2014 respectively (graduated with university honors), with a minor in biomedical engineering. He received his Doctor of Philosophy in Medical Engineering and Medical Physics from MIT in June 2018, and his Doctor of Medicine from Harvard Medical School in May 2023 (graduated with magna cum laude). He completed his residency training in internal medicine through the Stanbury physician-scientist program at Massachusetts General Hospital in June 2025.
After breaking through the academic path of "combination of medicine and engineering", Brian Chang joined MicroPort Medical as a medical technology consultant in 2020. He was deeply involved in the clinical verification of core projects such as cardiovascular intervention and surgical robots, played a key role in helping the company's star product Toumai Robot obtain FDA and CE certifications, and helped MicroPort win a key victory in its global expansion journey.
With his first-class academic background and contributions to the commercialization of core products, Brian Chang served as Chief Medical Officer of MicroPort Medical in June 2025, and was appointed as non-executive director of MicroPort CardioFlow in December of the same year. This route of starting from professional technical positions and gradually accumulating management experience provides professional endorsement for his succession.
Parallel to the "technology-oriented succession", another major path is "capital operator-oriented succession". This type of second-generation successors generally have backgrounds in finance, investment banking or overseas business schools, and cut into the core decision-making layer of enterprises through capital operations such as mergers and acquisitions, investment, and BD (business development) global expansion, so as to obtain succession qualifications by quickly delivering performance results.
Wu Bin, son of the actual controller and co-actual controller of Tianyi Medical, is the representative of this path. Wu Bin is currently the director and deputy general manager of Tianyi Medical, with a study experience in Canada, and has been developing in China for 12 years. In 2025, he led two heavyweight cross-border mergers and acquisitions of Tianyi Medical: acquiring the CRRT (Continuous Renal Replacement Therapy) business of Nikkiso, a Japanese hemodialysis giant, for 400 million yuan, and cross-border acquiring the CRRT filter business assets of Italian Bellco, a subsidiary of Medtronic, for 11.99 million euros.
These two transactions helped Tianyi Medical build an independent and closed-loop CRRT product ecosystem. Wu Bin revealed that he has a clear division of labor with his father: his father is in charge of domestic production and operation, while he is responsible for overseas mergers and acquisitions and management. In the next five years, he will focus on promoting the integration of overseas targets into the listed company and realizing the production of overseas factories.
Wu Qun of Yuwell Medical also completed several key mergers and acquisitions after taking over the business, locking in a number of high-growth innovative products. After taking over as chairman in 2020, he rapidly expanded the territory through a series of mergers and acquisitions, successively acquiring Kailete (CGM), Jiangsu Lerun (contact lenses), and subscribing to the equity of Inogen, a North American oxygen concentrator manufacturer. In addition, on the business side, he once promoted the company's e-commerce business revenue to soar from 7 million yuan in 2012 to 600 million yuan in 2016, becoming a phased growth engine. Whether it is in-depth technology cultivation or capital operation, second-generation successors are relying on their respective professional advantages to lead enterprises to find new growth anchors in the fierce industry changes.
03
Second-generation Succession is Deeply Bound to Enterprise Strategic Transformation
The first generation of entrepreneurs mostly started their business relying on generic drugs, raw materials or sales-driven models, and fully enjoyed the industry dividends before the centralized procurement; while when the "second-generation entrepreneurs" took over, they faced a stock game with normalized centralized procurement and compressed profit margins. Under this background, intergenerational handover is deeply bound to the strategic transformation of enterprises, and it has become an inevitable choice to find new growth curves such as innovative drugs and internationalization.
From the perspective of profile, this group of "second-generation entrepreneurs" generally have backgrounds from top European and American universities, and have accumulated practical experience in foreign enterprises, investment banks or private equity institutions. With this composite background, they generally take capital operation and international expansion as the core starting point to break through the bottleneck after taking over.
CSPC Pharmaceutical Group is a typical sample of second-generation successors promoting external cooperation. Cai Lei, the eldest son of founder Cai Dongchen, joined the company in 2014, has long been in charge of the US R&D division, deeply participated in overseas capital docking, Hong Kong stock IPO, and participated in the heavyweight cooperation of 420 million US dollars with AstraZeneca. The second son Cai Xin also has a background in pharmaceutics from Purdue University and working experience in CDH Investments. After returning in 2022, he served as executive president and president of the marketing decision center, focusing on sales business.
The efforts in the BD (business development) field played a key role in CSPC's transformation. In the first half of 2026, CSPC Pharmaceutical Group achieved revenue of 18.594 billion yuan, a year-on-year increase of 40.09%. BD licensing revenue became a highlight of the performance, and the recognition of the BD down payment of the long-acting polypeptide platform brought 5.895 billion yuan of licensing fee revenue to CSPC Pharmaceutical Group.
The case of China Biopharmaceutical reflects the accelerating effect of second-generation successors on innovation transformation. After Xie Qiyun and Xie Chengrun, the fourth-generation members of the Xie family of CP Group, took over the business in an all-round way, they promoted the company's strategic focus to fully shift to innovative drugs. At the level of capital and BD, the company successively acquired enterprises such as Livzon Pharmaceutical, Hegia Bio, and Haoubo, and reached cooperation with Sanofi and GSK, promoting pipeline construction through the two-wheel drive of external introduction and internal R&D.
At present, China Biopharmaceutical has officially entered the intensive harvest period of innovative drugs, with a total of 20 national Class 1 or 2 innovative drugs and 8 biosimilars approved, and its achievement transformation efficiency ranks among the top in the industry. In the first half of 2026, China Biopharmaceutical achieved revenue of 19.44 billion yuan, a year-on-year increase of 10.6%; among which BD revenue was 980 million yuan, a year-on-year surge of 2101.9%, and innovative drug sales revenue was 7.81 billion yuan, a year-on-year increase of 29.2%.
When facing the impact of centralized procurement, second-generation successors also showed the courage to decisively restructure the business structure. Taking Salubris, a leading enterprise in the cardiovascular field, as an example, the current chairman Ye Yuxiang officially took over in 2022. Facing the growth bottleneck caused by the decline of generic drug business, after taking over completely, he firmly anchored the advantageous field of cardiovascular to increase innovation efforts, and sold low-end generic drug projects to recover funds. This transformation has achieved remarkable results: in the first half of 2026, the innovative drug revenue of Salubris accounted for 54.8%, exceeding the traditional business, marking the substantial transfer of business focus. In addition, the third-generation members of the family have entered the management team, showing the planning intention of long-term governance.
On the whole, these cases reflect the common characteristics of second-generation succession in the pharmaceutical industry: intergenerational handover is often accompanied by in-depth strategic adjustment. Second-generation successors are more inclined to deal with industry changes through capital operation and business restructuring, rather than simply continuing the business model of their parents. This intergenerational replacement is essentially an inevitable strategic choice for pharmaceutical enterprises under the dual pressures of normalized centralized procurement and innovation transformation.