August Tea and Coffee Store Ranking: Over 6780 new stores added, more than 3220 stores closed
Data from Yilan Business shows that in August 2026, the total number of stores of 55 brands reached 241,400, a 2.50% increase month-on-month. The resumption of operation of most campus stores during the September school opening season is the main reason for the rebound in the total number of stores this month.
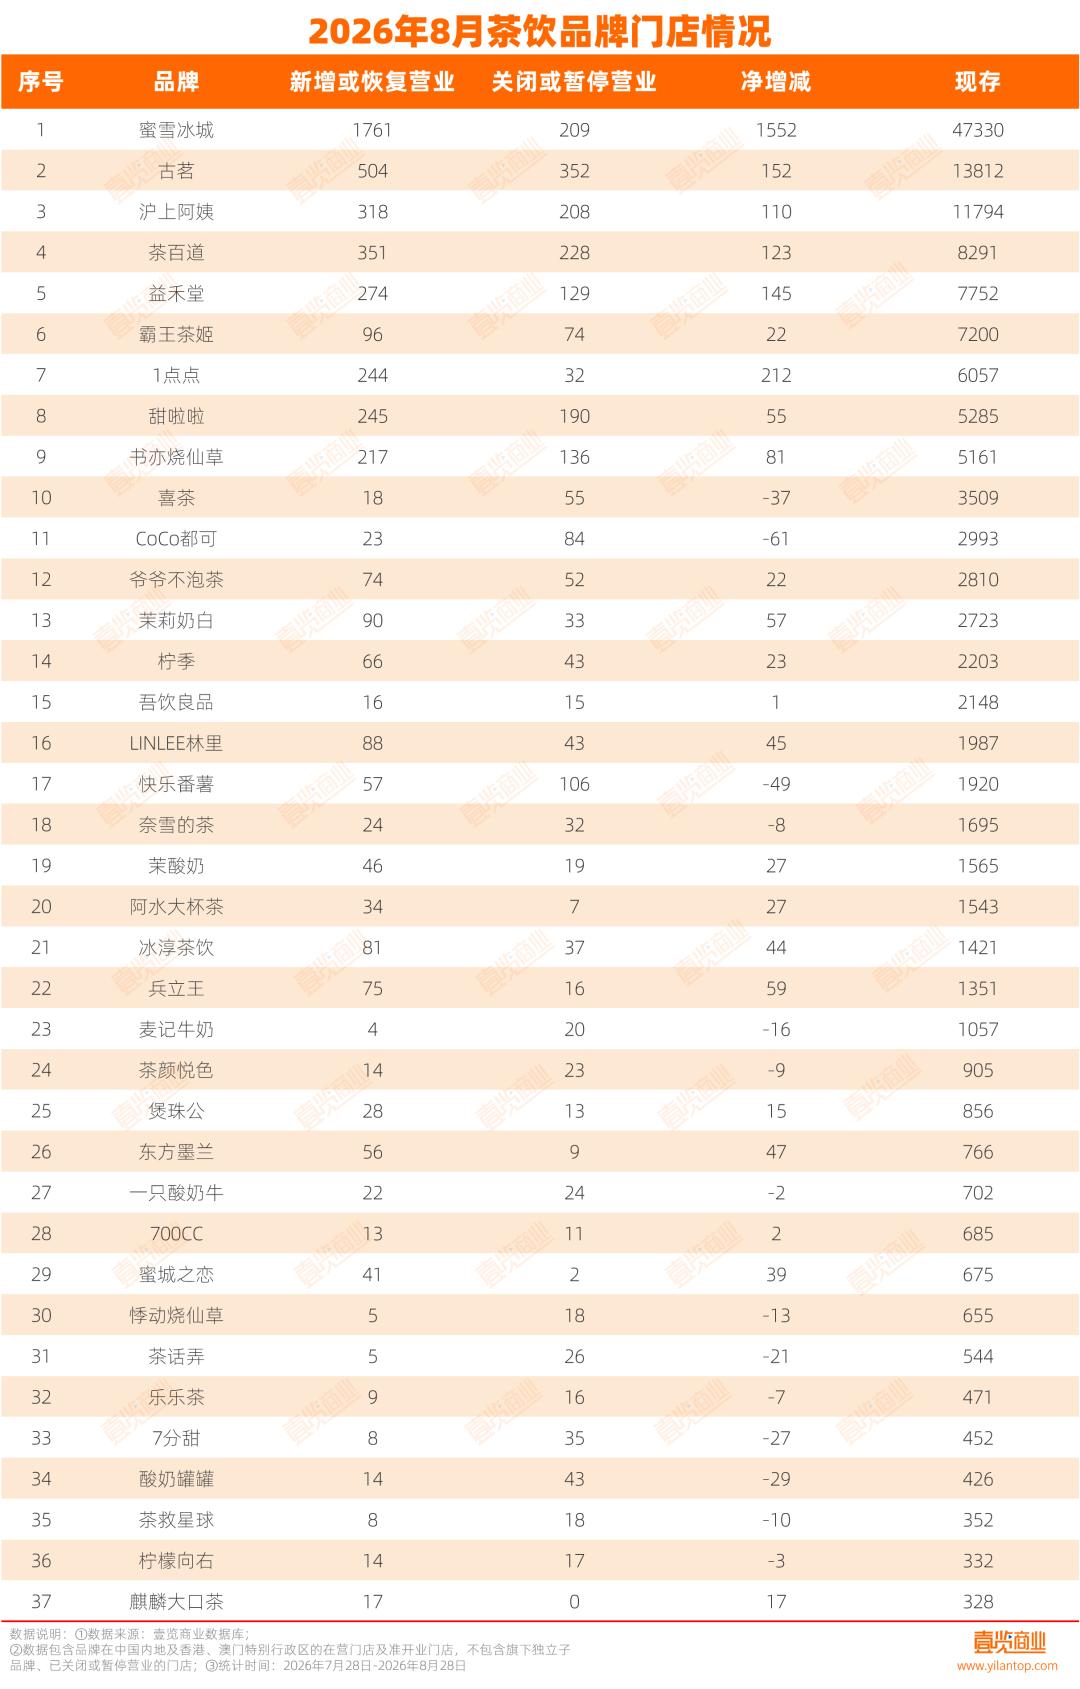
After excluding Luckin Coffee and Cotti Coffee, which were included for the first time this month, the original 53 brands opened 6,780 new stores and closed 3,223 stores in a single month, with an actual net increase of 3,557. Among them, the overall scale of the tea beverage industry is large and the pattern is solidified, the head brands have obvious advantages, the echelon threshold is clear, and it is difficult for small and medium-sized brands to shake the leading position.
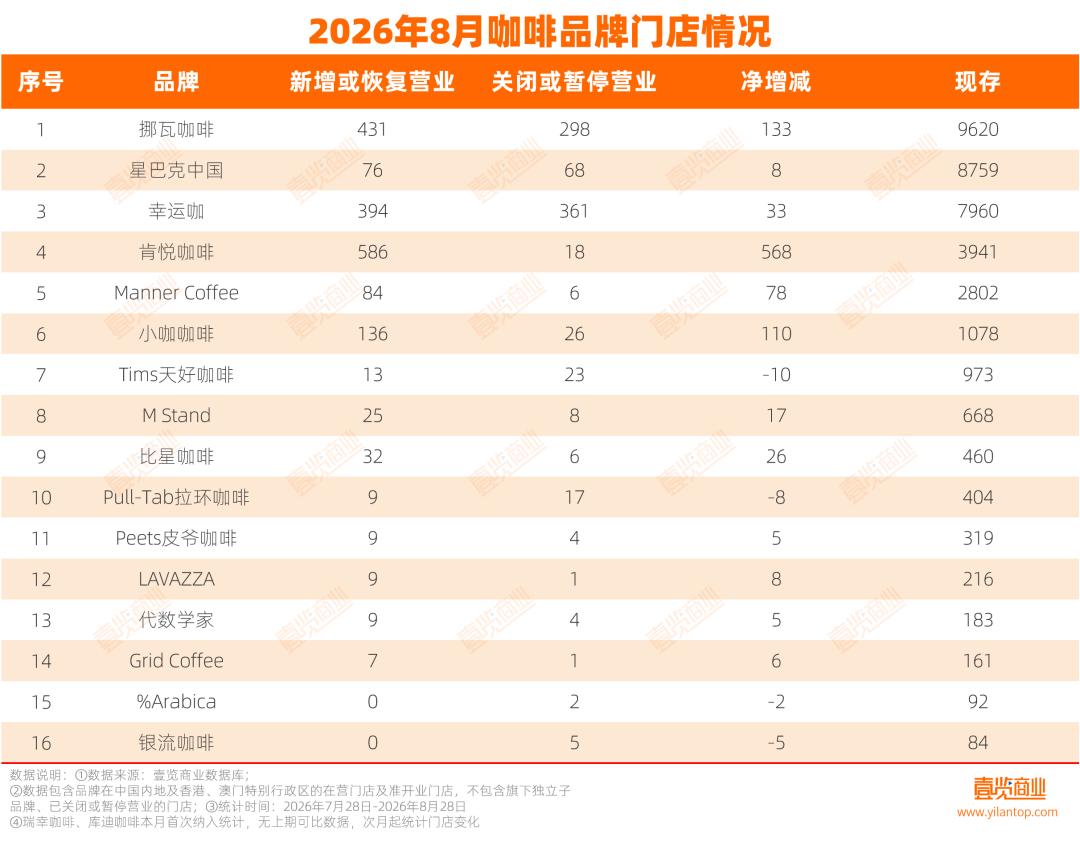
The differentiation in the coffee industry is remarkable. Local brands such as Nowwa Coffee and Lucky Coffee continue to expand their stores. In contrast, the expansion pace of traditional foreign brands represented by Starbucks China and Tims China has slowed down and even shown negative growth.
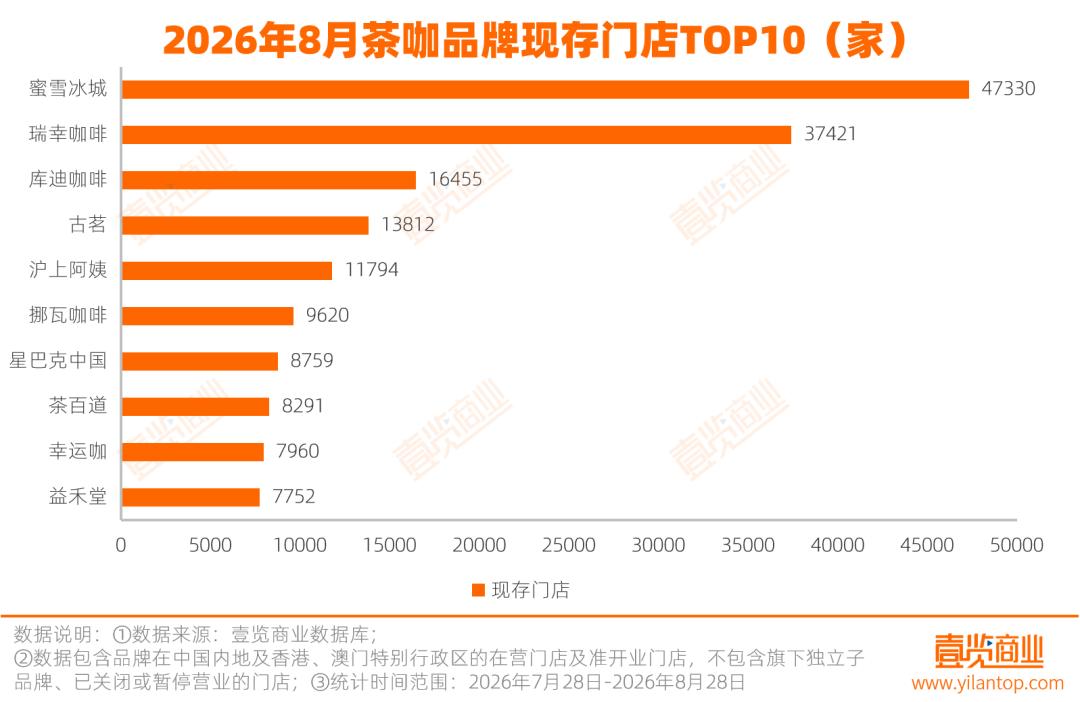
From the perspective of store scale, the overall scale is flat compared with last month, and the echelon pattern is stable. Mixue Bingcheng is the only brand that has exceeded 40,000 stores, firmly ranking in the first echelon of the industry. Luckin Coffee and Cotti Coffee rank second and third respectively; Guming and Aunt Hu's Shanghai have both crossed the threshold of 10,000 stores; the total number of stores of Nowwa Coffee, Starbucks China and Cha Baidao are all above 8,000.
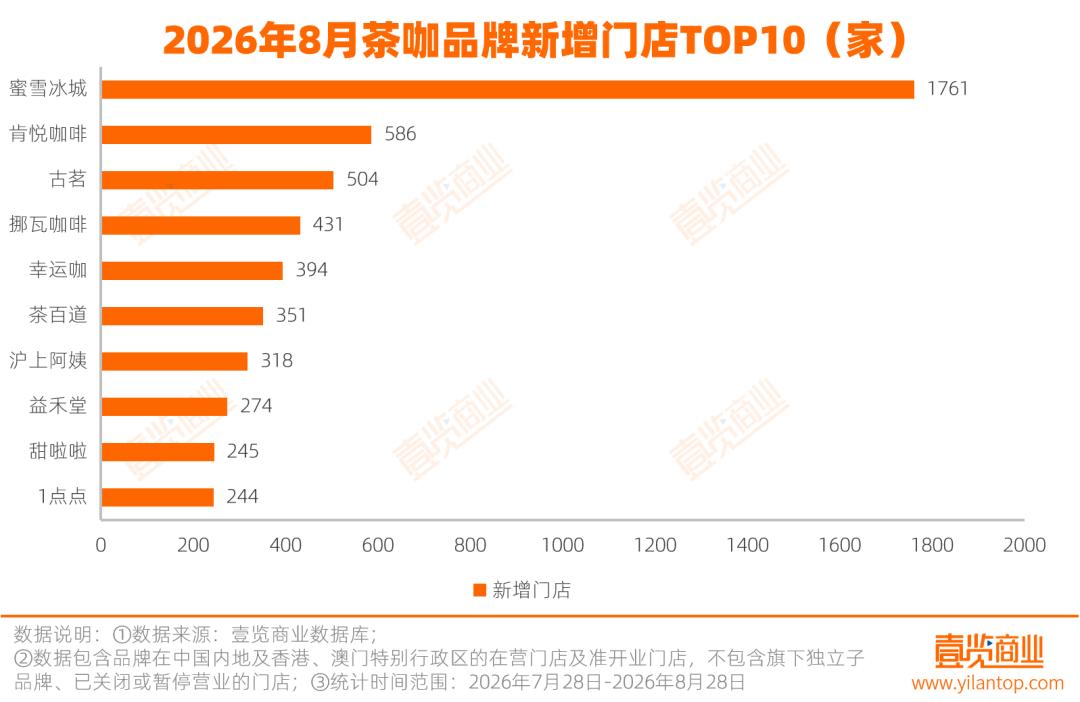
The expansion speed of leading brands has increased. In terms of new stores, 53 mainstream brands added 6,780 new stores in the month, an increase of 48.68% over the previous month. The top ten brands all added more than 240 new stores, higher than 148 in July. Mixue Bingcheng added 1,761 new stores in a single month, leading by a large margin. Kenyue Coffee added 586 new stores, Guming added 504 new stores, and 4 brands including Nowwa Coffee and Lucky Coffee all added more than 300 new stores.
It is worth mentioning that Lucky Coffee surpassed Shuyi Shaoxiancao and ranked among the top ten in the number of new stores. From the perspective of brand performance, the current store expansion is still concentrated in brands with scale advantages and channel capabilities.
While expanding new stores, industry adjustments have slowed down. From the perspective of closed or suspended stores, 53 mainstream brands closed or suspended 3,223 stores in the month, a decrease of 53.30% compared with the previous month. July was mainly affected by the summer vacation, and campus stores entered a seasonal contraction cycle. The market is expected to gradually recover after the September school opening season.
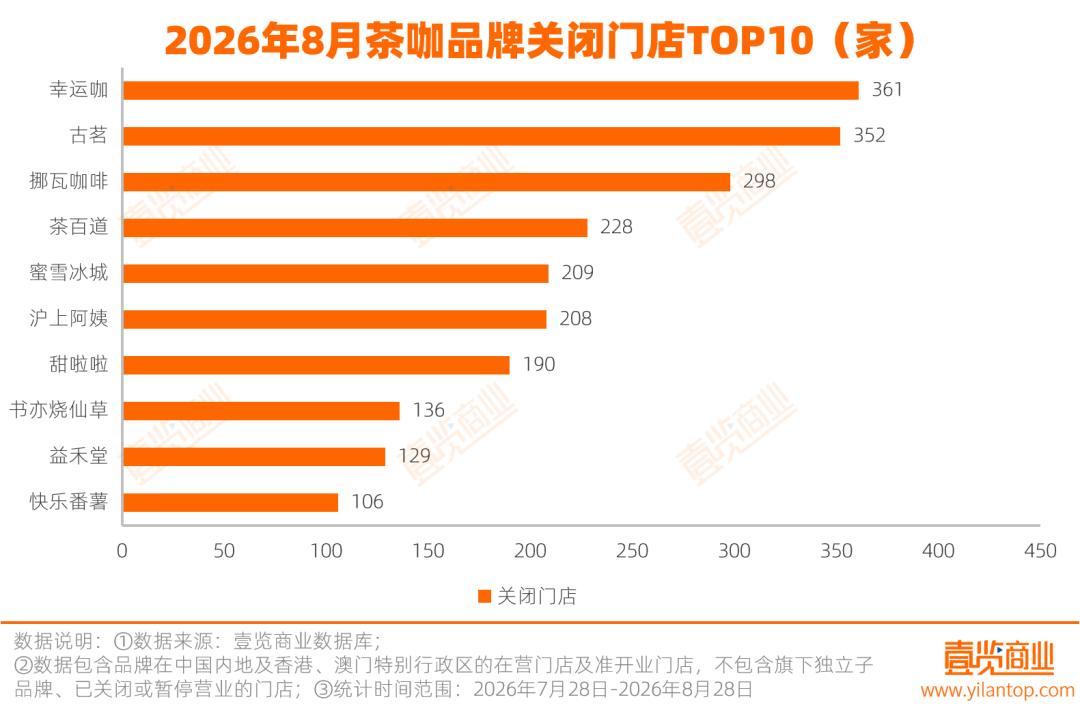
The adjustment range of leading brands narrowed this month, and the top ten brands all closed or suspended more than 106 stores. Lucky Coffee closed or suspended 361 stores, ranking first. 5 brands including Guming, Nowwa Coffee, and Cha Baidao closed or suspended more than 200 stores. Happy Sweet Potato surpassed Kenyue Coffee and entered the top ten of the store closure list.
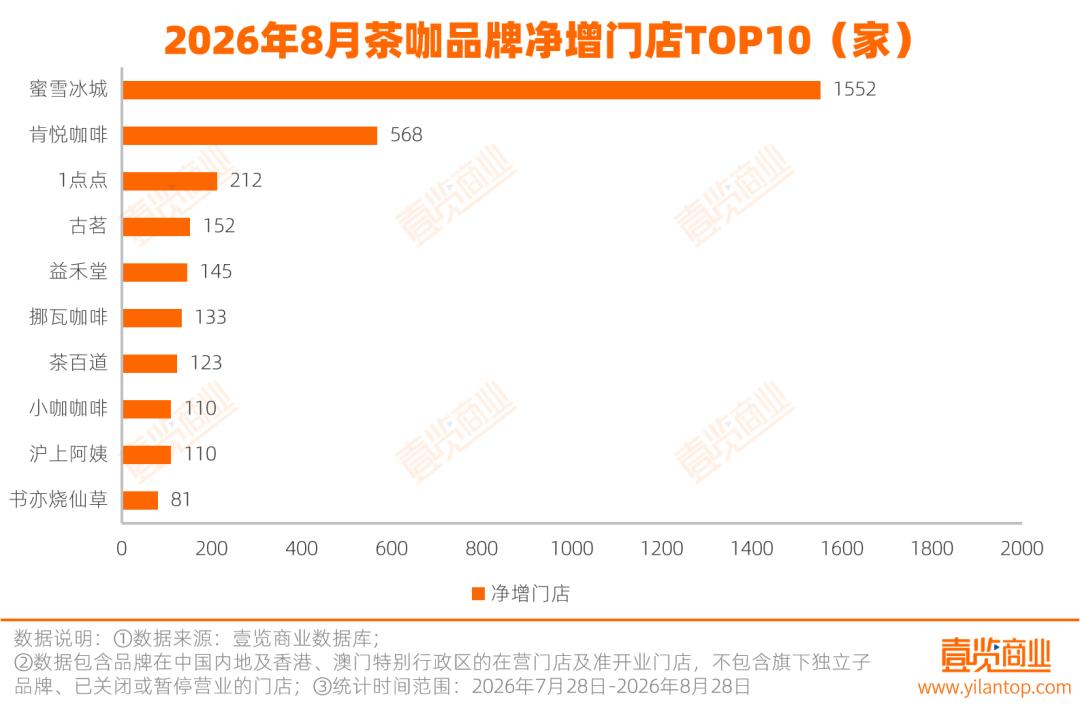
From the perspective of the final change in net increase of stores, brand differentiation further expanded in August, and the head effect is significant. With the advantage of new stores, Mixue Bingcheng achieved a net increase of 1,552, becoming the fastest growing brand this month. Kenyue Coffee followed closely with a net increase of 568, and 7 brands including Yidiandian, Guming, Yihetang, and Nowwa Coffee achieved a net increase of over 100 stores.
Kenyue Coffee continues the previous expansion rhythm and maintains a high growth trend. Since there were 2,297 stores in December 2025, the total net increase in 9 months has reached 1,644, with an average monthly net increase of about 205.5. Xiaoka Coffee also performed well, with a net increase of 110 stores this month, and the total number of stores climbed to 1,078.
Brands such as 7-minute Sweet, Yogurt Can, and Chahua Nong continue to shrink. Even though the September school opening season drove most campus stores to resume operations, it failed to reverse the trend of store contraction. Behind this, there are not only active changes in channel structure adjustment, but also passive responses to strategic contraction, reflecting the realistic pressure faced by brands under the current competitive landscape.
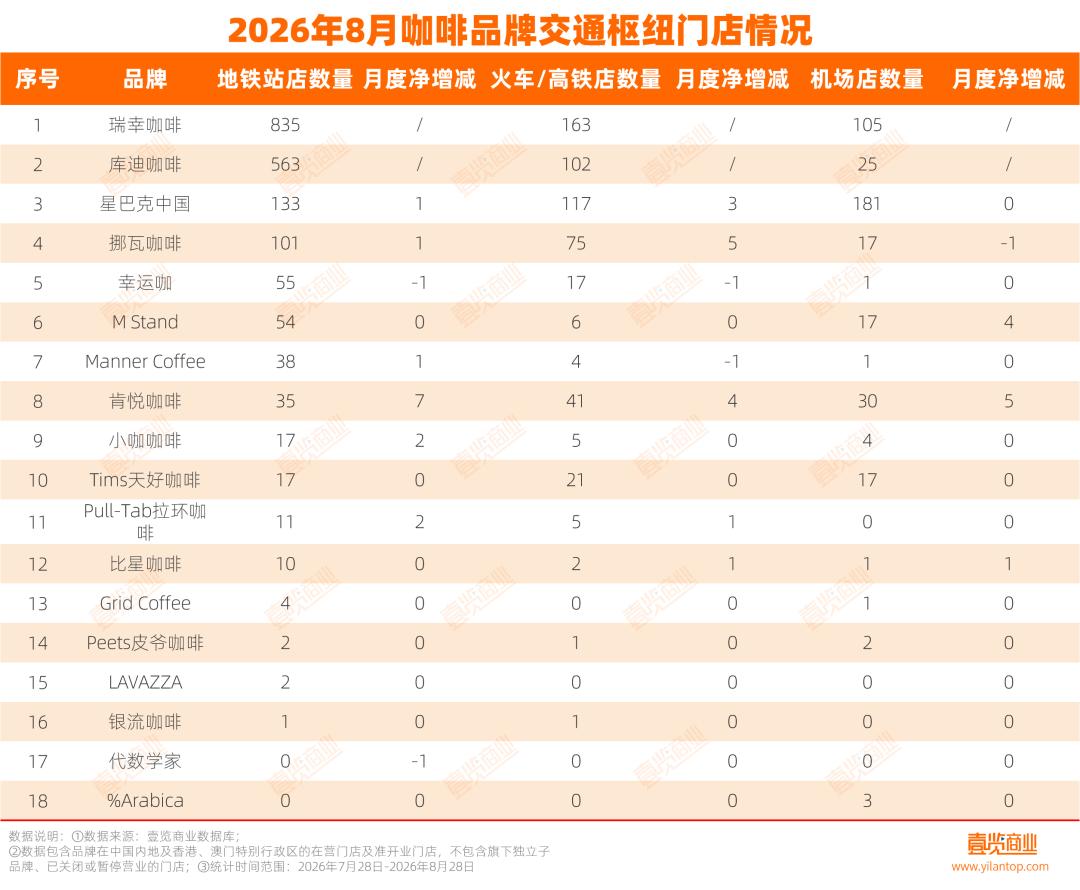
From the perspective of transportation hub locations, the transportation hub channel has generally entered the stage of stock game. In August, 55 tea and coffee brands had a total of 3,367 subway station stores, 1,212 train or high-speed rail station stores, and 604 airport stores. It is worth noting that except for a few brands, the monthly net change of most brands fluctuates within 3 units, and expansion decisions are generally cautious.
Airport stores are windows for brand display. Coffee brands have signed contracts in advance, and locked these advantageous locations through long-term contracts and priority renewal rights. As late entrants, tea beverage brands can only choose secondary stores even if they are willing to pay higher rents, resulting in a greatly reduced passenger flow conversion rate. Coupled with the high rent cost of airport stores, the single-store profit model is more difficult to establish.
From the stock perspective, Starbucks China alone occupies 181 airport stores, more than the sum of all tea beverage brands' airport stores. It is nearly 1.7 times that of the second-ranked Luckin Coffee. Kenyue Coffee added 5 net new airport stores this month, and M Stand added 4 net new stores, which are the few growth points in the airport channel.
Tea beverage brands such as Mixue Bingcheng, Shuyi Shaoxiancao, and Cha Baidao generally have about 15 airport stores, which play a more "supplementary" role.
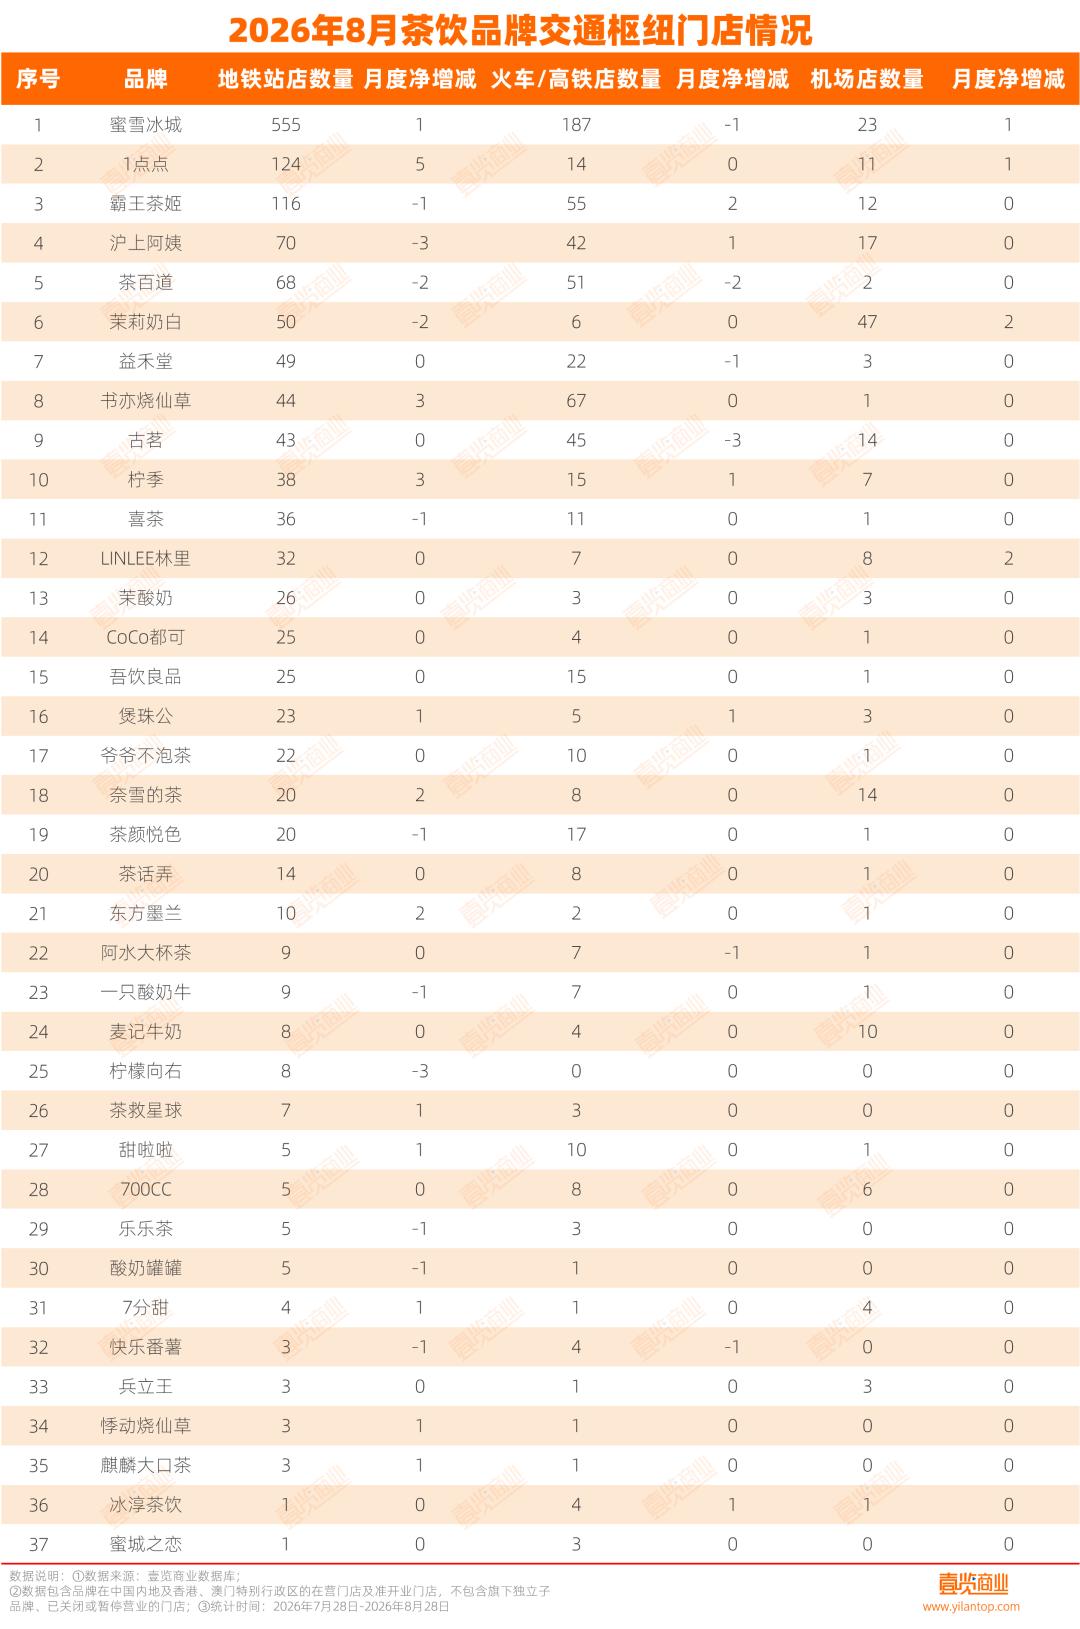
The brand concentration in the subway station channel is at a high level. Luckin Coffee has 835 stores and Cotti Coffee has 563 stores. The two brands have a total of 1,398 stores, accounting for more than 40% of the total, building a scale barrier. Except for Mixue Bingcheng, no other single brand has exceeded 150 stores.
The train or high-speed rail station channel also continues the leading pattern dominated by top brands, led by Luckin Coffee, Cotti Coffee, and Starbucks China, all of which have more than 100 stores. Nowwa Coffee ranks fourth with 75 stores, reflecting the coffee brands' heavy bet on the transportation hub channel.
However, 10,000-store level tea beverage brands such as Guming, Aunt Hu's Shanghai, and Cha Baidao generally only have 40-50 stores at high-speed rail stations, which do not match their total number of stores, with relatively insufficient penetration.
The incremental space of the shopping mall channel has reached its peak. After excluding Luckin Coffee and Cotti Coffee, the original 53 brands only had a net increase of 147 stores. Among them, Kenyue Coffee expanded against the trend, adding 104 new shopping mall stores in a single month, accounting for nearly 70% of the total new stores in this channel.
Pull-Tab Coffee, Tea Rescue Planet, Yogurt Can, and 7-minute Sweet continue to show negative growth in the shopping mall channel, which is consistent with their overall store contraction trend, facing adjustment pressure.
This article is from the WeChat official account "Tea & Coffee Observer", authors: Huang Linan, Lei Jun, editor: Yang Yu, published with authorization from 36Kr.