Post anti-VEGF Era: A $10-billion "hidden battle" in the ocular fundus field
An acquisition worth up to 3.325 billion US dollars adds new fuel to the iterative wave of new global ophthalmic drugs.
On November 16, Johnson & Johnson announced the acquisition of ophthalmic biotech firm Ollin Biosciences. With the consideration of 2.2 billion US dollars as upfront payment plus up to 1.125 billion US dollars in regulatory and commercial milestones, it has taken two ophthalmic bispecific antibody pipelines under its wing: one is OLN324, a VEGF/Ang2 bispecific antibody that has advanced to Phase III clinical trials for wet age-related macular degeneration (wAMD) and diabetic macular edema (DME); the other is OLN102, an IGF-1R/TSHR bispecific antibody for thyroid eye disease (TED). The former is sourced from Innovent Biologics, while the latter comes from Orange Pharma.
Looking back at the evolution trend of ophthalmology over the past 20 years, Eylea, with better efficacy and compliance, has overtaken its competitors to become the top-selling ophthalmic drug of its generation; Vabysmo targeted the opportunity of next-generation anti-VEGF ophthalmic drugs, and achieved explosive sales immediately after launch thanks to its longer dosing interval. OLN324 aims to go a step further: its dual-target design can control fundus neovascularization at a deeper level, and has shown clinical advantages in early head-to-head studies with Vabysmo.
In other words, Johnson & Johnson is betting on the next blockbuster ophthalmic drug. This is not hard to understand. Driven by both population aging and the rising prevalence of diabetes, the ophthalmic drug market has already exceeded the scale of 100 billion US dollars, but the treatment bottleneck of traditional anti-VEGF drugs has become increasingly prominent — the compliance problem of repeated intraocular injections, insufficient response in some patients, and long-term efficacy attenuation together form a clear unmet clinical need.
A sufficiently clear market pain point is enough to create huge commercial returns, attracting pharmaceutical companies of all sizes at home and abroad to compete for layout. Ollin's pipeline is only the tip of the iceberg among numerous innovative ophthalmic pipelines. The global R&D of fundus drugs has long shifted from the "involution" of single targets to a multi-dimensional race covering bispecific/multispecific antibodies, long-acting sustained release and even gene therapy.
01
The 100-billion-dollar market and its ceiling
In the landscape of ophthalmic medications, fundus diseases are undoubtedly the high-value golden track, far from being saturated.
According to the data disclosed at EyePoint's 2025 Investor Day, the combined market size of branded drugs for the three major indications of wet age-related macular degeneration (nAMD), diabetic macular edema (DME) and retinal vein occlusion (RVO) has exceeded 12 billion US dollars globally. Among them, the two major indications of nAMD and DME account for more than 80%, making them the absolute main force of the market.
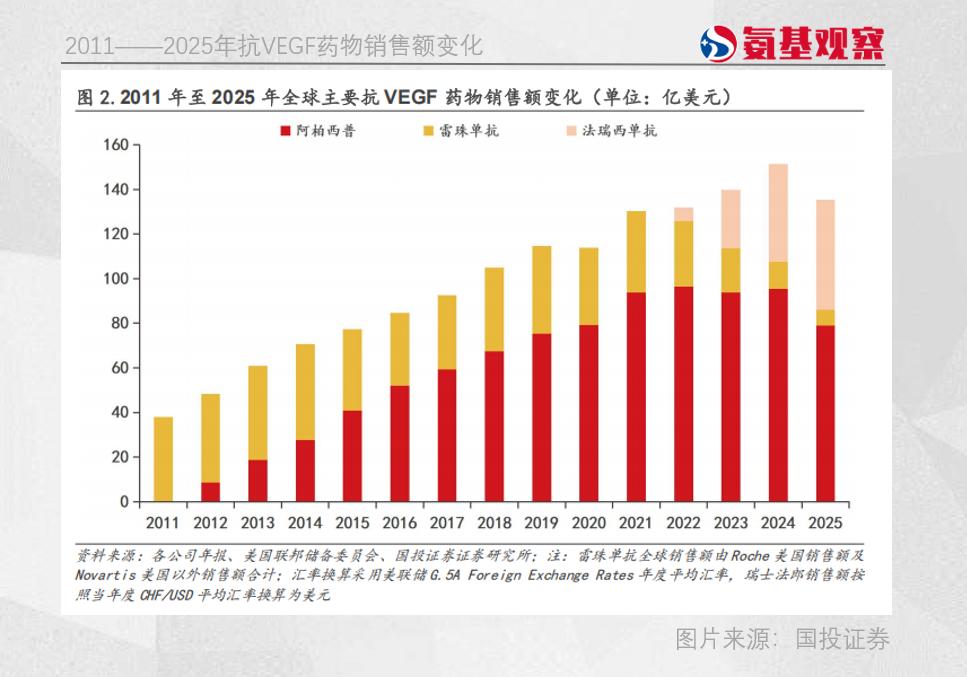
The growth logic on the demand side remains solid: population aging continues to push up the number of patients with macular degeneration, the expansion of the global diabetic patient base steadily increases the diagnosis and treatment demand for DME and diabetic retinopathy, and superimposed with the long-term eye disease burden of the myopic population, the expansion of the fundus disease market is still ongoing.
However, the traditional anti-VEGF drugs that support this 100-billion-dollar market are hitting the ceiling of clinical limitations.
Taking nAMD and DME as examples, anti-VEGF drugs improve patient prognosis by inhibiting abnormal angiogenesis and vascular leakage. But such diseases usually require long-term management, and patients often need repeated intravitreal injections, leading to poor compliance.
Especially for DME, a considerable number of patients still have insufficient response to anti-VEGF treatment in clinical practice, and some cannot achieve sustained retinal fluid control during long-term treatment.
Prolonging the dosing interval, deeply clearing effusion, and conquering drug-resistant populations — these three unmet clinical needs constitute the core logic for the breakthrough of new-generation ophthalmic drugs.
Vabysmo is the first "next-generation" player that stands out. As the world's first approved VEGF/Ang2 bispecific antibody, it targets both VEGF-A and Ang2, which not only inhibits abnormal angiogenesis, but also improves vascular stability, and is equally effective for patients with insufficient response to previous anti-VEGF treatment.
The growth momentum of Vabysmo after launch verifies the commercial value of this direction: its global sales reached 4.102 billion Swiss francs in 2025, a year-on-year increase of 12%; in the third quarter of 2026, its sales reached 3.2 billion Swiss francs, a year-on-year increase of 10%, and it is still seizing market share from Eylea.
But Vabysmo is not the end point. At present, it still needs to be injected every 4 weeks in the initial treatment stage, and the dosing interval in the maintenance period still has room for further extension; at the same time, reports of rare ocular safety events such as retinal vasculitis have emerged after launch, and long-term safety still requires continuous monitoring.
In other words, between the huge market demand and the existing therapies that still have shortcomings, the window for latecomers remains open.
02
3.3 billion US dollars heavy bet: what is Johnson & Johnson targeting
Facing the huge potential of the ophthalmic drug market and clear clinical needs, multinational pharmaceutical companies have begun to increase their bets on next-generation ophthalmic pipelines.
Johnson & Johnson's acquisition of Ollin for 3.3 billion US dollars is essentially to strengthen its ophthalmic pipeline, and directly obtain the core qualification to compete for the next-generation ophthalmic drug with real money.
The structure of this transaction is also thought-provoking. In addition to the total consideration of 2.2 billion US dollars upfront payment and 1.125 billion US dollars in milestones, Johnson & Johnson also simultaneously reached an independent R&D financing agreement with Blackstone. Blackstone will contribute 750 million US dollars to support the Phase III clinical development of OLN324, in exchange for corresponding milestone payments and a single-digit sales share.
The endorsement of top-tier investment institutions indicates on the side that they recognize the asset quality of OLN324. Whether in terms of structural design or early clinical performance, this bispecific antibody has the potential to hit the Best-in-Class (BIC) level.
According to the information disclosed by Ollin, OLN324 is also a VEGF/Ang2 bispecific antibody, but it adopts a more miniaturized antibody structure (minibody) with high Ang2 inhibitory potency, which achieves more sufficient dual-target intervention at a higher molar dose, and can theoretically bring better retinal fluid control effect and longer duration of action.
The head-to-head clinical study conducted between OLN324 and Vabysmo provides more direct evidence of efficacy.
In January 2026, Ollos announced the Phase Ib clinical data comparing OLN324 and Vabysmo in treating patients with wAMD or DME: among DME patients, the OLN324 4mg group showed faster and more significant retinal anatomical improvement. At week 12, nearly 90% of patients reached the DME-free state, compared with 57% in the Vabysmo group.
In March, Ollin further released the complete 20-week data. Among DME patients, the OLN324 treatment group still maintained a good retinal drying effect within 12 weeks after the last mandatory administration. Among them, 93% of patients in the OLN324 4mg group did not need retreatment, compared with 89% in the Vabysmo group.
In terms of vision improvement, the OLN324 4mg group also maintained advantages. Among wAMD patients, the OLN324 4mg group had an improvement in best corrected visual acuity that was numerically about 2.2 letters higher than that of the Vabysmo group at week 20. In addition, OLN324 also showed faster and more durable effects in improving the thickness of pigment epithelial detachment (PED).
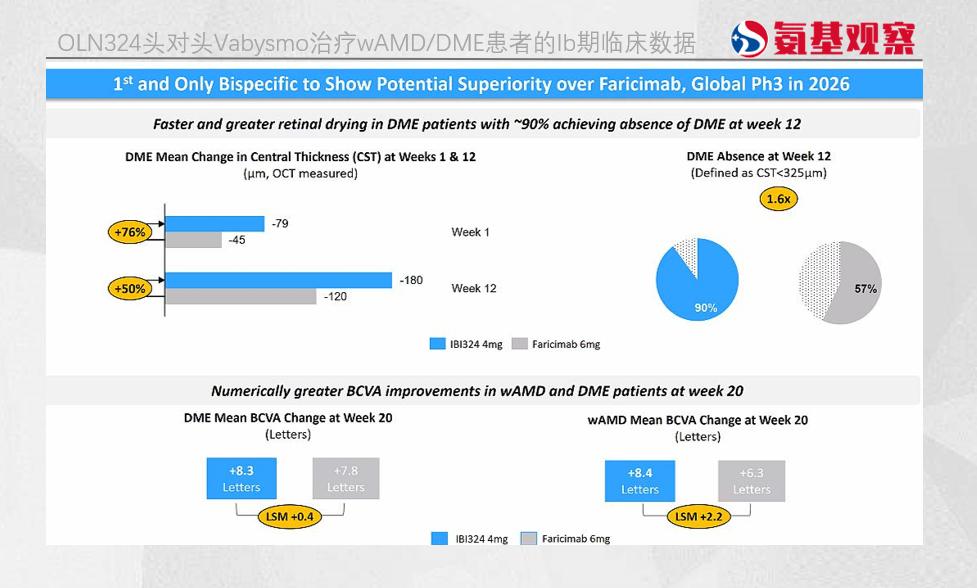
Whether in anatomical improvement or vision improvement, OLN324 is superior to Vabysmo. Of course, this is only a Phase Ib study with limited sample size and follow-up time, and OLN324 still requires larger-scale studies to verify its effectiveness. But the advantages demonstrated by direct head-to-head comparison are enough to support Johnson & Johnson's determination to place the bet.
Another preclinical pipeline, the IGF-1R/TSHR bispecific antibody OLN102, supplements Johnson & Johnson's layout in the TED field.
TED is an orbital inflammatory disease closely related to autoimmune thyroid diseases. Patients may experience exophthalmos, diplopia, eyelid retraction, and in severe cases even optic nerve compression and visual impairment.
IGF-1R is already a clinically validated therapeutic target. Tepezza (teprotumumab) exerts its effect by inhibiting IGF-1R and is the first approved non-surgical drug for TED. OLN102 further adds TSHR inhibition on the basis of IGF-1R. TSHR plays an important role in the treatment of Graves' disease, and its combined action with IGF-1R can produce a synergistic effect, which theoretically leads to stronger efficacy.
On this target combination, the research of Innovent Biologics' same-target bispecific antibody IBI3031 for TED indication has also advanced to the Phase I clinical stage.
03
Rising waves: three main innovation lines for next-generation ophthalmic drugs
Johnson & Johnson's acquisition is just the tip of the iceberg. Looking at the world, the R&D wave of innovative ophthalmic drugs has long been surging, with multi-dimensional innovations in target mechanisms, delivery technologies and treatment paradigms advancing side by side, and the competition dimension has long jumped out of the framework of traditional anti-VEGF therapies.
· Target upgrading: from bispecific antibodies to multi-target, fully covering vascular pathology
In terms of targets, VEGF/Ang2 bispecific antibodies are currently the most mature and most competitive direction. In addition to Vabysmo and OLN324 acquired by Johnson & Johnson, BI-836880 from Boehringer Ingelheim is a VEGF/Ang2 bispecific nanobody, which adopts a molecular form different from traditional bispecific antibodies and has entered Phase I/II clinical development.
VIS-101 from New Bridge Biotech is also noteworthy. It is a novel tetravalent bispecific antibody targeting VEGF-A and ANG-2. The tetravalent molecular structure prolongs the half-life, and Phase I data shows that half of the patients have a dosing frequency of more than 6 months. Recently, this product just announced the administration of the first patient in the Phase IIb trial.
In addition to dual targets, more extensive multi-target fusion proteins are also advancing simultaneously. GenSci148 from Gensci Pharmaceutical covers four targets: VEGF-A, VEGF-C, VEGF-D and Ang2, and intervenes in abnormal angiogenesis, vascular permeability and stability through multiple pathways. This product was approved for clinical trials in China in August 2026.
The combinations are not limited to VEGF/Ang2 bispecific antibodies, and combinations of VEGF with FGF, complement, Tie2, IL-6 and other targets are also emerging continuously.
RC28-E from RemeGen is a VEGF/FGF dual-target fusion protein, which explores more comprehensive control of abnormal angiogenesis by simultaneously inhibiting VEGF and FGF-related signals.
IBI302 from Innovent Biologics adopts a design that combines VEGF and complement pathways, capturing VEGF family ligands through VEGFR1 and VEGFR2-related domains, while introducing complement inhibition-related functions, hoping to take into account pathological links such as neovascularization and inflammatory injury.
Tabirafusp-ted (KSI-501) from Kodiak Sciences combines IL-6 and VEGF. This product inhibits abnormal angiogenesis through VEGF-trap, while blocking IL-6-related inflammatory signals to improve the disease from two dimensions of vascular abnormality and inflammatory response. The product reached the primary endpoint in the Phase III DAYBREAK study announced in September 2026, with non-inferior visual improvement to Eylea, and is currently conducting a Phase III clinical study for DME.
MK-8748 deployed by Merck simultaneously inhibits VEGF and activates Tie2. The latter is a receptor tyrosine kinase expressed on the surface of endothelial cells and is an important factor for maintaining the stability of vascular endothelium. This design further enhances vascular stability and reduces abnormal leakage, and has now entered Phase II/III clinical research.
· Gene therapy: pursuing a paradigm revolution of "one administration, long-term benefit"
For patients with nAMD and DME, long-term repeated intravitreal injection is an unavoidable problem. The logic of gene therapy is to make retinal cells continuously express therapeutic proteins through a single intraocular administration, fundamentally solving the pain point of repeated injections.
A number of products have entered the clinical stage globally. Ixo-vec, acquired by Eli Lilly, is an AAV gene therapy product for nAMD, which enables retinal cells to continuously express anti-VEGF proteins through intraocular delivery, greatly reducing patients' dependence on conventional injections; in addition, Eli Lilly also obtained the gene therapy AAV-AIPL1 for the treatment of Leber congenital amaurosis type 4 (LCA4) through cooperation with MeiraGTx, with the goal of "restoring the vision of those children who were destined to be blind at birth".
Domestic enterprises are also catching up rapidly. EXG102-031 from Exegenesis Bio adopts a broader anti-angiogenesis design, which can continuously express therapeutic proteins covering multiple related pathways such as VEGF-A, VEGF-B, VEGF-C, VEGF-D, PlGF and Ang2 through AAV delivery, achieving more comprehensive vascular regulation than single VEGF inhibition; RRG001 from D-gene also adopts the AAV gene therapy strategy. The Phase I/IIa study data shows that the annual supplementary anti-VEGF injection rate in the high-dose group decreased by 95.83%, showing the potential to reduce the burden of repeated treatment.
Of course, the druggability of AAV gene therapy still faces more unknown challenges. Immunogenicity, long-term expression stability, safety and even commercialization are all thresholds that need to be crossed. But once verified successfully, it will become a disruptive treatment in the field of fundus diseases.
· Exploration of new mechanisms: jumping out of VEGF and returning to vascular homeostasis
Retinal fundus diseases are not only a problem of excessive angiogenesis. Impaired vascular barrier function, abnormal endothelial cell connections and local inflammation also participate in the occurrence and development of diseases. Therefore, jumping out of the inherent idea of VEGF inhibition and activating pathways related to vascular homeostasis has become another innovation path.
MK-3000 from Merck is a representative of this direction. By simulating the effect of the natural ligand Norrin, it activates the FZD4-related Wnt signaling pathway to promote the normal development and stability of retinal blood vessels. Its key Phase II/III study for DME has read out positive results.
In addition, long-acting delivery technology was once highly expected to extend the dosing interval through sustained-release preparations. But the R&D in this direction has not been all smooth sailing. Recently, DURAVYU (vorolanib intraocular sustained-release formulation) from EyePoint failed to reach the expected endpoints in the Phase III clinical trial, and the company's stock price plummeted by more than 80% in a single day, which also cast a shadow over the R&D prospect of long-acting ophthalmic delivery.
This also reminds us again that the R&D of fundus disease drugs is entering an all-round innovation stage. From the superposition and expansion of targets, to the breakthrough of delivery technology, and then to the innovation of treatment paradigms, players of different technical routes are competing on the same field. But whether the innovative mechanism can be transformed into clinical advantages ultimately depends on the efficacy and safety data.
Of course, it is undeniable that the 100-billion-dollar market space is large enough to accommodate multiple blockbuster products, and the wave of ophthalmic innovation