Post-food-delivery-war Era: Meituan, Alibaba and JD Are Competing in Other Fields
A series of industry updates in early November have outlined the competition trajectory of the post-food delivery war era.
Guo Qing, head of JD's local life services business, resigned for personal reasons. The official announcement simultaneously stated that the food delivery business has entered the 2.0 stage centered on "supply chain innovation", and the new management team will consist of talents with long-term deep experience in the supply chain sector.
"Family Banquet", Taobao Flash Purchase's high-end in-home catering project, launched gray testing in Beijing, covering 18 stores of 6 brands in the first phase, with the number of national partner brands expanded to 27 and the total number of stores exceeding 50.
Earlier at the end of October, Meituan completed the promotion of two post-80s vice presidents, who will take charge of the pharmaceutical health and commercial value-added tracks respectively.
The three adjustments seem to have different causes and are unrelated to each other, but in fact they are all pre-layouts for a new round of industry competition. The core of industry competition is entering a deep water zone where short-term funds cannot quickly leverage advantages.
I. After the Ceasefire, Platforms Start Recalculating the Profit of Every Single Order
From Q2 2025 to Q1 2026, the three platforms launched high-intensity competition around food delivery, with the average daily orders once reaching 250 million units, and the market landscape has also undergone significant changes.
According to UBS's estimate in March 2026, Meituan has about 62 million average daily orders, Taobao Flash Purchase about 52 million, and JD about 8 million, corresponding to market shares of 53%, 41% and 6% respectively, totaling about 122 million orders across the three platforms. In the statistics of Goldman Sachs in June 2026, the figures given are 80 million, 66 million and 16 million orders respectively, corresponding to market shares of about 49%, 41% and 10%.
The statistical timing and calibers of different institutions are not completely consistent, but the general direction of the market pattern is basically clear: Meituan still leads, Taobao Flash Purchase has become an important competitor, and JD has retreated after rapid expansion.
The cost paid is also extremely high. According to the calculation of HSBC's research report, from Q2 2025 to Q1 2026, the three platforms added a total of about 156.8 billion yuan in marketing expenses, and the total loss on food delivery and related instant retail business in the same period was about 173 billion yuan.
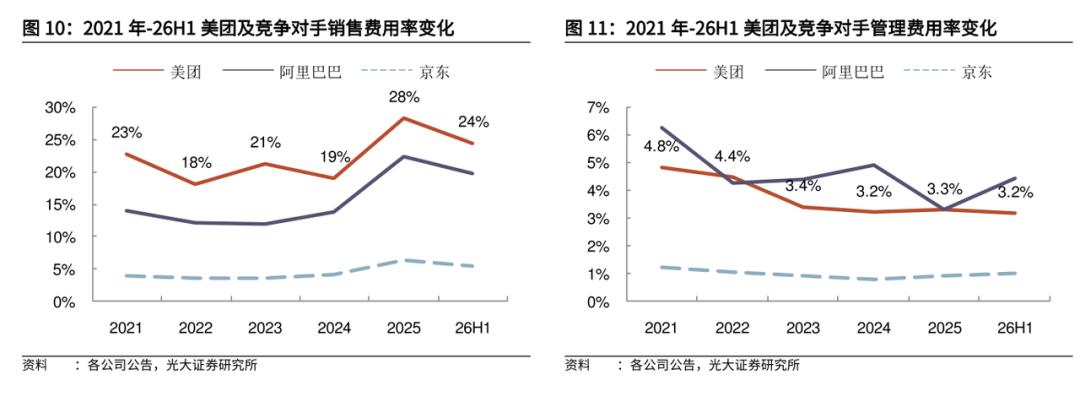
"The past year was a period of extremely crazy and unreasonable competition that wasted almost a whole year of the entire industry. Now we are finally gradually getting back on the right track." Wang Xing made a frank statement at the shareholders' meeting.
Tightening regulation is the direct reason for the receding of subsidies and the gradual return to the right track.
In June 2026, the State Administration for Market Regulation released the "Ten Norms for Subsidy Behaviors of Food Delivery Platforms (Draft for Comments)", putting forward normative requirements for behaviors such as long-term large-amount subsidies, forcing merchants to bear the cost of subsidies, and selling below cost.
Sustained money-burning for orders has increasingly become an unsustainable long-term strategy. According to Goldman Sachs' tracking data, since last September, although the daily average order volume of the three platforms has fluctuated, no fundamental changes have taken place in their relative market shares.
The more fundamental reason is that subsidies can buy orders, but cannot enable platforms to fulfill each order at a more cost-effective cost.
Food delivery is a business that relies on regional order density. When orders are concentrated in the same business district, riders can complete more deliveries within a limited distance, making it easier to reduce the per-order fulfillment cost. On the contrary, even if a platform has a large number of users, if orders are scattered and the delivery network is not dense enough, the cost is still difficult to be averaged down.
According to JPMorgan Chase's calculation, the lower limit of Meituan Food Delivery's comprehensive per-order fulfillment cost is about 6.3-6.5 yuan, while the cost of similar competitors in the industry is generally 0.3-0.5 yuan higher. The gap is mainly related to order density and delivery efficiency. JD Food Delivery has a higher proportion of full-time riders and heavier compliance costs, so the per-order rider cost will be higher.
Although various calculation calibers are different, they all reflect one problem: order scale does not equal fulfillment efficiency.
Platforms can quickly acquire users by relying on subsidies, but they need a much longer time to build a merchant network, rider density and stable consumption habits. Subsidies can shorten the time to enter the market, but cannot replace the accumulation of local fulfillment networks.
When the marginal revenue of subsidies declines, what solutions will the platforms come up with?
II. Three Answers: Deepen Penetration, Expand Boundaries, and Increase Asset Weight
Facing the same industry changes, the three companies are in different situations and have made different choices.
Food delivery is Meituan's core hinterland. With the receding of subsidies, Meituan's profits have been significantly restored.
In Q3 2025, Meituan's core local business recorded an operating loss of 14.071 billion yuan, and this business segment that had long supported profit growth faced strong pressure. By Q2 2026, this segment returned to an operating profit of 5.668 billion yuan. It should be noted that this set of data reflects the overall performance of the core local business, not the separate profit and loss changes of the food delivery business.
Focusing on the food delivery business, according to estimates by some institutions, Meituan Food Delivery's per-order unit economics (UE) improved from about -1 yuan in Q1 2026 to about +0.16 yuan in Q2 2026.
Meituan chooses to deepen its penetration, relying on its existing local fulfillment network to expand more high-value categories and improve the utilization efficiency of the existing network.
In the catering sector, Meituan has reduced indiscriminate competition for low-price orders and pays more attention to the input-output ratio of orders themselves. At the 2026 Food Delivery Industry Conference held in October, Meituan disclosed that among the food delivery orders of catering merchants in 2026, the proportion of orders below 15 yuan halved year on year, and the average actual payment per order rebounded simultaneously.
In the non-catering sector, Xiaoshang Supermarket continues to expand its front warehouse network, Lightning Warehouses expand commodity supply through socialized cooperation, and Meituan also announced that it will invest 30 billion yuan in resources in the next three years to build a "30-minute commodity circle" together with partners.
In addition, the two post-80s vice presidents mentioned earlier are respectively in charge of the high-threshold commodity demand in instant retail and the commercial monetization of the platform's stock traffic, which is also an exploration for high-value business growth points.
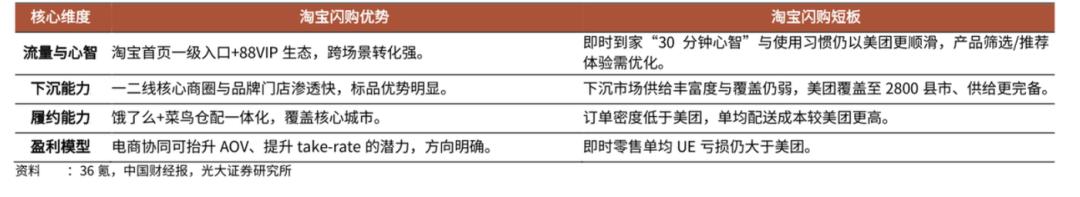
Alibaba chooses to push the boundary of instant retail outward to give full play to its advantages in commodities and product categories.
Taobao Flash Purchase has been listed as the core strategic pillar of Alibaba's e-commerce. According to the plan previously announced by Jiang Fan, Alibaba hopes to turn positive the monthly UE of instant retail in FY2027, and push the scale of instant retail to exceed 1 trillion yuan in FY2028.
The specific implementation is to expand instant retail to more consumption scenarios: the catering business covers more price ranges through different brands and products, such as the Family Banquet mentioned earlier. The non-catering business uses Taobao's commodity resources to connect more categories such as daily general merchandise to instant delivery services.
In September 2026, the head of Taobao Flash Purchase's non-catering business was adjusted from Hu Qiugen to Wang Tingxiang. Wang Tingxiang has rich experience in businesses such as Taoxianda, Taocai Cai and Taobao Apparel, and is more familiar with Taobao's commodity ecosystem and brand operation.
The massive brand commodities and merchant resources on Taobao's main site originally serve the fulfillment model of express delivery e-commerce. Transforming them into a supply network that can support instant retail involves a series of complex issues such as inventory synchronization, brand owners' willingness to prepare goods separately, and price system balance. This requires a person who understands both Taobao's e-commerce ecosystem and local fulfillment logic to promote the transformation.
JD Food Delivery is the one most obviously restricted by order density among the three platforms. If it continues to compete for orders along the matching model, JD will need to pay very high costs, and it will be difficult to establish advantages in the short term.
Therefore, JD chooses to bypass this path. Since it cannot compete by matching others' supply, it will build its own supply, which is the "supply chain innovation" mentioned earlier.
Increasing asset weight has always been JD's consistent strategy. It is acceptable not to make money by selling meals at the front end, and making profits through the supply chain is also a viable path.
Qixian Little Kitchen is an important experiment on this new path. By intervening in catering production and standardized management, JD hopes to extend its supply chain capabilities to the catering supply side. Details will be described in the following part.
So far, the three platforms have made relatively differentiated choices based on their own advantages. Meituan relies on its fulfillment network to deepen instant retail, Alibaba leverages its commodity ecosystem to expand consumption scenarios, and JD finds a new competitive fulcrum from the supply chain and production end.
III. Where Is the Next Round of Competition?
Although the three platforms have different paths, they are all extending to the supply side, trying to intervene in supply in different ways, and evolving from matching transactions to organizing production, managing inventory and providing fulfillment services.
There are two types of products on the shelves of instant retail: one is freshly made catering with no inventory, and each order requires on-site organization of production. The other is standard products with inventory, where the competition focuses on where the warehouse is built, how much stock is prepared, and who supplies the goods. The former front line is in the catering kitchen, and the latter front line is in the warehouse network.
Let's first look at the catering sector.
Taobao Flash Purchase's Jiwa Canteen is the lightest model among them: the platform outputs brands, menu structure and traffic, while partner merchants bear the costs of rent, kitchen, ingredients and personnel, targeting the price range of affordable simple meals. The advantage of the light asset model is fast expansion and small platform investment, but product quality control and operation quality are highly dependent on partner merchants.
Alibaba has deployed Family Banquet at the other end of the price spectrum, targeting family gatherings and business banquets, redesigning everything from dish selection, menu design to packaging and delivery, trying to bring high-end catering into the in-home consumption scenario.
Meituan's Raccoon Canteen is between the two models, which is closer to a shared kitchen: partners are responsible for site selection, rent, decoration and equipment, while the platform provides orders, investment promotion and operation management.
Raccoon Canteen plans to lay out about 1,200 stores in the next three years, and launch about 200 stores first in 2026. Whether this model can succeed depends on site utilization rate and the operation quality of settled merchants.
JD's Qixian Little Kitchen intervenes the most deeply, with unified procurement, unified kitchen management and unified standards, directly extending supply chain capabilities to the catering production end. The platform bears the costs of rent, ingredient procurement and kitchen manpower, and realizes standardized production through automated equipment and unified management, while partners mainly provide recipes and participate in profit sharing.
Then let's look at the warehouse network sector.
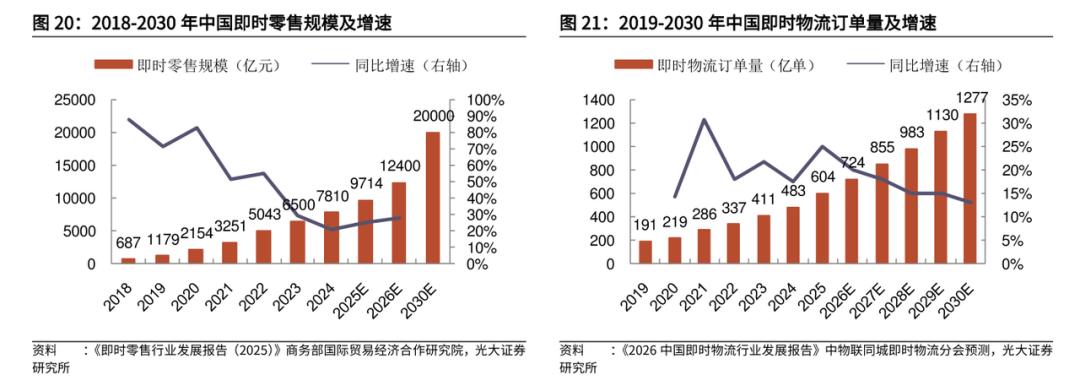
Wang Puzhong, CEO of Meituan Core Local Business, once stated that instant retail has crossed the most difficult stages of demand cultivation and network deployment, and the next stop is to stride from the "store-warehouse-delivery era" into the "commodity era".
In other words, Meituan's warehouse network is already dense enough, and the current focus should be on converting fulfillment density into commodity density, and calculating the operating efficiency of each single warehouse.
As mentioned earlier, Xiaoshang Supermarket has more than 2,000 front warehouses, covering 100 cities. At the same time, the proportion of private label products and customized small-specification products in the warehouses continues to increase, so as to optimize the product structure and improve the gross profit of each warehouse.
Xiaoshang Supermarket is also promoting the integration of stores and warehouses, adopting the collaborative model of "large central store + city-wide front warehouse". The front area provides retail experience, and the back area undertakes online sorting, so as to supplement the in-depth supply of fresh food and daily general merchandise.
Lightning Warehouses undertake the role of expanding socialized commodity supply.
Wang Puzhong disclosed at the Instant Retail Conference that the target set in 2024 of building 100,000 Lightning Warehouses and achieving 200 billion yuan GMV by 2027 is expected to be completed ahead of schedule.
As the warehouse network scale gradually takes shape, Meituan Flash Purchase launched the "Commodity NEXT" plan, investing 30 billion yuan in the next three years to support partners in product selection, goods distribution, marketing and product development, so as to further enrich the supply of instant retail.
Alibaba configures its warehouse network according to different product categories and consumption demands, to convert Taobao's commodity resources into instant retail supply.
Alibaba is forming an instant retail system with multiple warehouse network forms running in parallel. The Freshippo system is dominated by self-operated front warehouses, Tmall Supermarket extends the traditional e-commerce fulfillment network to instant retail through urban warehouses, and Taobao Convenience Stores introduces third-party merchants through brand authorization to build community flash purchase warehouses together.
Freshippo's front warehouses are extended from the Freshippo Hema large store system, which exceeded 500 in June this year, with a year-end target of more than 1,000. In September 2026, Taoxianda was restarted, positioned as an affordable supermarket under Freshippo, providing 24-hour delivery service, with the basic delivery fee reduced to 3 yuan and free delivery for orders over 29 yuan. According to relevant reports, Taoxianda entered 7 cities in about 60 days and laid out more than 33 warehouses.
The two are complementary in product positioning: one focuses on mid-to-high-end self-operated products, and the other focuses on affordable standard products.
Tmall Supermarket originally mainly shipped goods from central warehouses, providing next-day delivery and half-day delivery services. Now Alibaba is promoting the construction of urban warehouses and front warehouses dedicated to instant retail, forming a "large warehouse + small warehouse" warehouse network structure, and has launched 4-hour delivery services in some cities.
Taobao Convenience Stores adopts the brand authorization model to let merchants open warehouses, with goods supplied by factories in 1688 industrial belts. It has developed to 800 stores about 9 months after launch, and according to Tech Planet