Elon Musk blasted Nvidia's board of directors: Are people who sell fast food and soda deciding the fate of a trillion-dollar AI empire?
A list of NVIDIA board members has completely ignited Silicon Valley's fury.
Shortly after Jensen Huang suddenly left NVIDIA, Elon Musk openly launched an attack on the NVIDIA board of directors.
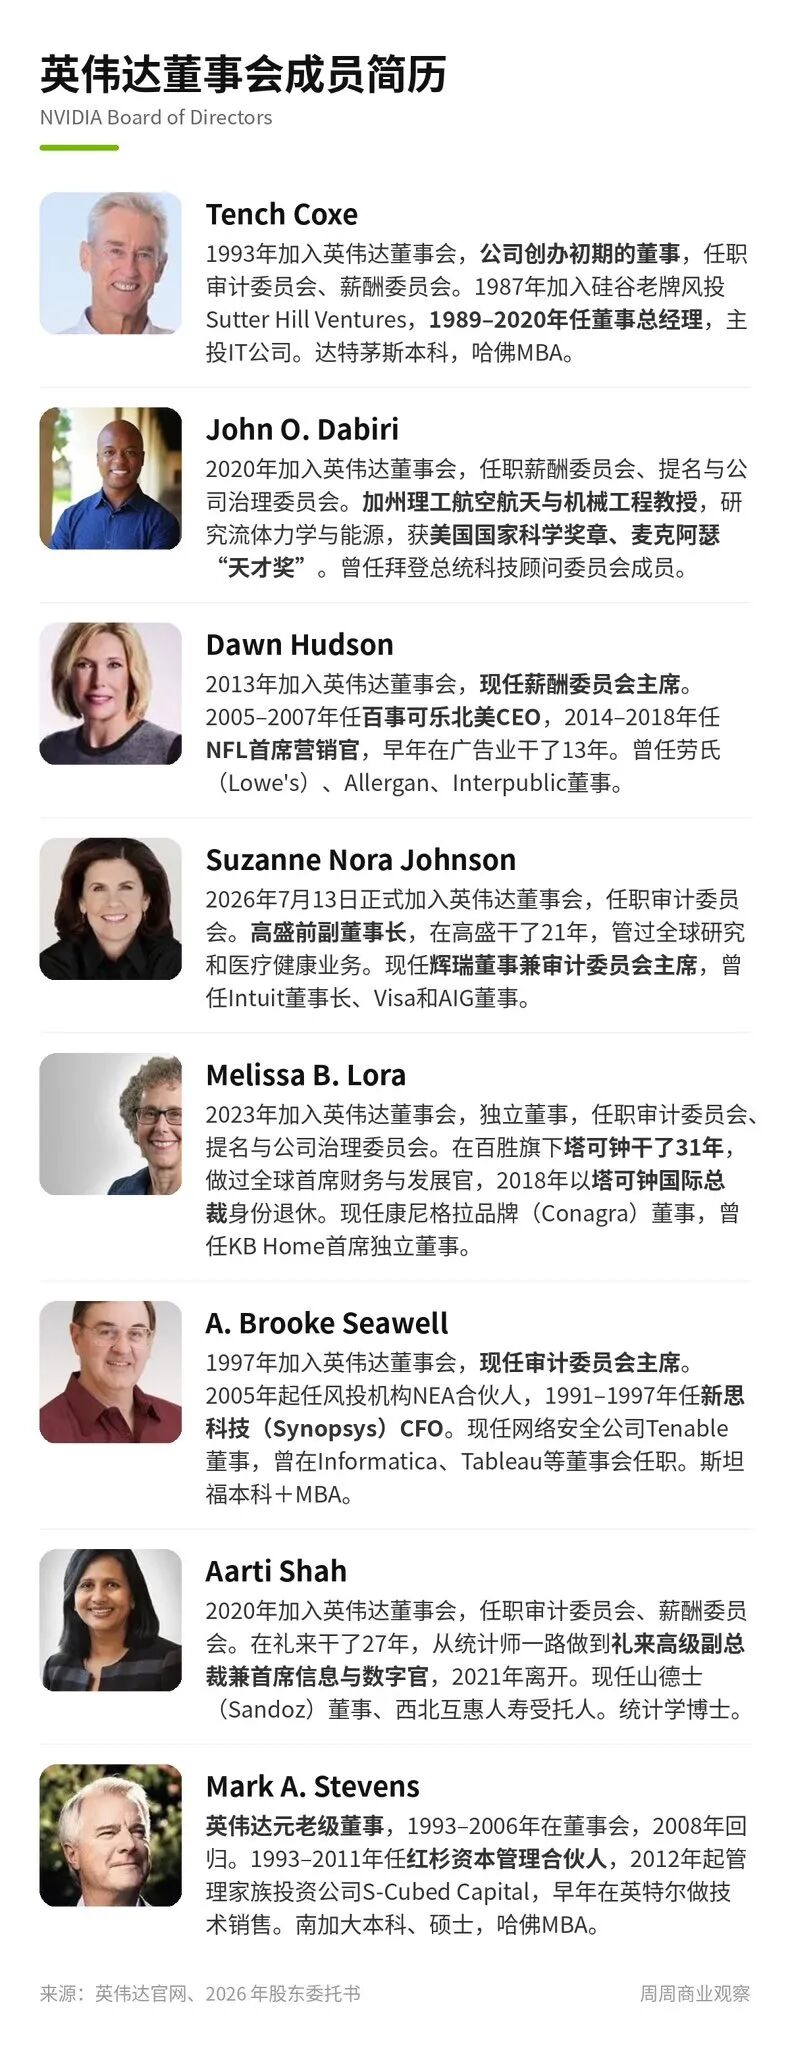
He reposted a post about the composition of NVIDIA's board members on the social platform X, leaving a highly ironic comment:
"This is the board that makes decisions for what used to be the most valuable company on Earth!?"
He also attached a facepalm emoji right after the comment.
The most thought-provoking detail is that Musk used the word "used to be".
This does not mean he has asserted that NVIDIA is on the decline, but it fully demonstrates his dissatisfaction with this leadership change.
More importantly, Musk is not just venting his emotions.
He has also publicly supported the petition demanding Jensen Huang return to NVIDIA, and warned that once NVIDIA loses Jensen Huang, it may even lose some key supply chain partnerships.
At this point, a question worthy of serious consideration by all NVIDIA shareholders arises:
Why would a company founded by a tech genius that dominates the global AI computing power market end up having its founder's fate decided by a group of directors from the fast food, beverage, finance, legal and venture capital sectors?
I.
The Board List Exposed:
Taco Sellers, Coke Sellers, Wall Street Bankers,
All Sit in NVIDIA's Highest Authority Body
A board member list circulating online has caught countless investors by surprise.
First up is Melissa B. Lora.
She joined NVIDIA's board in 2023, spending 31 years of her career at Taco Bell, where she served as President of International Operations and Global Chief Financial and Development Officer.
Taco Bell is a well-known American fast food brand that mainly sells Mexican-style wraps, tacos and other food products.
The second member is Dawn Hudson.
She once served as CEO of PepsiCo North America and Chief Marketing Officer of the National Football League (NFL), and joined NVIDIA's board in 2013.
The third member is Suzanne Nora Johnson.
She worked at Goldman Sachs for 21 years as Vice Chairman, and served as a director at large enterprises including Pfizer. In July 2026, she officially joined NVIDIA's board of directors.
There are also venture capitalists, corporate financial executives and other cross-industry professional managers.
As a result, a very sharp question has emerged online:
People who sell cola can supervise a chip company, but do they really have the ability to judge who is best suited to lead the global AI computing power revolution?
However, after checking NVIDIA's official documents, Tradesmax found that this circulating image is incomplete.
It only lists 8 directors, omitting two other important figures.
Among them, Harvey C. Jones, who has just taken office as Chairman of the Board, once served as CEO and Executive Chairman of Synopsys, the giant in chip design software. He has a computer science background and co-founded the processor IP company Tensilica.
Mark A. Stevens once worked at Intel, holding a bachelor's degree in electronic engineering and a master's degree in computer engineering; John O. Dabiri is a professor of engineering at the California Institute of Technology; Aarti Shah holds a doctorate in applied statistics, with work experience in information technology and data analysis.
Therefore, strictly speaking, NVIDIA's board of directors is not completely ignorant of technology, and we cannot directly conclude that a person lacks corporate governance ability just because he or she once worked in the fast food or beverage industry.
But another problem still exists:
Being proficient in finance, compliance and the market does not mean that one can fully understand an AI computing platform built by GPU architecture, CUDA software ecosystem, advanced packaging and global supply chain.
The board of directors does not need to design chips in person, but it must be able to judge which strategic decisions may affect the company's competitive position in the next five or even ten years.
This is the real core of the controversy.
II.
The Empire Jensen Huang Spent 33 Years Building: What Exactly Has Been Lost?
In 1993, Jensen Huang founded NVIDIA together with two co-founders.
At that time, no one could have imagined that this company would eventually become one of the most important suppliers of global artificial intelligence infrastructure.
The most noteworthy part of NVIDIA is not just that it designed GPUs with leading performance.
It is that Jensen Huang, in every technological turning point, bet on long-term directions that competitors did not pay sufficient attention to.
From graphics processing, to general-purpose parallel computing, to the CUDA ecosystem, deep learning, AI training and inference, NVIDIA has spent decades building the competitive moat it has today.
The most critical part of this is CUDA.
Chip performance can be gradually caught up by competitors, and product prices can be driven down, but the development tools, software libraries, engineer experience and application ecosystem built around CUDA are not so easy to replace.
After that, Jensen Huang extended NVIDIA's competitive scope from a single GPU to the entire data center.
Nowadays, NVIDIA sells not only chips, but also network interconnection, system architecture, rack-level computing platforms, and software supporting AI infrastructure.
This means that Jensen Huang's core value has long gone beyond the management responsibilities of an ordinary CEO.
He not only determines the company's business direction, but also plays a key role in technological R&D, industrial chain resource allocation, customer relations and market expectations.
A company's CEO can be replaced, but a technical decision-making system formed over 33 consecutive years cannot be handed over in just a few days.
III.
What Musk Is Really Worried About Is Not NVIDIA Changing Its CEO, But That The Supply Chain May Lose Jensen Huang
Compared with the external debates over the background of board members, Musk's other statement on November 14 is of more analytical value to investors.
According to a Reuters report, Musk believes that Jensen Huang has managed NVIDIA's supply chain excellently, and many important partnerships rely on personal trust established between both sides, not just formal contracts.
He is worried that without Jensen Huang, some key partnerships may be lost.
This statement points to a frequently underestimated competitive moat in the AI industry:
Supply chain control capability.
NVIDIA's competitive advantage depends not only on how advanced a GPU it can design, but also on whether it can lock in key production resources in advance.
Advanced process nodes, HBM high-bandwidth memory, advanced packaging, network components, and supporting production capacity required for complete machine systems may all become bottlenecks in the expansion of AI infrastructure.
In periods of tight supply, whoever can judge demand in advance, lock in production capacity, and coordinate suppliers and customers is more likely to translate technological advantages into actual revenue.
The long-term industrial relationships Jensen Huang has cultivated may be exactly one of these assets that are difficult to quantify.
Of course, Musk's concerns do not equal actual supply chain losses that have already occurred. Whether there are significant lost orders, partnership adjustments or delivery delays still needs to be verified by subsequent facts.
But this reveals NVIDIA's most sensitive risk at present:
It is not that competitors suddenly design more advanced chips than NVIDIA, but that internal power changes at NVIDIA may first shake the confidence of external partners in its execution capability.
IV.
Why Is It Said That NVIDIA's Board of Directors Is Facing An Extremely Difficult Choice?
In this turmoil, there is another fact that cannot be ignored.
NVIDIA previously announced the launch of an independent investigation, involving the foreign intelligence contact risk raised in external reports.
The company made it clear in its statement on November 8 that there was no reason to believe at the time that national security or NVIDIA's trade secrets had been compromised, while deeming it necessary to carry out the investigation.
Subsequently, the company hired independent legal counsel to advance related work.
This means that the board of directors is not just dealing with an ordinary personnel dispute, but a complex issue that may involve compliance, national security, regulation and shareholder interests.
From the board's perspective, even a founder who has created huge shareholder value cannot be exempted from necessary supervision.
But from investors' perspective, another issue is equally important:
Without fully disclosing the investigation conclusions and the course of management changes to the market, how much impact could the loss of a founder who has long mastered strategy, technology and supply chain relationships have on the company?
There are two types of risks here.
One is that the board of directors fails to fully perform its supervisory duties, eventually causing the company to suffer more serious legal and regulatory losses.
The other is that when handling the crisis, the board of directors does not fully assess the strategic and operational losses brought by the departure of key personnel.
Mature corporate governance does not mean unconditionally protecting founders, nor does it mean proving that the board of directors can replace the founder at any time. Instead, it must make a judgment between compliance risks and long-term corporate value that can be explained to shareholders.
It is worth noting that some members of NVIDIA's current board of directors joined the company as early as 1993. They are not external forces that suddenly entered the company.
This makes the issue even more complicated: how exactly do these directors who have long participated in NVIDIA's development weigh the costs and benefits of this decision?
What the market needs is more sufficient information, not just a carefully worded management change announcement.
V.
From An Investment Perspective, The Most Dangerous Thing May Not Be Performance, But That The Valuation Logic Has Changed
Let's look at a set of truly important financial data.
According to NVIDIA's Q2 FY2027 earnings report released on August 26, 2026:
Total quarterly revenue reached 96.2 billion US dollars, a year-on-year increase of 106%;
Data center business revenue reached 89 billion US dollars, a year-on-year increase of 117%;
The data center business has contributed about 92.5% of total revenue;
Non-GAAP gross margin reached 75%.
This is an enterprise that still has extremely high growth rate and strong profitability.
Therefore, Jensen Huang's departure does not mean that NVIDIA's customer demand will suddenly disappear the next day, nor does it mean that the CUDA ecosystem will collapse accordingly.
What is really worth worrying about is another kind of change:
The market was willing to pay a high valuation for NVIDIA in the past, and part of the reason was that investors believed Jensen Huang had the ability to continuously extend the company's technological leading edge.
With Jensen Huang leaving, this part of confidence may need to be repriced.
For investors, the value of an enterprise depends not only on how much profit it can create in the future, but also on how long these profits can last, and how much confidence the market has in the probability of its realization.
If the market begins to doubt whether NVIDIA can maintain its technological lead, customer partnerships and supply chain advantages, even if short-term earnings performance remains strong, the valuation multiple may come under pressure.
This is why, the company's fundamentals have not deteriorated immediately, but its stock price may plummet sharply first.
VI.
Next, NVIDIA Investors Should Keep A Close Eye On Three Signals
The first signal: In the November 17 earnings report, can the management maintain the original growth guidance?
NVIDIA previously gave Q3 FY2027 revenue guidance of 108 billion US dollars, with a fluctuation of plus or minus 2%, and non-GAAP gross margin guidance of about 74%.
This earnings report will become the most important market test after the management change.
In addition to revenue, gross margin and future quarterly guidance, investors especially need to pay attention to how the management explains the supply chain, customer demand, product delivery and capital expenditure.
The second signal: Is the Vera Rubin platform and subsequent product roadmap advancing as planned?
Advanced AI chips cannot generate revenue just after the design is completed.
From GPU design to system integration, software adaptation, and then to supply chain delivery, every step involves complex cross-departmental coordination.
If key products are still mass-produced and delivered as planned, it shows that NVIDIA's organizational system has a certain degree of resilience.
Tradesmax believes: on the contrary, if major product delays, R&D brain drain or key customer partnership changes occur in the future, the market will need to reassess the company's long-term competitive advantages.
The third signal: Is the new CEO a financial manager, or a leader who can continue the technical strategy?
Interim CEO Colette Kress has deep financial and technology industry management experience.
But leading NVIDIA in the long run requires more than just financial management capabilities.
The new CEO must be able to understand the development trends of GPUs, network interconnection, software ecosystems and AI infrastructure, and make forward-looking strategic decisions when there is great uncertainty in technical routes.
At the same time, the company must also retain the trust of its core technical team and customers.
This may be more important than choosing a professional manager recognized by Wall Street.
VII.
Will NVIDIA Repeat Apple's History From Years Ago?
Many investors compare this turmoil to Steve Jobs' departure from Apple back then.
In 1985, Steve Jobs left Apple after internal power struggles at the company. After that, Apple experienced a long period of strategic difficulties, and did not gradually enter a new stage of development until Steve Jobs returned in 1997.
The historical backgrounds faced by the two companies are different, and we cannot simply assert that NVIDIA is doomed to repeat Apple's fate.
But this case reminds investors:
When a company has long relied on a founder with unique strategic vision, the loss of this leader may cause losses that go beyond what the financial statements can immediately reflect.
Of course, history also shows that excellent enterprises can reduce their dependence on a single individual through institutionalized R&D systems, professional management teams and organizational inheritance.
What will ultimately determine NVIDIA's future is not whether Jensen Huang still sits in the CEO's office, but whether the technical and organizational advantages he built over the past 33 years can continue to operate effectively.
Final Note
The reason why Musk's public questioning of NVIDIA's board of directors has resonated widely this time is not just because executives from the fast food, beverage and finance industries appear on the list.
What is truly worrying is:
When the global AI industry is going through a technology and capital investment cycle that may last for more than ten years, NVIDIA has suddenly lost the person who has long set the strategic direction, coordinated the supply chain and led the technical team.
The board of directors certainly has the right to supervise the CEO.
But power itself cannot automatically prove that the decision is correct.
The board of directors needs to prove to shareholders that it is not only capable of managing risks, but also capable of protecting the corporate value that Jensen Huang has built over 33 years.
For NVIDIA, the real test is not whether it can find the next CEO.
It is whether the next CEO can inherit the technical judgment, industrial leadership and global supply chain influence left by Jensen Huang.
Will the word "used to be" that Musk used end up being just irony in a fit of anger, or a warning for NVIDIA's future?