CoreWeave: With a stellar outstanding performance report, defying the wildly irrational volatile stock price trend, can NVIDIA's widely reputed golden boy really hold its head high and achieve real success?
AI new cloud unicorn Coreweave (CRWV.US) released its Q3 financial report after market hours on November 10 Eastern Time. Judging solely from this quarter's performance, the results are quite solid: both revenue and backlog have accelerated their growth and outperformed expectations, all profit margins continued to improve, and the adjusted operating margin reached double digits one quarter ahead of schedule as stated by the company, while the full-year guidance was raised across the board. The details are as follows:
Revenue: QoQ increase of 1.1 billion USD, growth rate further accelerates
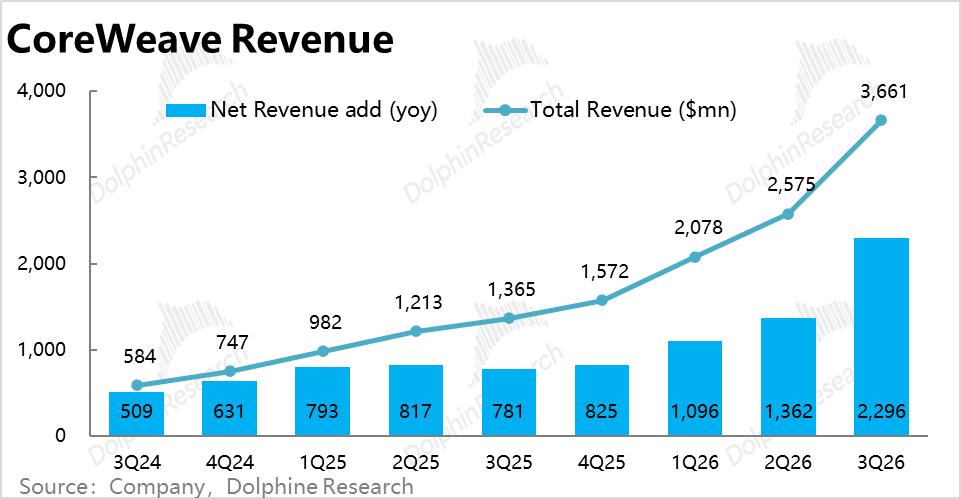
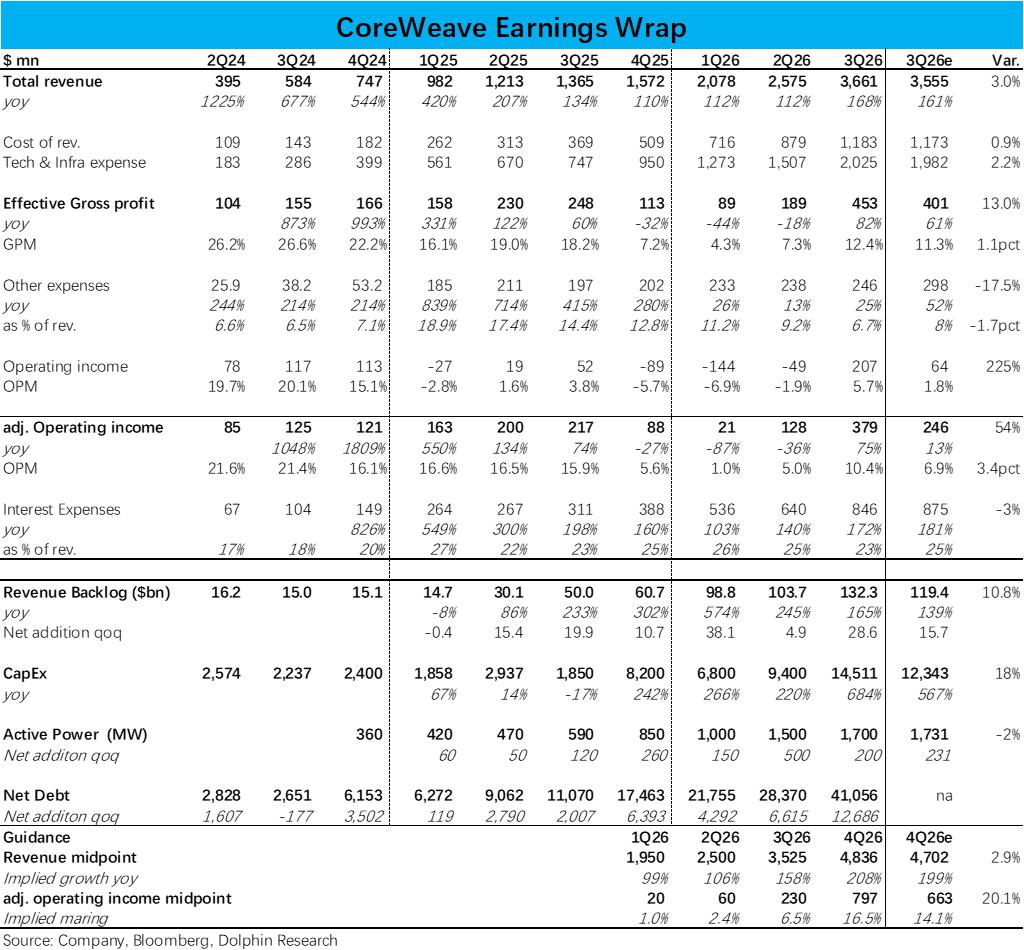
3Q26 revenue reached 3.66 billion USD, with a net sequential increase of about 1.09 billion USD for the single quarter, more than double that of the previous quarter. The revenue was about 3% higher than the consensus expectation, and also exceeded the upper end of the previous guidance of 3.6 billion USD, representing impressive growth.
The company stated that the growth came from favorable pricing and strong demand. It was confirmed on the earnings call: the prices of all computing power models rose by about 25% in July, followed by an additional roughly 10% increase later in the quarter, and prices continued to rise in 4Q, with the increase outpacing the rise in costs; the prices of the previous-generation "old chips" (Ampere, Hopper, etc.) also rose by 30%~50% QoQ this quarter, higher than the original contract price.
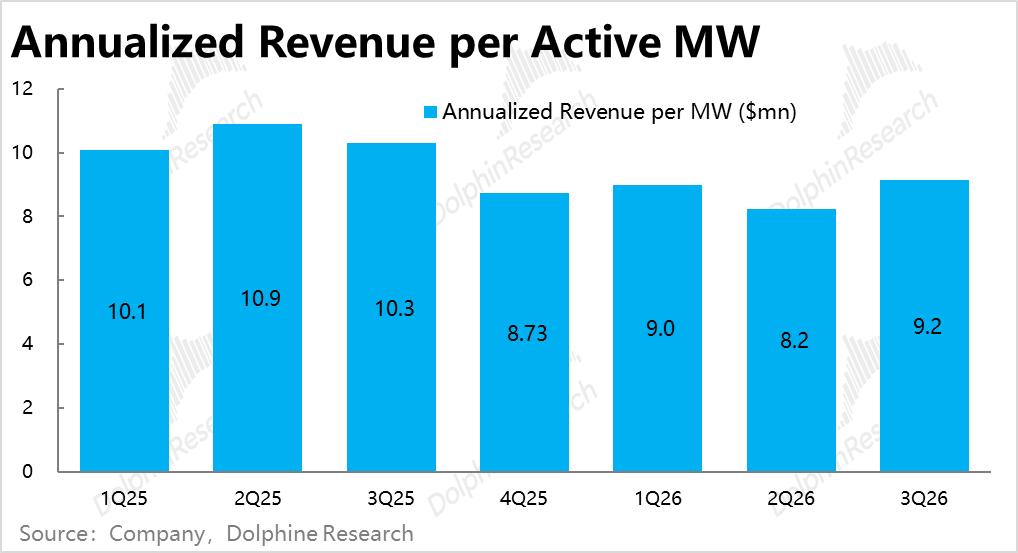
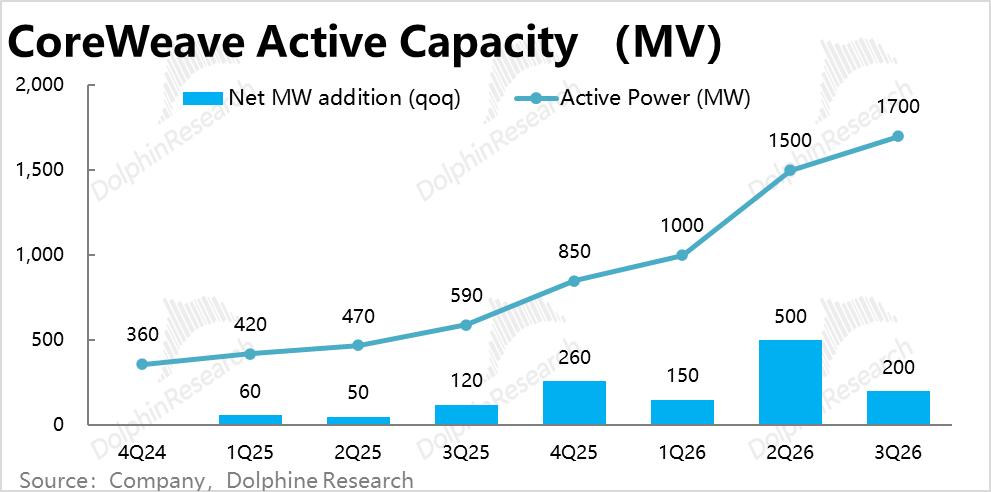
In terms of volume, only about 200MW of active power was added this quarter (compared to about 500MW in the previous quarter), which is not a fast pace. Therefore, the revenue that exceeded expectations this quarter should be more attributed to the large amount of computing power added at the end of the previous quarter that started generating revenue this quarter.
Roughly calculated based on average active power, the annualized revenue per MW this quarter is about 9.15 million USD, which is a significant increase from about 8.24 million USD in the previous quarter, verifying the rise in leasing pricing from the financial statement side.
To sum up in one sentence, looking back, the demand for computing power is indeed strong and supply cannot meet demand.
Backlog: Nearly 29 billion USD added in one quarter, mainly driven by long-term orders
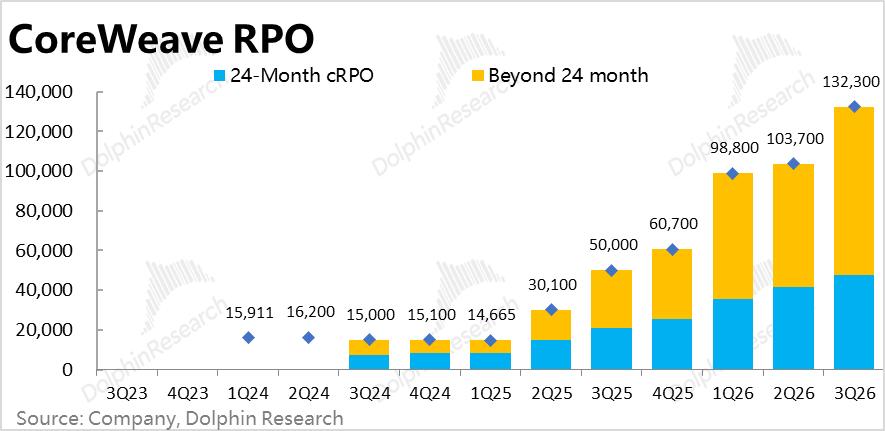
RPO at the end of the quarter stood at 132.3 billion USD, up by about 28.6 billion USD QoQ, marking the second highest single-quarter increment in history (second only to 1Q26), and about 11% higher than the consensus expectation; not only the current quarter's revenue, but also the demand for new orders is equally strong.
The company stated that new orders came from both existing and new customers, and the customer base is more diversified: more than half of the new customers added this year are from industries outside AI labs and the technology sector.
In terms of term structure, the proportion of long-term orders with a term of more than 24 months increased by 4 percentage points this quarter, while the net sequential increase of short-term orders was roughly equivalent to that of the previous quarter. The strong order growth this quarter is mainly driven by long-term orders with a term of more than 2 years.
Computing power launch and Capex: Launch meets expectations, Capex is spent in advance and exceeds guidance
Active power at the end of this quarter exceeded 1.7GW, roughly in line with the consensus expectation (about 1731MW). More than 200MW was added in the single quarter, a noticeable slowdown compared to the new increment in the previous quarter. Meanwhile, the company maintained its target of active power exceeding 1.85GW by the end of the year, which means only about 150MW will be added in 4Q, and the year-end scale will be lower than the consensus expectation of about 1.91GW.
Therefore, despite the strong revenue this quarter, the pace of computing power construction is not fast (this quarter's revenue is more driven by the large amount of computing power launched in the previous quarter).
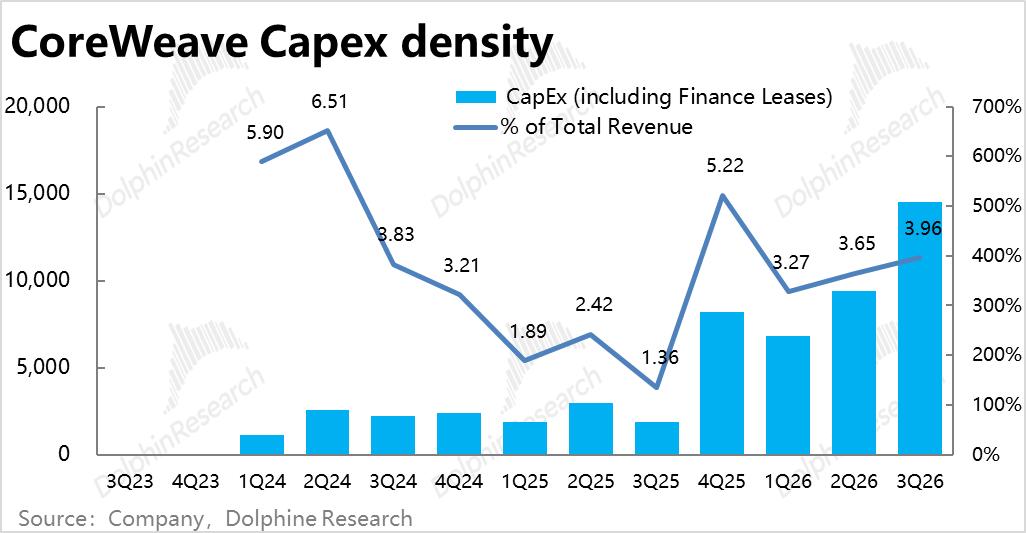
However, this quarter's Capex (including finance leases, excluding changes in construction in progress) reached as high as 14.5 billion USD, significantly higher than market expectations and the upper end of the guidance of 13.5 billion USD; the multiple of Capex relative to revenue also rose to nearly 4x. The pressure of investment required to support revenue growth is also becoming increasingly obvious.
Regarding the small amount of new computing power added while Capex surged, the CFO explained that part of the 4Q investment was brought forward to 3Q. However, Dolphin Analyst believes that the unit construction cost of computing power should also have risen (hardware price increase), and rough calculation shows that the cost this year may have increased by about 1/5~1/4 compared with 2025.
Profit margin: Adjusted operating margin is about 10%, reaching double digits one quarter ahead of schedule
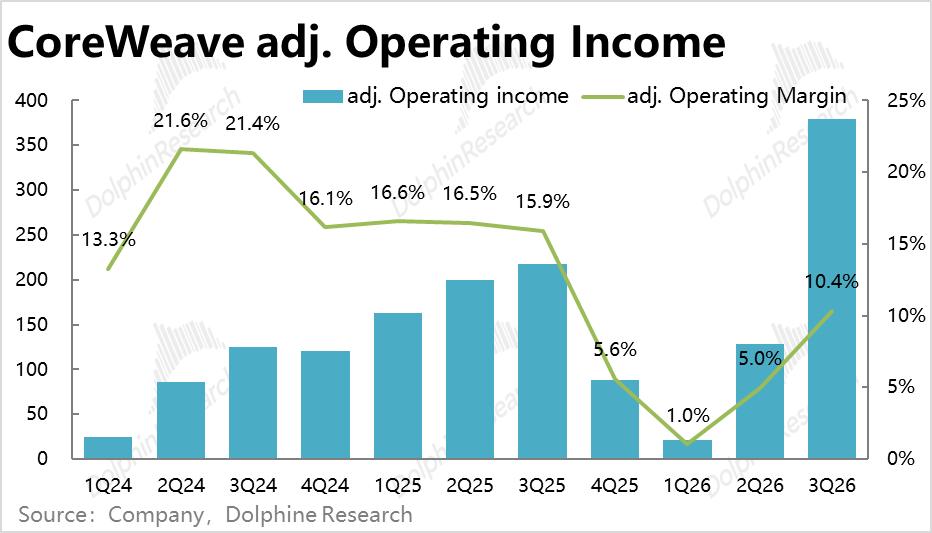
The adjusted operating profit this quarter was 379 million USD, with a profit margin of 10.4%, significantly higher than the consensus expectation of 6.9%, achieving the company's previously expected target of double-digit profit margin one quarter ahead of schedule.
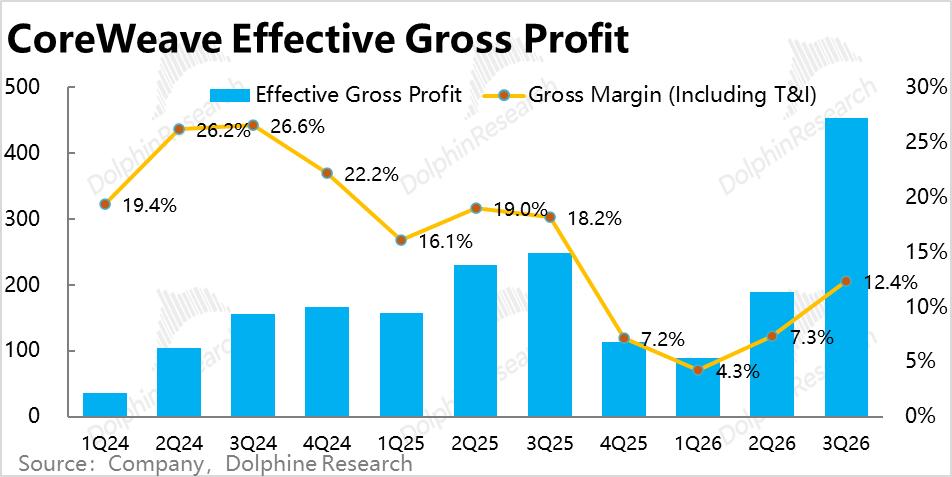
Breaking it down, the "real gross margin" after deducting operating costs and infrastructure R&D costs (T&I) is about 12.4%, compared to about 7.3% in the previous quarter, but still lower than the roughly 18% a year ago. The improvement mainly comes from the decline in the proportion of depreciation in revenue in T&I, from 54.1% to 51.6%;
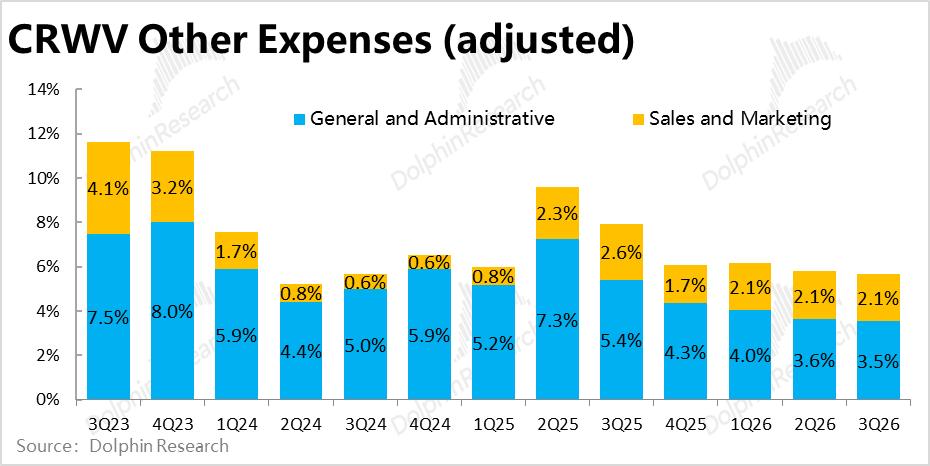
In addition, the operating cost ratio, which mainly includes energy, rent and labor, also decreased by about 1.8 percentage points QoQ. As for the sales and administrative expense ratio, it has always been low, and it continued to be diluted as revenue grew this quarter.
Combined with the management's remarks, Dolphin Analyst believes that the profit margin exceeding expectations and continuous improvement mainly have two reasons: the rise in leasing prices (the main factor) and the natural scale effect after revenue increases.
The CFO clearly stated that allocating available capacity to higher-margin short-term contracts "contributed significantly" to this quarter's performance. At present, the annualized revenue of short-term contracts can exceed 40 million USD/MW, and the price of new 4~5 year long-term contracts has also risen to 20~25 million USD/MW; short-term contracts can pay back the cost in 6~18 months, and long-term contracts take about 1~2 years to recover the hardware Capex.
Interest and financing: Interest is lower than guidance, but liabilities increased by about 12 billion USD in one quarter
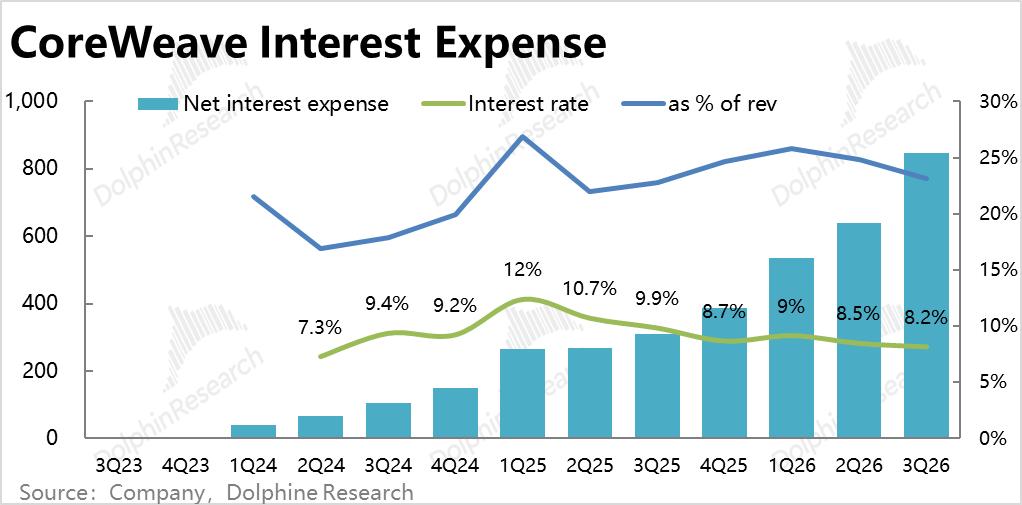
Net interest this quarter was 846 million USD, lower than the lower end of the guidance of 860 million USD. According to the rough calculation of interest / average total liabilities, the average interest rate decreased from 8.5% to 8.2%, so the proportion of interest in revenue also decreased.
Different from the obvious rise in new cloud bond issuance costs in the recent market, looking back, the interest rate of the company's existing debt is instead declining, which is quite unexpected. But this only reflects historical conditions, and we should remain cautious about subsequent interest pressure. Moreover, at present, adjusted operating profit still cannot cover interest, and the money earned is still not enough to cover the capital cost of debt.
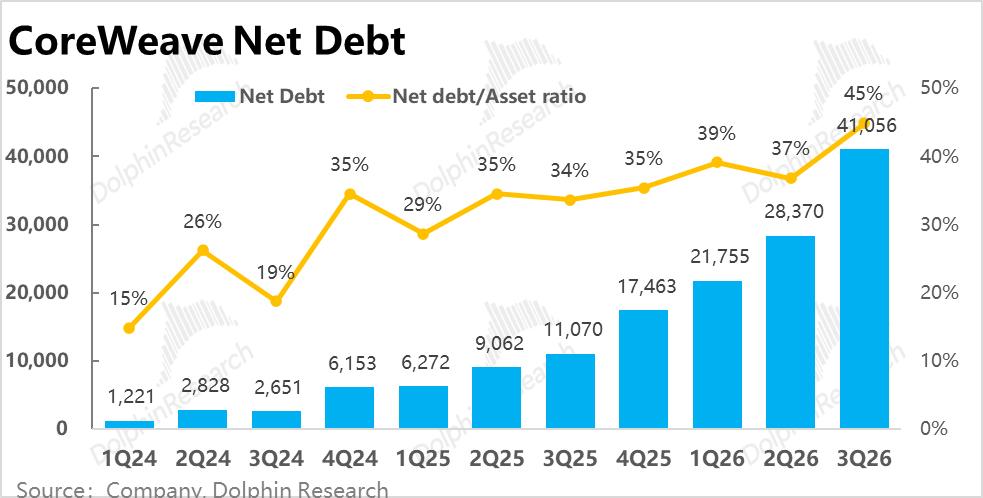
And although interest expenditure is slightly lower, total debt (including finance leases) at the end of this quarter is about 47.5 billion USD, liabilities increased by about 12.2 billion USD in a single quarter, which is also a new historical high. In order to support the continuously rising Capex investment demand, the company's financing pressure has not decreased.
4Q and full-year guidance: Revenue and profit are raised across the board, 4Q interest continues to rise
In terms of the outlook for the next quarter, the full-year guidance implies 4Q revenue of 46.9~49.9 billion USD, about 3% higher than the consensus expectation of 47.0 billion USD. Calculated at the upper limit, the net sequential increase is 13 billion USD, the growth will continue to accelerate compared with this quarter.
The adjusted operating profit guidance implies 7.5~8.5 billion USD in 4Q, the midpoint is about 20% higher than the consensus expectation of 6.6 billion USD, corresponding to a profit margin of about 16.5%, the profit margin will also continue to increase by a large margin.
The year-end ARR (annualized revenue) guidance was raised from 18.5~19.5 billion USD to 20.0~21.0 billion USD, with a consensus expectation of about 18.9 billion USD.
However, the 4Q interest guidance is 10.5~11.5 billion USD, the midpoint is about 9% higher than the consensus expectation of 10.1 billion USD, an increase of about 30% compared with this quarter, which is equivalent to the sequential growth rate of 4Q revenue, the proportion of interest eating into revenue has not decreased significantly.
7. Overview of core indicators
Dolphin Research View:
1. Summary of this quarter's financial report performance
Judging from this quarter's revenue, orders, next quarter's revenue guidance and continuously improving profit margin, CoreWeave's business itself is improving: demand is strong, prices are rising, and profit margins continue to climb. But correspondingly, the "cost" paid to support the business is also rising: liabilities increased by about 12 billion USD again in one quarter, interest is still higher than adjusted operating profit, Capex has risen sharply and free cash flow is deeply negative.
At the same time, what the market really cares about, and what is ultimately reflected in valuation, is whether the demand in 2027 and beyond can continue, and whether the currently rising computing power leasing price (that is, the situation of supply shortage) will reverse. These questions cannot be answered by the recent impressive performance. Therefore, the market will give a small reward to this good performance, but it cannot bring a real logical reversal.
2. Performance outlook, the short-to-medium term trend continues to rise
In the short term, the upward momentum of performance is relatively clear: the 4Q guidance implies that revenue will increase by about 30% QoQ, the adjusted operating margin is about 16.5%, the year-end ARR guidance is raised to 20.0~21.0 billion USD, and the management also stated that prices are still rising in 4Q.
Looking a little longer, the company gave its first profitability timeline: adjusted net loss will narrow significantly in 2027, and adjusted net profit will turn positive in the first half of 2028 and for the full year.