The breakout Chinese AI sensation has emerged: Sand.ai secures $200 million in financing.
It is rare to see such a large-scale financing deal in the second half of the year.
Pedaily has learned that Sand.ai, a video large model enterprise, has announced the completion of a $200 million Series A+ financing round. This round of financing brings together investment forces from industrial capital, well-known RMB and USD funds, Shanghai state-owned assets and other parties. Among them, Jiyuan Capital and Wangsu Science & Technology (300017.SZ) jointly led the investment; well-known institutions including Times Capital, Panlin Capital and Dongzheng Capital participated in the investment; Tianchuang Capital, together with Shandong Tietou Venture Capital and Shandong Railway Fund, participated in the investment strategically; Shanghai state-owned background institutions such as Pudong Venture Capital and Shanghai Guofang joined the round; old shareholders including Matrix Partners, Huaye Tiancheng and CAS Star continued to increase their positions.
It has only been a few months since the company's last round of financing. Looking at a longer timeline — from the beginning of this year to now, Sand.ai has completed three consecutive rounds of financing in ten months, with a total financing amount of about 300 million US dollars, officially entering the unicorn rank.
The significance of this financing goes far beyond the birth of a new unicorn. In a track where rules are still defined by tech giants, a startup established less than three years ago is answering a bigger question in its own way: can the next chapter of China's AI industry only be written by tech giants?
Three Rounds of Financing in 10 Months
The Birth of a New Unicorn in Video Generation
This time, Sand.ai has gathered almost all types of capital from the primary market behind it.
Looking at the investor lineup of this round, industrial capital, leading market-oriented institutions, local state-owned assets and old shareholders all appear collectively. The four types of capital have different demands, but they have reached a consensus on the same target. When different types of capital appear on the shareholder list at the same time, it indicates that the expectations placed on Sand.ai are not single-fold.
Among them, the appearance of Wangsu Science & Technology is a noteworthy signal. In fact, at the end of September this year, Wangsu Science & Technology announced this investment through a public notice: it plans to use 300 million yuan of its own funds to subscribe for 2.1054 million newly issued Series A+ preferred shares of Sand.ai.
Why would a veteran manufacturer that has been engaged in CDN business for 17 years bet 300 million yuan on a video model startup established less than three years ago in one go?
The explanation in the public notice is not complicated: "It will help the company understand the industrial development and technology direction, promote both parties to leverage their respective advantages, focus on scenarios such as audio and video inference, low-latency edge inference, and intelligent solutions for government, enterprise and internet industries, and carry out cooperation in business collaboration, technical support, technical cooperation and industrial ecology co-construction." In other words, this is a typical "industrial player's strategic stake placement" — the listed company is not making a financial investment, but buying a ticket for its next stage of business growth.
As the co-lead investor of this round, Jiyuan Capital's status in the investment circle is self-evident. This veteran venture capital institution has been relatively restrained in making moves in the AI field in the past, and rarely follows the trend to place bets on early large model projects. This time choosing to make a heavy position investment means that the institution judges that Sand.ai has crossed the "laboratory prototype" stage, and the investment is not for short-term valuation arbitrage, but for the long-term returns brought by the future infrastructure development of video generation.
Looking closely at the group of follow-on investors, each carries a differentiated investment logic. Among them, Times Capital is a typical cross-border growth fund with deep layout in AI infrastructure, good at capturing Chinese technology companies that have both overseas product revenue and open source ecosystem capabilities; Tianchuang Capital, Shandong Railway Fund, Shandong Tietou Venture Capital, Panlin Capital and Dongzheng Capital represent the choices of another group of RMB funds, most of which rely on resources from industrial groups or securities firms, and their AI model investment is more based on the idea of completing the industrial chain layout.
There are also new entrants of Shanghai state-owned assets — Pudong Venture Capital and Shanghai Guofang. Different from market-oriented institutions that mostly pursue financial returns, state-owned institutions have additional consideration dimensions of industrial agglomeration goals, and investing in Sand.ai can just improve the local AI industrial chain.
In contrast to the new shareholders are the old shareholders who have followed the company all the way to the present: Matrix Partners, Huaye Tiancheng and CAS Star. They are among the first group of people to recognize the value of Sand.ai. The continued additional investment in this round undoubtedly sends a signal that the previous investment logic still holds, and the company's technology iteration and commercialization progress are moving forward steadily. The significance of old shareholders increasing their positions is not just "being optimistic", but using the pricing of subsequent rounds to negate the judgment that "the valuation has already peaked".
When we extend the timeline, Sand.ai's financing pace this year is impressive.
In June earlier this year, the company announced the completion of two rounds of financing totaling more than 100 million US dollars, jointly invested by first-tier institutions including Look Capital, Lollapalooza Capital (Wang Huiwen's family office), JiuKun Venture Capital, Matrix Partners, MSA Capital, Sinovation Ventures, Xianghe Capital, Source Code Capital, CAS Star, Hongtai Fund, Capital Today, Huaye Tiancheng, Yunhui Capital, IDG and Baidu Ventures.
Up to now, Sand.ai has completed three consecutive rounds of financing in less than a year, and the company's valuation has risen rapidly, crossing the threshold of unicorn.
At this moment, the AI investment logic in the primary market has been completely reconstructed. Everyone has bid farewell to the extensive investment mode of "valuing concepts while neglecting implementation", and turned to systematic investment that "values technology and closed-loop operation". Sand.ai completing three rounds of financing in one year is a microcosm of this trend.
A Breakthrough Research Sample
As this round of financing comes to light, a question that the outside world is more curious about emerges: under the circumstance that video model R&D requires high investment and the track is surrounded by giants, what kind of company can break through the encirclement?
Sand.ai is undoubtedly a case worthy of in-depth research.
Let's start with the path that large language models have gone through. In the past few years, whether it is overseas companies such as OpenAI and Anthropic, or domestic companies including DeepSeek, Zhipu AI, MiniMax and Moonshot AI, they have proven with real money that the large language model track will not have only one winner. Admittedly, gaps may widen between leading companies, but as long as they enter the first echelon, they can all obtain considerable market share, revenue and valuation.
For example, the "two leading large model stocks in Hong Kong stock market" that have taken the lead in listing have experienced a wave of correction in market value, but the hundreds of billions or even trillions of market value they once reached clearly shows how huge the potential space is; while DeepSeek's valuation exceeded 300 billion yuan in its first round of financing, and its valuation in the nearly completed second round of financing has also doubled. Therefore, for investors, even if they do not bet on the first place, capturing the second or third place will still bring generous investment returns in the future.
This path is being replicated in the video model track.
There is no doubt that Seedance under ByteDance has established a clear leading position in the track by virtue of its internal ecology and computing power advantages. But the key point is — Seedance is an internal business of ByteDance, and external investors hardly have the opportunity to invest in it directly.
Therefore, a realistic question is placed in front of investors: in the video model track that is bound to give birth to multiple leading enterprises, which other startup company not only has model capabilities that have the opportunity to approach or even challenge Seedance, but also has an open equity structure? It is certain that investors are making investment moves along this screening condition.
Back in 2024 when Sand.ai was founded, the Diffusion route was still the consensus in the video generation field at that time, but Sand.ai chose to explore autoregressive video generation and launched the R&D of the MAGI model. Cao Yue, the founder of Sand.ai, once judged that autoregression is the most essential modeling method for video data.
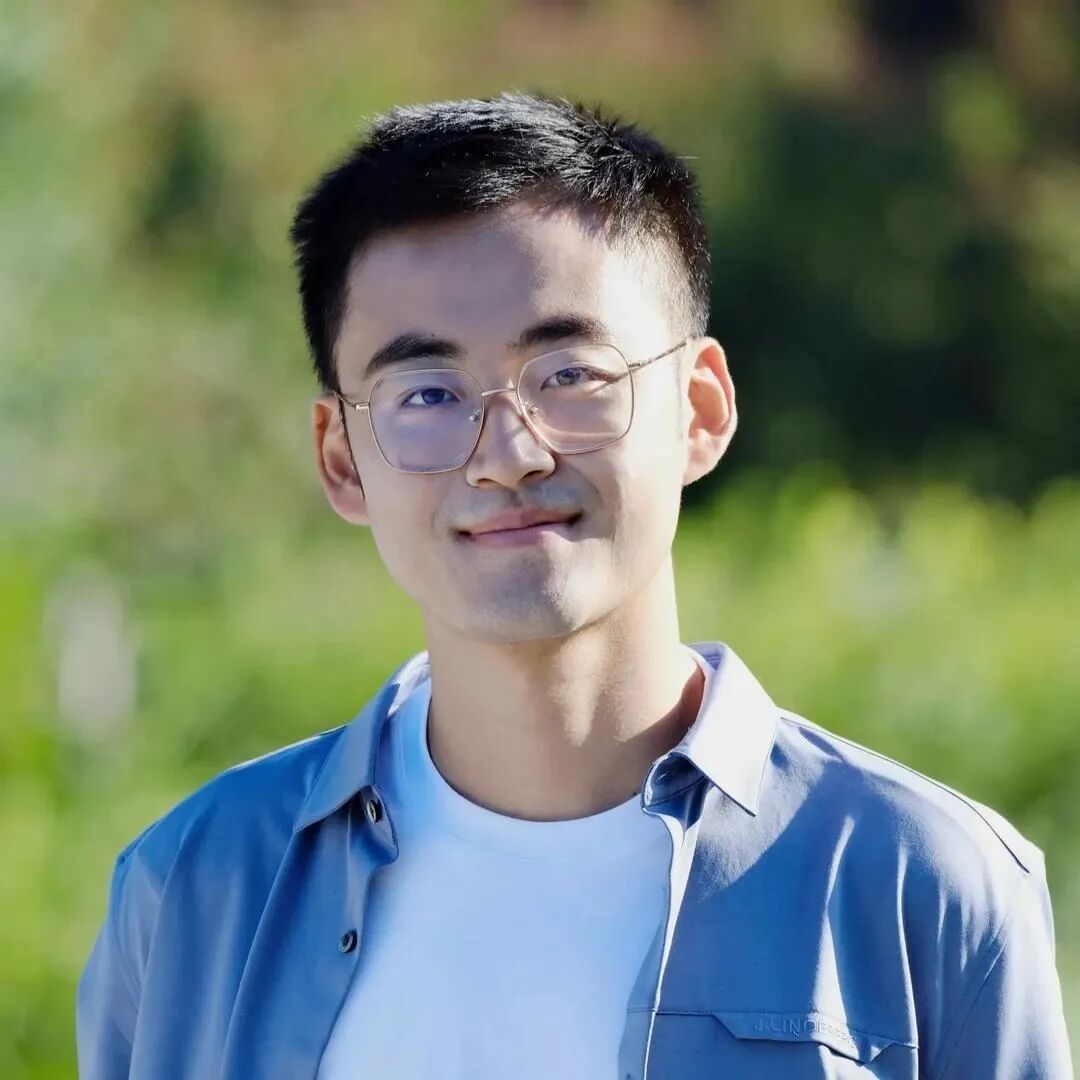
This judgment was not popular at that time, because it meant a longer training cycle and higher engineering difficulty; but at the same time, it also meant that once the path is proven feasible, the team will accumulate systematic capabilities that others cannot make up for in the short term.
Subsequently, Sand.ai began to explore simultaneous generation of audio and video in May last year, and it is the earliest team to launch a model that can generate audio and video synchronously besides Google Veo-3; later, when the team realized that there is an impossible triangle of "cost, speed and effect" for video models, it decisively explored the MoE architecture.
From the perspective of the primary market, a team that dares to place bets before the consensus is formed and continuously verifies its judgment through model iteration is a scarce asset in itself.
What tests people more is their concentration. Over the past year, world models have become a trend in the primary market, and many video model companies have chosen to shift their R&D focus to the direction of 4D world models, but Sand.ai has not followed the trend blindly, and has focused on training basic video models. In Cao Yue's view, world models are still in the pre-GPT era — with insufficient data, unclear definitions and far from converged technical routes, and video models are the most important path leading to that final destination.
In August this year, Sand.ai officially released and open-sourced MAGI-2 Preview. This is the world's first 100-billion-level open-source MoE video generation model: the total number of parameters reaches 114B, with about 6B parameters activated in a single run. The distilled model has an inference cost of about 0.5 yuan for generating a 10-second 1080p video, which is about one-tenth of the per-second cost of mainstream models in the industry.
For investors, apart from the extremely low generation cost, MAGI-2 Preview more importantly proves one thing: Sand.ai has initially run through the Scaling path of large-scale video models, and has the R&D capability to train ultra-large-scale video generation models, and this capability is reusable and can continue to expand the parameter scale. The only question that needs to be considered next is "how high this capability can be improved".
Another puzzle piece beyond technology is the product closed loop. Beyond the model side, Sand.ai has quietly built an application line. Its AI video creation application VidMuse is a video creation Agent tailored for content creators, which has exceeded 10 million US dollars in ARR just two months after its launch at the beginning of the year.
As Cao Yue said before, "In the video model direction, it is difficult to only be a company that sells APIs. Models and products must be driven by two wheels." In a track where the speed of model iteration is measured in months, products are not only the source of revenue, but also the entry point for model capabilities to obtain real feedback and form a data flywheel.
In the final analysis, the rise in Sand.ai's valuation is not a capital premium for a story, but a pricing for this partially verified path.
Trillion-Yuan Valuation Emerges
The Prologue Unfolds
If we look at it in a larger coordinate system, this narrative has only just begun.
A notable change in the video generation track since this year is that more and more leading manufacturers have begun to lay out both basic models and content platforms at the same time. For professional content producers such as advertising agencies, film and television studios, and e-commerce teams, this business pattern also brings new concerns: if the basic model supplier itself also operates a content platform, customers need to consider potential business competition, changes in platform rules, and dependence on a single technology supplier.
Precisely because of this, it has created new market opportunities for independent basic video model companies.
As an independent and neutral basic model supplier for the content industry, Sand.ai can rely on high-quality model capabilities, competitive costs and an open technology ecosystem to provide stable and reliable video generation capabilities for various content platforms and professional creation teams.
Furthermore, Sand.ai is more focused on basic model R&D and does not directly participate in customers' content business, so it can establish broader cooperative relationships with different types of platforms and developers. It is not difficult to understand that Sand.ai has reduced the cost of generating a 10-second 1080P video to 0.5 yuan, which is not only a manifestation of technical efficiency, but also a pricing strategy: on the premise that model capabilities are close, cost advantage itself is the shortest path for customers to switch suppliers.
The emergence of Keling has opened up the valuation space of the entire track. Not long ago, Kuaishou released an announcement that the 19.8 billion yuan capital increase and delivery of Keling was officially completed, with a post-investment valuation as high as 18 billion US dollars (equivalent to more than 1.2 trillion yuan). A video model company obtaining a valuation at the level of 100 billion yuan sends out a positive signal beyond doubt.
Putting the two together, we cannot deny the order-of-magnitude gap between them. But conversely, this also means greater upside potential. Historical experience shows that every technological iteration will bring a wave of valuation jumps — everyone is watching the upcoming official version of MAGI-2 to be released by Sand.ai.
According to Sand.ai's plan, the parameter scale of the official version of MAGI-2 will be further expanded. Before that, the Preview version has run through the Scaling path of the MoE architecture with 114B total parameters and 6B activated parameters. Therefore, what the official version needs to answer is another question: can a Chinese startup push video models to the top tier in the world?
If the official version of MAGI-2 meets expectations, a chain reaction will happen quickly: the influence of the open source community will further spill over to API commercialization; the content creation market will obtain a stronger and cheaper model base; the production cost of C-end Agent products such as VidMuse will continue to decrease, and the upper limit of creation will continue to rise. In this way, Sand.ai will have the opportunity to form a positive cycle of "model capability improvement — revenue growth — valuation re-pricing".
By then, Sand.ai will truly have the qualification to challenge Seedance and seize a seat among the leading players in the video model track.
This is also the most important thing on the agenda of Cao Yue, the head of Sand.ai. As a post-90s Tsinghua computer PhD, he has left many deep impressions on the public: from the Tsinghua Special Scholarship winner, ICCV 2021 Marr Prize winner, co-author of Swin Transformer, to the principal researcher at Microsoft Research Asia, head of the Vision Model Center at Beijing Academy of Artificial Intelligence, and then co-founder of Light Years Beyond, he has covered three lines of basic research, large model engineering and entrepreneurship at the same time. Such a compound background has always been the "voting ticket" that investors are scrambling for.
Looking back, China's primary market has seen too many AI stories go from carnival to desolation. It is certain that what really survives through cycles is never the concept itself, but teams that are stubborn enough on technical routes and down-to-earth in commercialization.
As for who the next enterprise with a trillion-yuan valuation will be, it still needs to wait for the verification of time. But the reason why a prologue is a prologue is precisely because it has not yet reached the final chapter.
This article is from the WeChat official account "Pedaily" (ID: pedaily2012), written by Liu Bo, and authorized for release by 36Kr.