The brand is not for sale, while the controlling stake has been sold! "Separation of Three Powers" at A.O. Smith China
On October 27, the Milwaukee headquarters released an official announcement. A.O. Smith sold 81% equity stake of its controlling entity for China business to CPE Yuanfeng, retaining 19% of the stake itself, and signed a long-term brand licensing agreement at the same time.
The transaction values the China business at approximately 400 million US dollars on a cash-free and debt-free basis. When adding the net present value of brand licensing fees over the coming decades, the total value exceeds 500 million US dollars.
This is neither an exit from the Chinese market nor a direct sale of the brand. The brand ownership is retained, while the controlling stake and daily operation rights are transferred to local capital. The US party will continue to obtain returns through dividends from the 19% minority stake and long-term licensing fees.
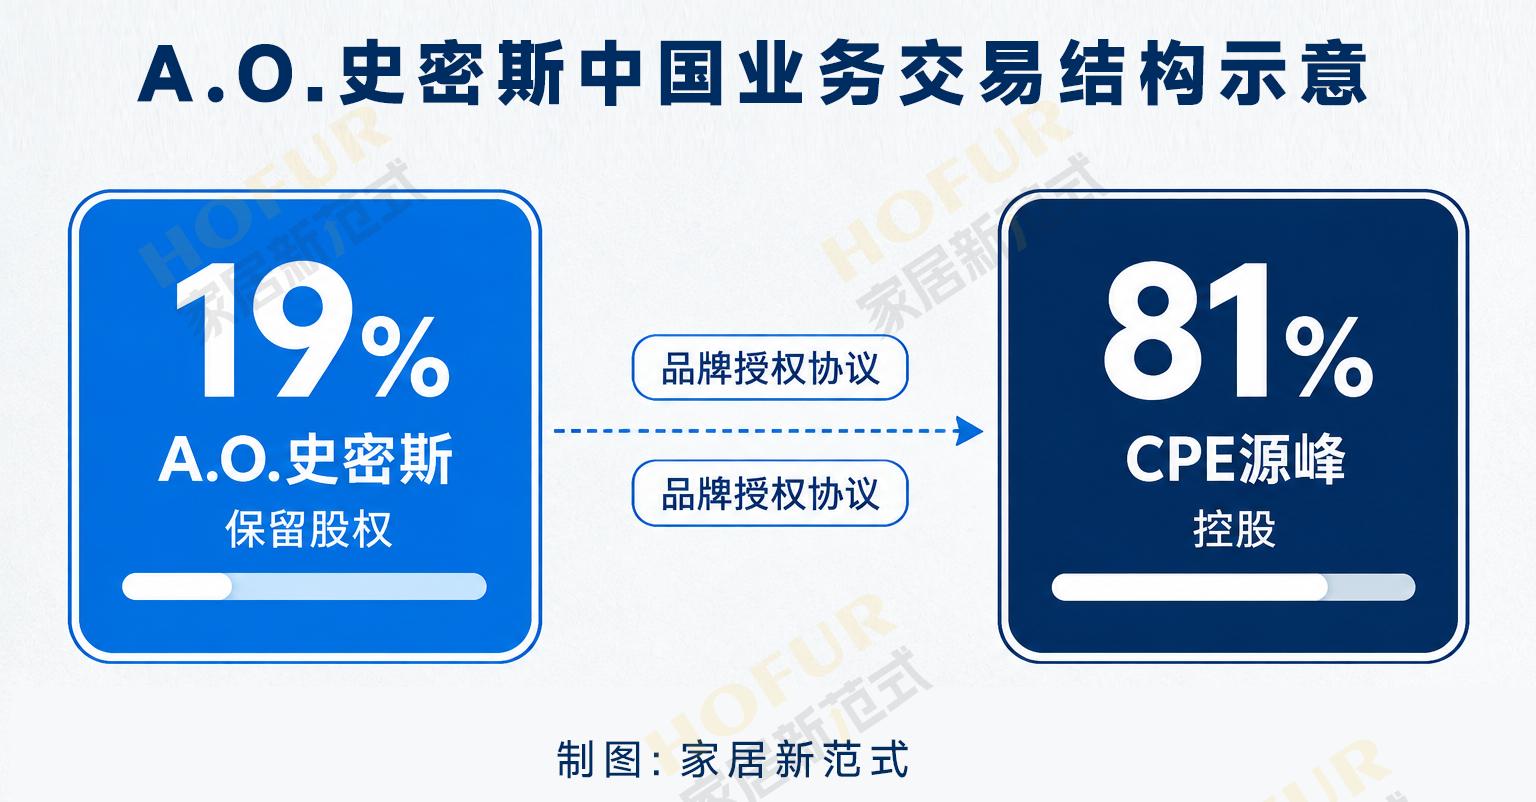
With this transaction, the foreign water technology enterprise has clearly realized the licensing and co-governance framework of "retaining brand ownership, localizing controlling stake, and structuring income rights" in the Chinese market. *New Home Paradigm* believes that this transaction has gone beyond the scope of ordinary equity transactions of water home appliances and comfortable home enterprises, and has become a landmark sample for foreign water home appliances and comfortable home brands to adjust their operation models in China.
The US party first balances its own books
A.O. Smith's China business has been under continuous pressure in recent years. In the third quarter of 2026, A.O. Smith's net sales in other regions of the world reached 192.8 million US dollars, down 7% year on year, of which the local currency sales in the Chinese market dropped by 17%. The official explanation is that weakening consumer demand, coupled with the strategic assessment process, has caused disturbances to channel operations.
Starting from the fourth quarter of 2026, the China business will be classified as discontinued operations and will no longer be included in the consolidated statements. After the transaction is closed, the remaining 19% equity stake will be accounted for under the equity method.
From the perspective of US stock shareholders, the logic of this transaction is clear. It unloads the growth pressure, recovers large consideration in one lump sum, and gains long-term licensing returns. The brand is still retained. If the Chinese market recovers later, the 19% equity stake can still share the growth dividends.
This is not a strategic surrender, but an adjustment to the asset operation ledger.
What CPE wants is assets with high recognition and low operational efficiency
The new controlling shareholder CPE Yuanfeng is a controlling alternative asset management institution, not an industrial operation enterprise. Cases such as Burger King China and Mammut have adopted similar operation ideas: take over foreign brands with high recognition but stagnant growth, rely on local teams to restructure channels and costs, and complete secondary capitalization exit through cash flow improvement in three to five years, which is also a typical path for private equity investment.
A.O. Smith China has a solid foundation, with accumulated high-end market mindshare over decades, mature sales and service networks, and a complete water technology R&D system still in place. Its shortcomings are also prominent: the decision-making chain of the multinational headquarters is lengthy, and its price range is continuously squeezed by domestic brands such as Haier, Midea, Casarte, COLMO and Angel.
After the handover, the business will most likely be adjusted along three main lines.
The proportion of non-water kitchen appliance categories will be reduced, focusing on the core tracks of water heaters, water purification and water softening, while water systems and whole-home comfort scenarios will still be the long-term development direction. The channel model will be transformed from simple inventory pushing to channels of decoration enterprises and designers, as well as stock renewal services. The product logic will be upgraded, no longer selling single water purification units, but turning to providing complete whole-home water system solutions.
As a private equity capital, CPE pursues clear investment returns and will not only maintain the brand tone. Repurchase rate, service retention and increase of customer order value are the core assessment indicators. For the US party, the brand licensing fee is a long-term "rent-collecting" cash flow, while for CPE, it is a key variable for the exit valuation in the future.
The advertising slogan of "washing for half a century" is still fresh in people's memory. Before the half century is over, the controlling stake transaction has been settled, and the operation right will be gradually transferred with the closing in 2027. With the asset-light structure of "local capital operation + long-term brand licensing", A.O. Smith has explored a second path for foreign water technology brands.