Character.AI declares bankruptcy, is AI companionship a false overhyped industry trend?
After Character.AI filed for bankruptcy protection, the AI companionship business is being re-examined.
This star company, which was valued at 1 billion US dollars with tens of millions of monthly active users just over a year after its establishment, was once regarded as one of the most representative players in the AI companionship track. With products that allow users to chat with virtual characters, it attracted a large number of users and capital, but eventually moved towards bankruptcy restructuring.
On October 12, the parent company of Character.AI filed for bankruptcy protection. Continuous computing power investment, operating costs, as well as minor protection-related lawsuits and regulatory pressures have pushed this star company into operational difficulties. At present, Disney has become the first bidder with 20 million US dollars, bidding for the non-exclusive permanent license of part of its intellectual property. The star company whose valuation once reached 1 billion US dollars now has to dispose of part of its assets through bankruptcy proceedings.
However, the fall of Character.AI does not mean that the AI companionship market has lost its growth momentum. Another AI character chat platform Chai disclosed that as of the beginning of October, its daily active users exceeded 1 million, and its annualized revenue scale reached 120 million US dollars. According to data from Sensor Tower, in the first quarter of 2026, the revenue of global AI companionship mobile applications reached about 150 million US dollars, more than 12 times that of the same period in 2023.
The domestic market also gathers many players. From Xingye and Talkie under MiniMax, to Cat Box under ByteDance, and a number of entrepreneurial products focusing on segmented needs, enterprises of different backgrounds are exploring the commercial opportunities of AI companionship.
On the one hand, star companies with tens of millions of users are heading for bankruptcy, on the other hand, industry revenue continues to grow and different players are exploring monetization paths respectively. The AI companionship industry shows obvious differentiation.
All are accompanying users to chat, why can some people make money from it, while others lose more and more? What kind of business is AI companionship on earth?
01. AI Companionship: Some Go Bankrupt, Some Keep Growing
The overseas market first produced a number of star products, and was the first to accept the test of commercialization.
Character.AI once accumulated a huge user base through virtual character chat, but the user scale did not translate into revenue sufficient to support operations.
According to Reuters, the company's monthly computing power expenditure was about 13.8 million US dollars in 2024, dropped to about 10 million US dollars in 2025, and accumulated about 56.1 million US dollars from January to August 2026. On the revenue side, monthly subscription revenue increased from about 600,000 US dollars in January 2024 to about 2.8 million US dollars in August 2026; advertising revenue increased from about 500,000 US dollars in July 2025 to 2.5 million US dollars in August. The total revenue in August was about 5.3 million US dollars, which was still not enough to cover its operating expenses.
It is worth noting that Character.AI adopts a "free + paid model". The paid version is divided into a light membership of 4.99 US dollars per month or 2.49 US dollars per week; a premium membership of 9.99 US dollars per month or 94.99 US dollars per year. The lower-priced model was only launched in September 2026 to ease the financial pressure of continuous losses. But before filing for bankruptcy, it still lost 8 million to 9 million US dollars per month.
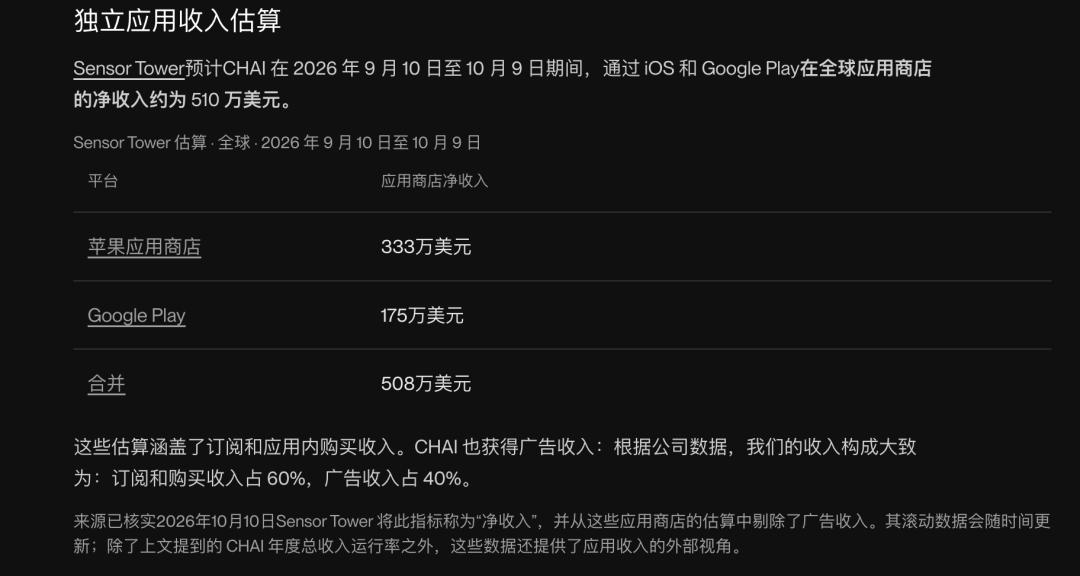
Chai, another platform that also focuses on AI character interaction, has a different situation. As of early October 2026, its daily active users exceeded 1 million, and its annualized revenue reached 120 million US dollars. Chai stated that the company has achieved a positive unit economic model and is profitable after excluding sales and marketing expenses. However, these data are unaudited and do not mean that the company's overall net profit has turned positive.
Chai's fees are divided into consumer subscriptions, in-app purchases and advertisements. According to the data cited on its official website, from September 10 to October 9, 2026, the net revenue of its app store was 5.08 million US dollars (mainly covering subscription and in-app purchase revenue). According to the company's data disclosure, about 60% of its revenue comes from subscriptions and in-app purchases, and 40% comes from advertisements.
In addition, early-entry AI virtual companion products such as Replika are still in operation. The user scale, revenue level and operating results of different products are not consistent.
Compared with overseas, there are also many players in the domestic AI companionship market, which can be roughly divided into three categories.
The first category is large model manufacturers, represented by MiniMax. It has successively launched AI character interaction products such as Xingye (domestic) and Talkie (overseas), applying underlying model capabilities directly to the consumer market, and monetizing mainly through subscriptions and advertisements.
AI companionship applications were once an important support for MiniMax's early commercialization. According to data previously disclosed by the company, in the first nine months of 2025, the combined revenue of Talkie and Xingye was about 18.75 million US dollars, contributing about 35.1% of the total revenue, exceeding the 32.6% of Hailuo AI. Among them, Talkie is also one of the important products for MiniMax to open up overseas markets.
But this business does not mainly make money from membership subscriptions, but relies more on online marketing services such as advertisements. In the first nine months of 2025, the two products generated a total revenue of 18.75 million US dollars, of which online marketing service revenue was 11.188 million US dollars, accounting for about 59.7%; subscription revenue was 6.604 million US dollars, accounting for about 35.2%; in-app recharge revenue was 958,000 US dollars, accounting for about 5.1%.
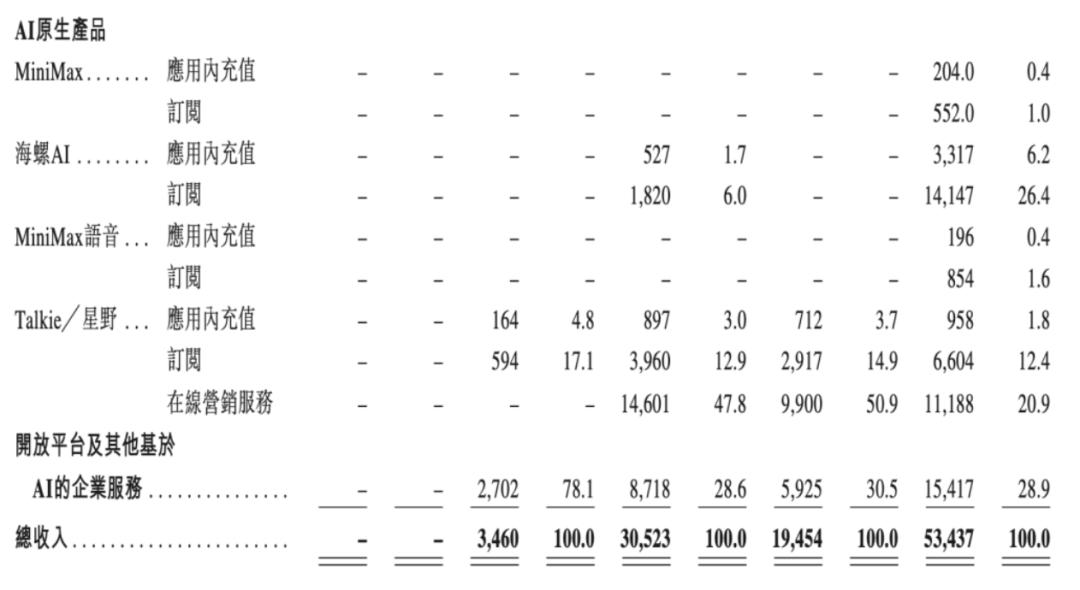
Even if advertisements account for the majority, it does not mean that related businesses have a high gross profit margin. From the perspective of MiniMax's broader AI native product business, including Talkie, Xingye, Hailuo AI and other products, the gross profit margin was -8.1% in 2024; it only turned positive in the first nine months of 2025, reaching only 4.7%. But it should be noted that this is not the separate gross profit margin of Talkie and Xingye.
In terms of user scale, as of August 2026, Talkie had about 31.07 million global monthly active users, and Xingye had about 3.38 million. However, some products previously saw a significant decline in new downloads. Data from Diandian previously showed that from January to May 2025, the monthly downloads of Xingye on Apple's iOS platform dropped from 4.86 million to 930,000, a decrease of about 81%, but the daily active users in January and May were about 960,000 and 970,000 respectively, remaining basically stable.
More notably, MiniMax's revenue focus is shifting. In the first half of 2026, the company's AI native product revenue was 42.64 million US dollars, and its proportion in total revenue dropped from 69.7% in the same period of last year to 36.6%; the revenue proportion of open platform and enterprise services rose to 63.4%. This large model company that first opened up the market through AI companionship now derives its growth momentum mainly from the enterprise side.
The second category is incubated by Internet and content platforms, such as Cat Box under ByteDance, and Dreamland incubated by China Literature (now operating independently). Such enterprises have advantages in traffic entry, product operation and user reach, and can integrate AI character interaction into the existing consumer Internet ecosystem.
Sensor Tower data shows that in the first quarter of 2026, Cat Box ranked first in the iOS AI application revenue list in China, and its cumulative iOS in-app purchase revenue has exceeded 22 million US dollars, which does not include Android channel and advertising revenue. In August 2026, calculated by the iOS revenue created by a single monthly active user, Cat Box was about 5 times that of Jimeng AI, 4 times that of AI Mate, and also about 4 times that of Xingye and Dreamland.
The way Cat Box makes money is also different from the traditional membership system. In addition to subscriptions and advertisements, there is also virtual currency recharge. Cat Box's continuous monthly membership is 25 RMB, and users can get longer voice call time, more advanced dialogue modes and other rights; in addition, users can also buy virtual currency called "cat food", 100 cat food is sold for 1 RMB, which is used to unlock some plot chapters, character dynamics and other content, and can also obtain cat food by watching advertisements. It provides an additional revenue source for AI companionship besides subscriptions, but there is no official disclosure on which method contributes more revenue at present.
The third category is independent startups. Such players usually do not have the traffic base of large factories, nor do they necessarily have self-developed large models, so they rely more on product positioning, user needs and operational efficiency to find market space. For example, Xinyingsuixing, which obtained tens of millions of US dollars in Series A+ financing, launched Doudou AI, which focuses on real-time game companionship; Solulu, which has original IP and focuses on AI chat companionship; and Tianzhiling AI mentioned below.
Such players are usually small in scale, more focused on products, and compared with the first two types of players, the common problem faced by independent startups is how to attract users, establish a payment model, and control the continuously generated model calling cost under limited resource conditions.
On the AI companionship track, having technology, traffic or content resources does not mean that you can definitely succeed. Large model manufacturers have technical advantages, Internet platforms have user bases, and content companies hold IP resources, but these advantages will not automatically translate into commercial returns, and even become cost burdens.
02. Revenue Is Rising, Why Is It Still Difficult to Make Money?
AI companionship is not short of growth stories, what is missing is a profitable model that can be implemented.
From the overall industry perspective, AI companionship is still heating up. According to data from China Research and Development Institute of Industrial Economics, China's AI emotional companionship market alone reached 3.866 billion RMB in 2025, and it is expected to exceed 59.5 billion RMB in 2028, with an annual compound growth rate as high as 148.74%. At the same time, the revenue generated by global AI companionship apps in the first half of 2025 has reached 82 million US dollars, showing an obvious year-on-year growth trend.
However, more than one AI companionship application entrepreneur told AIX Finance that the more realistic situation is that profitability is still a practical problem faced by many practitioners.
The problem lies in both the revenue and cost sides.
First look at the revenue side: users' willingness to pay for independent applications is weakening.
Previously, capabilities such as long-term memory, role-playing, and voice interaction were once important selling points for AI companionship products to attract users. But with the continuous upgrading of large model capabilities, these functions are no longer exclusive to dedicated AI companionship applications. For basic needs such as daily chatting, pouring out troubles, and seeking emotional comfort, users can fully open general AI assistants such as Doubao and ChatGPT.
Source / Unsplash
Zhang Yi, an AI companionship entrepreneur and founder of Tianzhiling AI, believes that if an AI companionship product only accesses the model API of other companies and provides simple dialogue functions, it really does not make much difference from a general AI assistant.
An AI product manager told AIX Finance that a well-recognized industry consensus is that in the past, some AI companionship products attracted users through more intimate role interactions, ambiguous relationships, and even content with adult hints, which may be the main reason why some users are willing to pay.
But in China, supervision is getting tighter and tighter. Relying on breaking content boundaries to attract users, even if revenue can be obtained in the short term, it is difficult to become a stable and sustainable business model.
This means that it is increasingly difficult for independent applications to charge users solely by "being able to chat".
Then look at the cost side: the cost structure of AI companionship is different from that of traditional Internet products.
The Internet industry is accustomed to measuring product value with indicators such as monthly active users, retention rate, and usage duration. The more users there are and the longer they stay, the greater the advertising monetization space usually means, and the easier it is to get capital attention. Traditional Internet products serve one more user, and the marginal cost is almost negligible.
But every time a user of an AI companionship product initiates a conversation, model inference costs may be incurred. While the user scale and usage duration increase, the service cost that the enterprise needs to bear may also grow simultaneously.
Zhang Yi believes that directly moving the growth logic of the traditional Internet to the AI companionship industry may be a risk faced by entrepreneurs. For example, some entrepreneurs hope to increase user activity through operational means, but ignore that AI dialogue itself requires continuous cost. Some heavy users may send 20,000 to 30,000 messages a month. If the product cannot control the cost of a single dialogue, such users may even bring losses to the enterprise.
The predicament of Character.AI is a case in point.
According to public materials, Character.AI has about 12 million active users. In August 2026, each active user on the platform brought in about 0.44 US dollars per month, of which advertising accounted for about 0.21 US dollars; while the computing power cost corresponding to each user was about 0.58 US dollars. The more active users are, the higher the computing power bill will be. Coupled with personnel expenses, litigation costs and regulatory pressure, the huge user scale did not bring narrowing of losses.
Chai has also experienced similar cost challenges. Its founder William Beauchamp once mentioned in a media interview that in some markets, for every 1 US dollar of computing power consumed by users, only about 0.1 US dollar of revenue can be generated.
An investor focusing on AI applications believes that what AI companionship enterprises need to calculate clearly is not only the customer acquisition cost and payment conversion rate, but also the continuous service cost generated by each user in the process of use. It is necessary to pay attention to how much revenue a user contributes in a certain cycle, after deducting direct service costs such as model inference, and whether these revenues can further cover customer acquisition and daily operating expenses.
In his view, entrepreneurs also need to figure out what kind of company they want to be first: a small company that can make continuous profits, or a company worthy of continuous investment from venture capital and has large-scale growth potential. The former only needs to find enough stable paying users and control operating costs within revenue; the latter must further prove that the user scale can expand, revenue growth is replicable, and growth will not continuously rely on high subsidies and computing power investment.
Of course, this does not mean that user scale has completely lost its value.
For AI companionship platforms adopting the advertising model, user scale and usage duration can still bring advertising revenue. Products such as Chai are also exploring the monetization method that combines subscriptions and advertisements. As long as the revenue brought by a single user can cover the cost he consumes, large-scale users can still become an advantage.