In the era of rising memory prices, the "sea-of-phones strategy" is on the wane.
The downward crisis in the mobile phone industry brought about by rising memory prices is still intensifying.
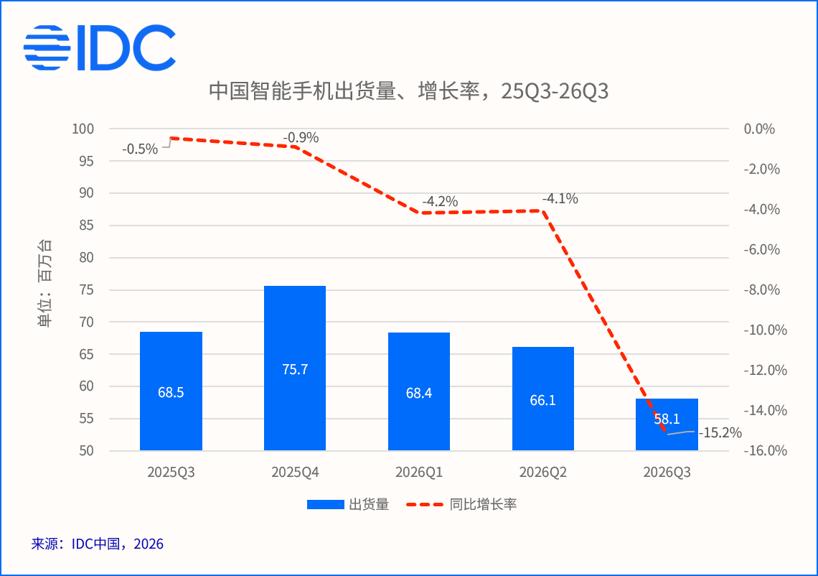
Data disclosed by IDC shows that in Q3 2026, the shipment volume of China's smartphone market reached 58.06 million units, a year-on-year decrease of 15.2%, further expanding from the roughly 4% decline in the first half of the year.
In response, Francisco Jeronimo, Vice President of IDC Global Devices, stated, "As prices rise, many consumers are choosing to extend the service life of their existing devices. Chinese brands are facing a particularly difficult situation, as they dominate the low-end smartphone market, which forces them to choose between protecting profit margins and maintaining sales volume amid weak demand."
Several months ago, when talking about the mobile phone industry entering an era of price hikes, Wang Teng, former General Manager of the REDMI brand, suggested that manufacturers suspend the release of new phones. This is because it is difficult to achieve major innovations in mobile phone hardware, and maintaining the original iteration model is very inefficient.
At that time, many netizens thought Wang Teng was "talking without standing in others' shoes", ignoring the objective laws of consumer market demand and technological progress.
Now it seems that Wang Teng's suggestion is not groundless. Facing the continuously rising storage costs, some mobile phone manufacturers have begun to slow down the pace of product updates and product line layout.
Although the ebb of the "sea-of-phones strategy" helps reduce the company's operational pressure, it is difficult for mobile phone manufacturers to get through the cycle only by relying on conservative business strategies.
01
The shrinking mobile phone market space leads to strategic contraction of manufacturers
Once upon a time, as the scale of China's smartphone market kept rising, the sea-of-phones strategy became one of the tried-and-true strategies for smartphone manufacturers to expand their market influence.
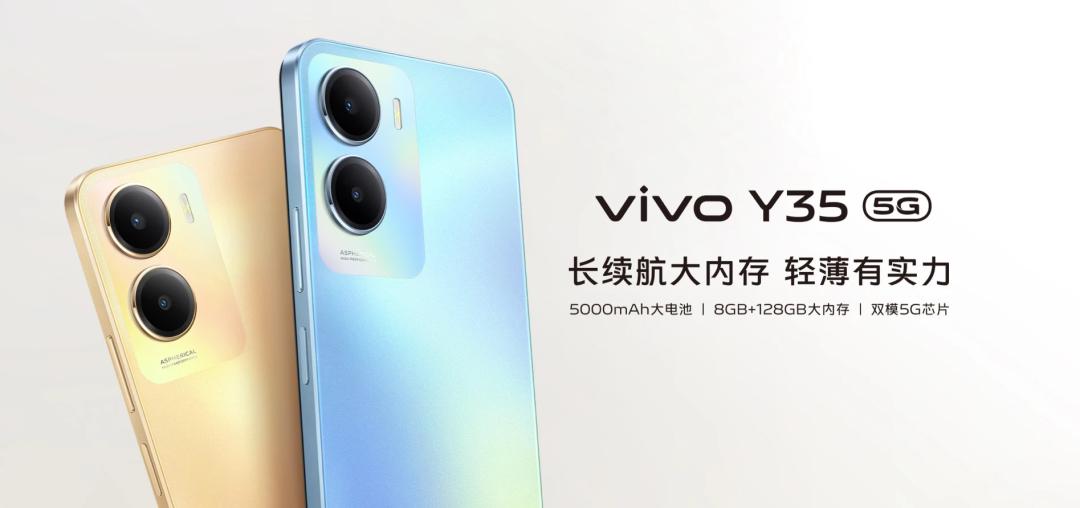
Taking vivo as an example, in 2022, it launched a total of 45 mobile phones, about 4 per month on average. It is worth noting that many new products launched by vivo do not have strong differentiation, and most of the mid-to-low-end mobile phones are "copycat products with similar shells".
Source: vivo
A typical example is the vivo Y35 series, which includes Y35, Y35+, Y35m and other models. They have highly similar appearances, with only differences in core configurations, and the price difference is a few hundred yuan, densely distributed in the thousand-yuan price range.
Relying on the sea-of-phones strategy, vivo did take the lead in the fierce market competition. Data disclosed by IDC shows that in 2022, vivo ranked first in China's smartphone market with a shipment share of 18.6%.
By 2026, under the skyrocketing memory price, the reason why the sea-of-phones strategy of smartphone manufacturers can no longer be sustained is, on the one hand, the shrinking market space, and on the other hand, the increasing memory cost pressure faced by mid-to-low-end mobile phones.
Source: IDC
From the market dimension, under the pressure of rising memory prices, mobile phone prices have risen synchronously, which has greatly suppressed consumer demand. IDC data shows that from Q4 2025 to Q3 2026, the year-on-year decline of China's smartphone market shipment volume was 0.9%, 4.2%, 4.1% and 15.2% respectively, and the decline gradually expanded.
In addition to the shrinking market leading to narrower living space, rising memory prices will also greatly erode the profit margin of mid-to-low-end mobile phones.
Recently, in an interview with CLSA, Wang Xudong from CINNO Research revealed that in Q3 2026, for a thousand-yuan mobile phone with 4GB+128GB configuration, the storage cost accounts for 64% of the total BOM cost of the whole device, up 42 percentage points year on year. "The increment of storage cost per single model will eat up all the profits of terminal manufacturers (for low-end products)."
Source: China Academy of Information and Communications Technology
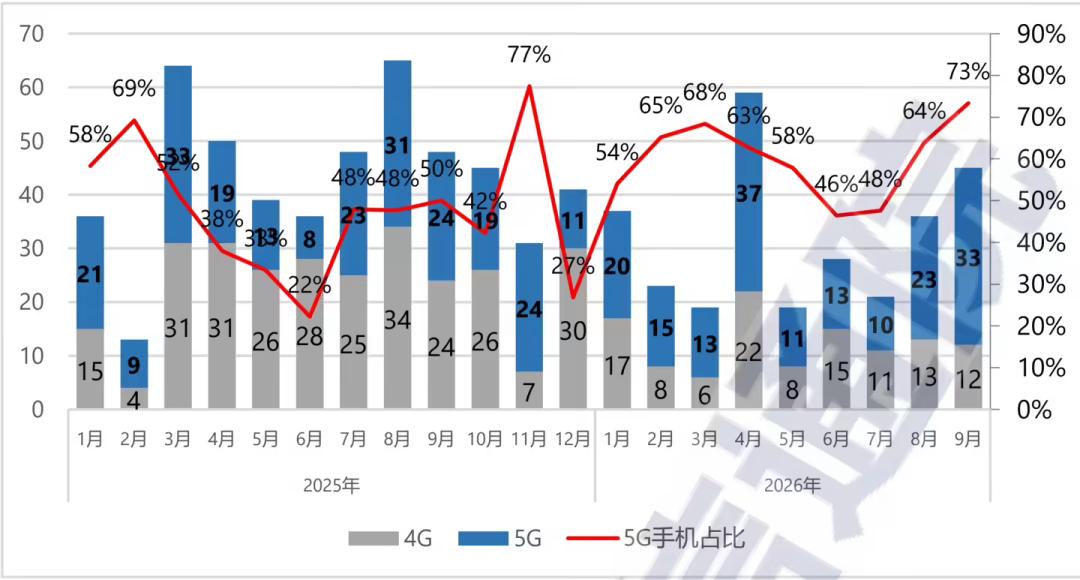
As the marginal revenue of the sea-of-phones strategy continues to narrow, many smartphone manufacturers have begun strategic contraction since 2026. Data disclosed by the China Academy of Information and Communications Technology shows that in the first nine months of 2026, 286 new mobile phone models were launched on the Chinese market, a year-on-year decrease of 28.1%.
Specifically for manufacturers, since this year, OPPO has been continuously integrating the business resources of OnePlus and realme. On July 16, realme announced that it would suspend product updates in the Chinese market, and subsequent new products will mainly target overseas markets.
In September 2026, when Apple launched its annual flagship, it did not update the standard version of iPhone 18, but only launched the iPhone 18 Pro series and the foldable screen phone iPhone Duo. In addition, according to the digital blogger "Digital Chat Station", series such as Xiaomi MIX Flip, Xiaomi Civi, and iQOO Ultra have stopped updating.
On October 24, "Digital Chat Station" further revealed, "Say goodbye properly, several familiar mobile phone product lines or tablet lines will stop updating next. The cost cannot be covered, and the more new products you release, the more you lose."
02
Profit vs. Sales Volume: Dilemma Under Cost Pressure
In the past few years, the reason why smartphone manufacturers relied heavily on the sea-of-phones strategy is largely that this strategy can achieve significant scale effects through component reuse.
Although many mobile phone products have raised their prices in the era of rising memory prices, for mid-to-low-end products, limited by product positioning, it is difficult to fully absorb the upstream cost pressure by raising prices. In this context, if mobile phone manufacturers continue to follow the previous product strategy, they will easily fall into the "scale trap".
Source: Xiaomi 2026 Q2 Financial Report
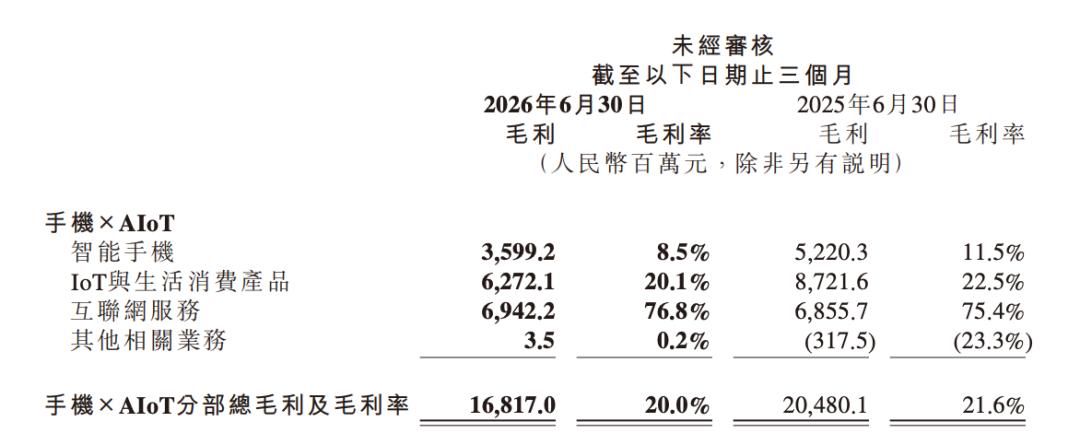
For example, in Q2 2026, the average selling price of Xiaomi mobile phones was 1351 yuan, a year-on-year increase of 25.9%, but the gross profit margin of the mobile phone business decreased by 3 percentage points year-on-year to 8.5%, "mainly due to the decline in gross profit margin of the mainland China business caused by the rise in core component prices."
In April 2026, when promoting the REDMI K90 Max, Lu Weibing, Partner, President of Xiaomi Group, President of the Mobile Phone Department, and General Manager of the Xiaomi Brand, said helplessly that the starting price of 2999 yuan for this mobile phone during the first sales period was sold at a loss.
Due to high cost pressure, the REDMI K90 series has adjusted prices frequently since 2026. Among them, the starting price of REDMI K90 Max has risen to 3899 yuan, an increase of as high as 30%.
Source: RD Observation
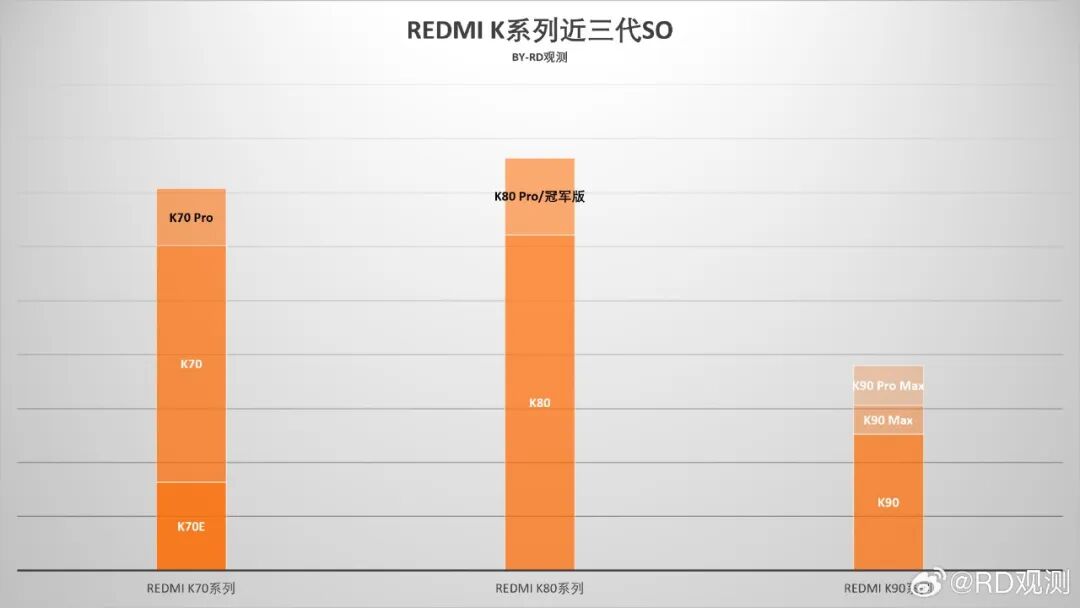
Although raising prices helps ease cost pressure, the higher purchase threshold will also suppress consumer demand. In August 2026, data disclosed by digital blogger "RD Observation" showed that the sales volume of the REDMI K90 series was 53.6% of that of the K70 series and 49.7% of that of the K80 series respectively.
For smartphone manufacturers, although a new mobile phone can reuse existing components, it still needs to invest resources in development and adaptation, marketing, channel stocking and after-sales support. Launching multiple products with similar positioning, if it cannot bring more sales, will disperse investment, increase inventory and clearance pressure in turn, and aggravate the operational burden.
03
After the Ebb of the Sea-of-Phones Strategy, the Industry's Key Competition Point Has Changed
The ebb of the sea-of-phones strategy does help improve the stress resistance of mobile phone manufacturers, but conservative business strategies can hardly help enterprises survive the downward cycle. If they want to show stronger competitiveness in the stock market, mobile phone manufacturers need to create more user value.
Source: Apple
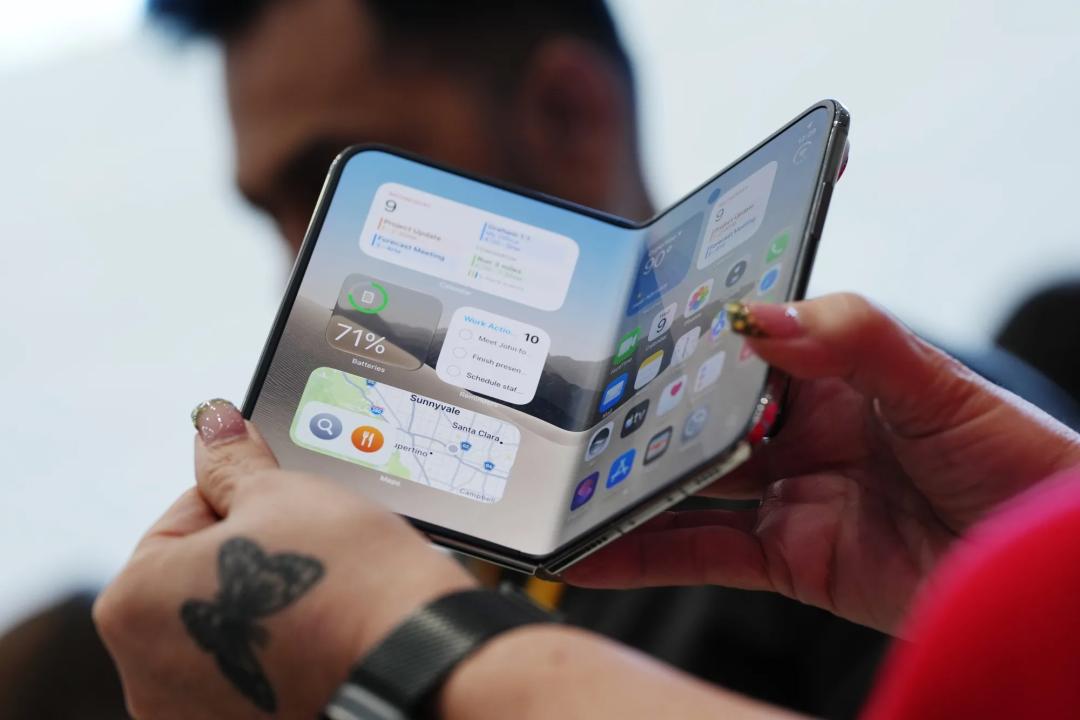
Taking Apple as an example, due to the weakening attractiveness of bar phones, it launched its first foldable screen phone iPhone Duo in September 2026, which adopts a horizontal inward folding design, with a 5.4-inch outer screen and a 7.6-inch inner screen. The aspect ratio of both the inner and outer screens is 1.4:1, and the starting price is 15999 yuan.
Although the concept of foldable screen phones is no longer new, iPhone Duo shows strong differentiation. The inner and outer screens of this product have the same aspect ratio, with a continuous flowing animation when opening and closing, resulting in stronger integration. In addition, Apple has strong ecosystem appeal, and the third-party application experience is also strongly guaranteed.
Source: TrendForce
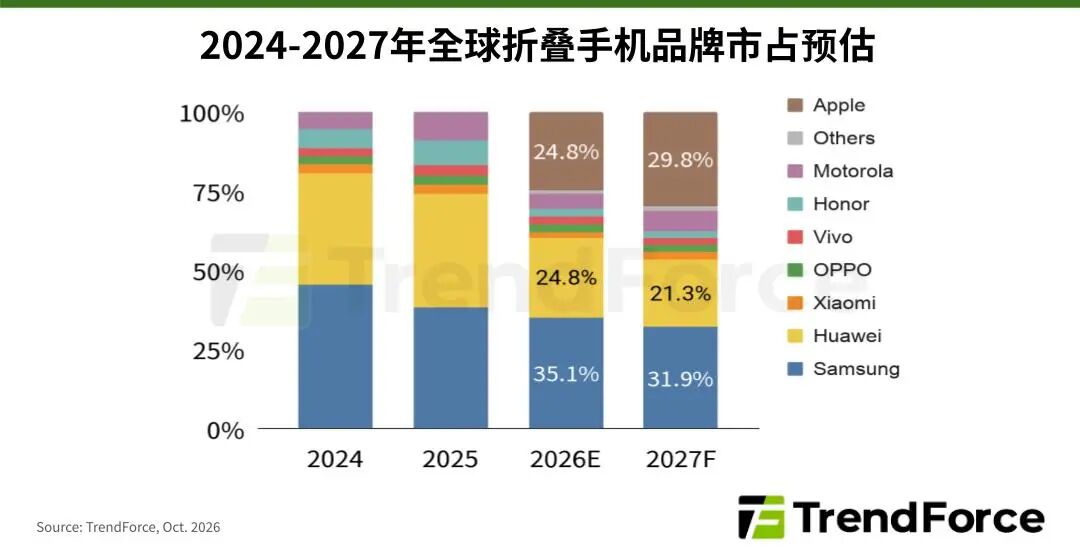
Thanks to this, although the price is high, iPhone Duo has captured a large number of consumers. According to the disclosure of "RD Observation", the sales volume of iPhone Duo was close to 200,000 units in the first four days of its first sale. TrendForce released a research report stating that it is expected that the shipment volume of iPhone Duo will reach 5 million units in 2026, taking 24.8% of the global foldable screen market share.
Source: Huawei
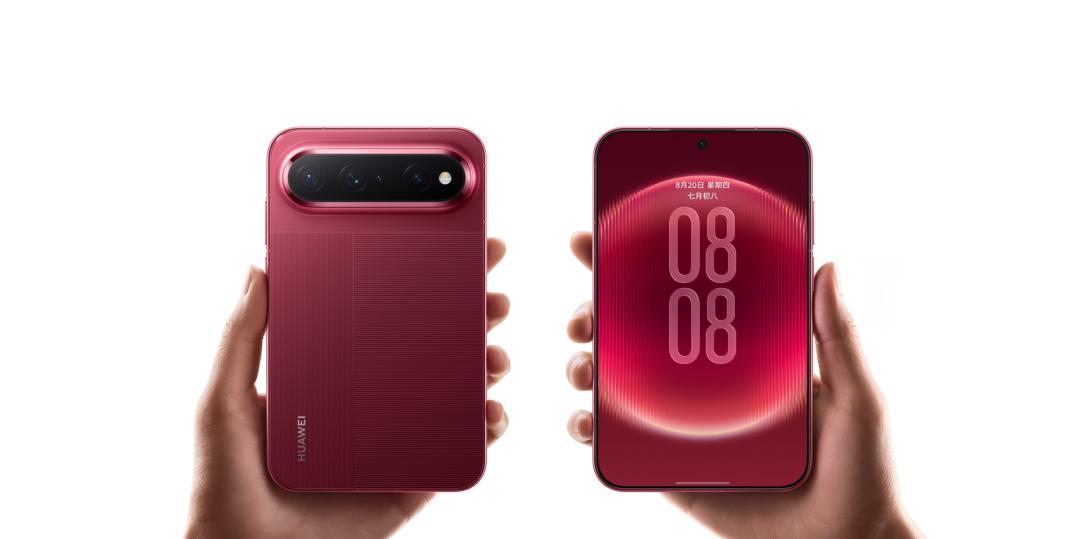
Coincidentally, Huawei also took a different approach and launched the wide-bar phone Pura X View in September 2026. Different from the "slender" aspect ratio of traditional smartphones, Pura X View adopts a "short and stout" design with a screen aspect ratio of 16:9.5, which can bring a stronger immersive experience when watching dramas, reading and playing games.
Due to its unique product form, Huawei Pura X View has also become a hit product. On October 29, "RD Observation" broke the news that the shipment volume of Pura X View exceeded 1 million units 50 days after its launch. Tencent Mobile Phone Market Insight data shows that from October 5 to October 24, the maximum weekly sales of Pura X View was close to 100,000 units, ranking first in the sales volume of domestic flagship mobile phones in the 5000-yuan price range.
Obviously, the successful experience of products such as iPhone Duo and Huawei Pura X View shows that the market downturn does not mean that new demand has completely disappeared. Relying on product innovation that is more close to user needs, manufacturers still have the opportunity to attract consumers' attention.
All in all, Wang Teng's suggestion to "suspend the release of new phones" explains the current cost dilemma of mobile phone manufacturers, but it also leaves a more difficult question -- reducing the number of new phones can reduce investment, but where do sales volume and users come from?
The mobile phone industry has long relied on scale to share R&D investment, maintain channel operation, and strive for supply chain bargaining power. Rising memory prices put this business model under pressure. Low-profit models cannot digest costs, and actively reducing products may weaken the scale advantage. For manufacturers, it is easy to cut a product line, but it is much more difficult to judge whether it is redundant investment or an important fulcrum to maintain the basic sales volume.
This is also the reason why the early performance of new-form products is worth studying. Users may still change their phones for more suitable screens, more convenient operations and new usage scenarios, but manufacturers need to bear the costs of R&D, adaptation and market verification. The higher the cost, the easier it is for enterprises to concentrate resources on main models with higher certainty, and niche demands and new product exploration may lose opportunities as a result.
After the ebb of the sea-of-phones strategy, the mobile phone market may become more efficient, or it may become more conservative. What really tests leading manufacturers next is whether they can continue to take the risk of creating new demand while cutting inefficient models.
Protecting profits is the survival foundation of this round of cycle. Only by creating sufficiently attractive reasons for users to change their phones can manufacturers have the opportunity to seize the next round of growth.
This article is from WeChat Official Account "Farsight Reef Watch", written by the Farsight Reef Team, and authorized for release by 36Kr.