The new energy vehicle sales figures for October have been released. BYD is sprinting to hit a monthly sales volume of 500,000 units, while Xiaomi and Xpeng are seeing skyrocketing sales growth.
November has arrived, and it is the time for new energy vehicle enterprises to release their October delivery/sales data.
Following the pattern of previous years, October is the second month of the "Golden September, Silver October" in the auto market, which is also the peak season for vehicle sales. However, against the backdrop of the overall decline in total sales of this year's automotive market, the September auto market was not as lively as in previous years. Although the total sales volume rebounded compared with the previous months, it still dropped significantly year-on-year.
So what will the sales performance of various new energy vehicle enterprises be in October, can they maintain the "Silver October" sales performance of previous years? Today, EV Insight (ID: dianchetong233) will take you through the relevant data together.
Strong Performance of New EV Makers: Leapmotor Sustains Monthly Deliveries Over 100,000 Units, Xiaomi and XPeng See Surge
The top seller among new EV brands in October is no suspense, still Leapmotor, with monthly deliveries reaching 106,127 units, a slight increase from 105,656 units in September.
Although the growth rate of Leapmotor's October deliveries has narrowed compared with September, from the perspective of EV Insight (ID: dianchetong233), Leapmotor has now entered a stage of stable development. Slight fluctuations (rise or fall) in monthly deliveries are normal performance. As long as Leapmotor can steadily maintain monthly deliveries above 100,000 units on a regular basis, it will always stay far ahead of other new EV makers in sales performance and firmly hold the throne of top seller among new EV brands.
After Leapmotor, the delivery performance of Xiaomi and XPeng in October is also very impressive. In September, the two carmakers both broke through the 40,000-unit delivery mark, and in October, the two companies simultaneously entered the "50,000-unit Club" with a very obvious growth momentum.
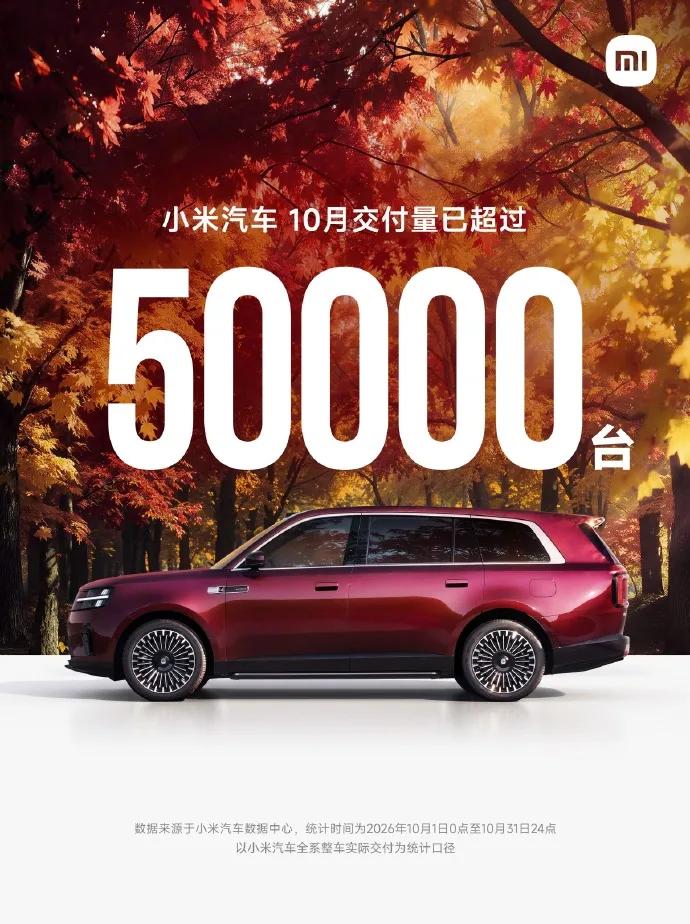
First is Xiaomi, which still did not disclose the exact delivery number, only announcing that its October deliveries reached 50,000+ units. Compared with the 40,000+ deliveries in September, Xiaomi achieved a growth of about 10,000 units in October. The reason for Xiaomi's rapid delivery growth is obviously the stable delivery of its Pengcheng series, which drives the sales increase.
(Image source: Xiaomi Auto)
However, it should be noted that Xiaomi Auto set its annual delivery target at 550,000 units at the beginning of this year. According to public information, its cumulative sales from January to September was 286,475 units. Even with the 50,000+ deliveries in October, there is still a gap of about 200,000 units to reach its target. Judging from Xiaomi's current sales performance, it is obviously impossible to complete the 200,000-unit delivery in the remaining two months of this year, and Xiaomi Auto's annual target is most likely not to be achieved this year.
Nevertheless, as an automotive brand with only 5 years of car-making history, it is very worthy of recognition to achieve monthly sales of more than 50,000 units. It remains to be seen whether Xiaomi can make new history and further increase its delivery volume in the remaining two months of this year.
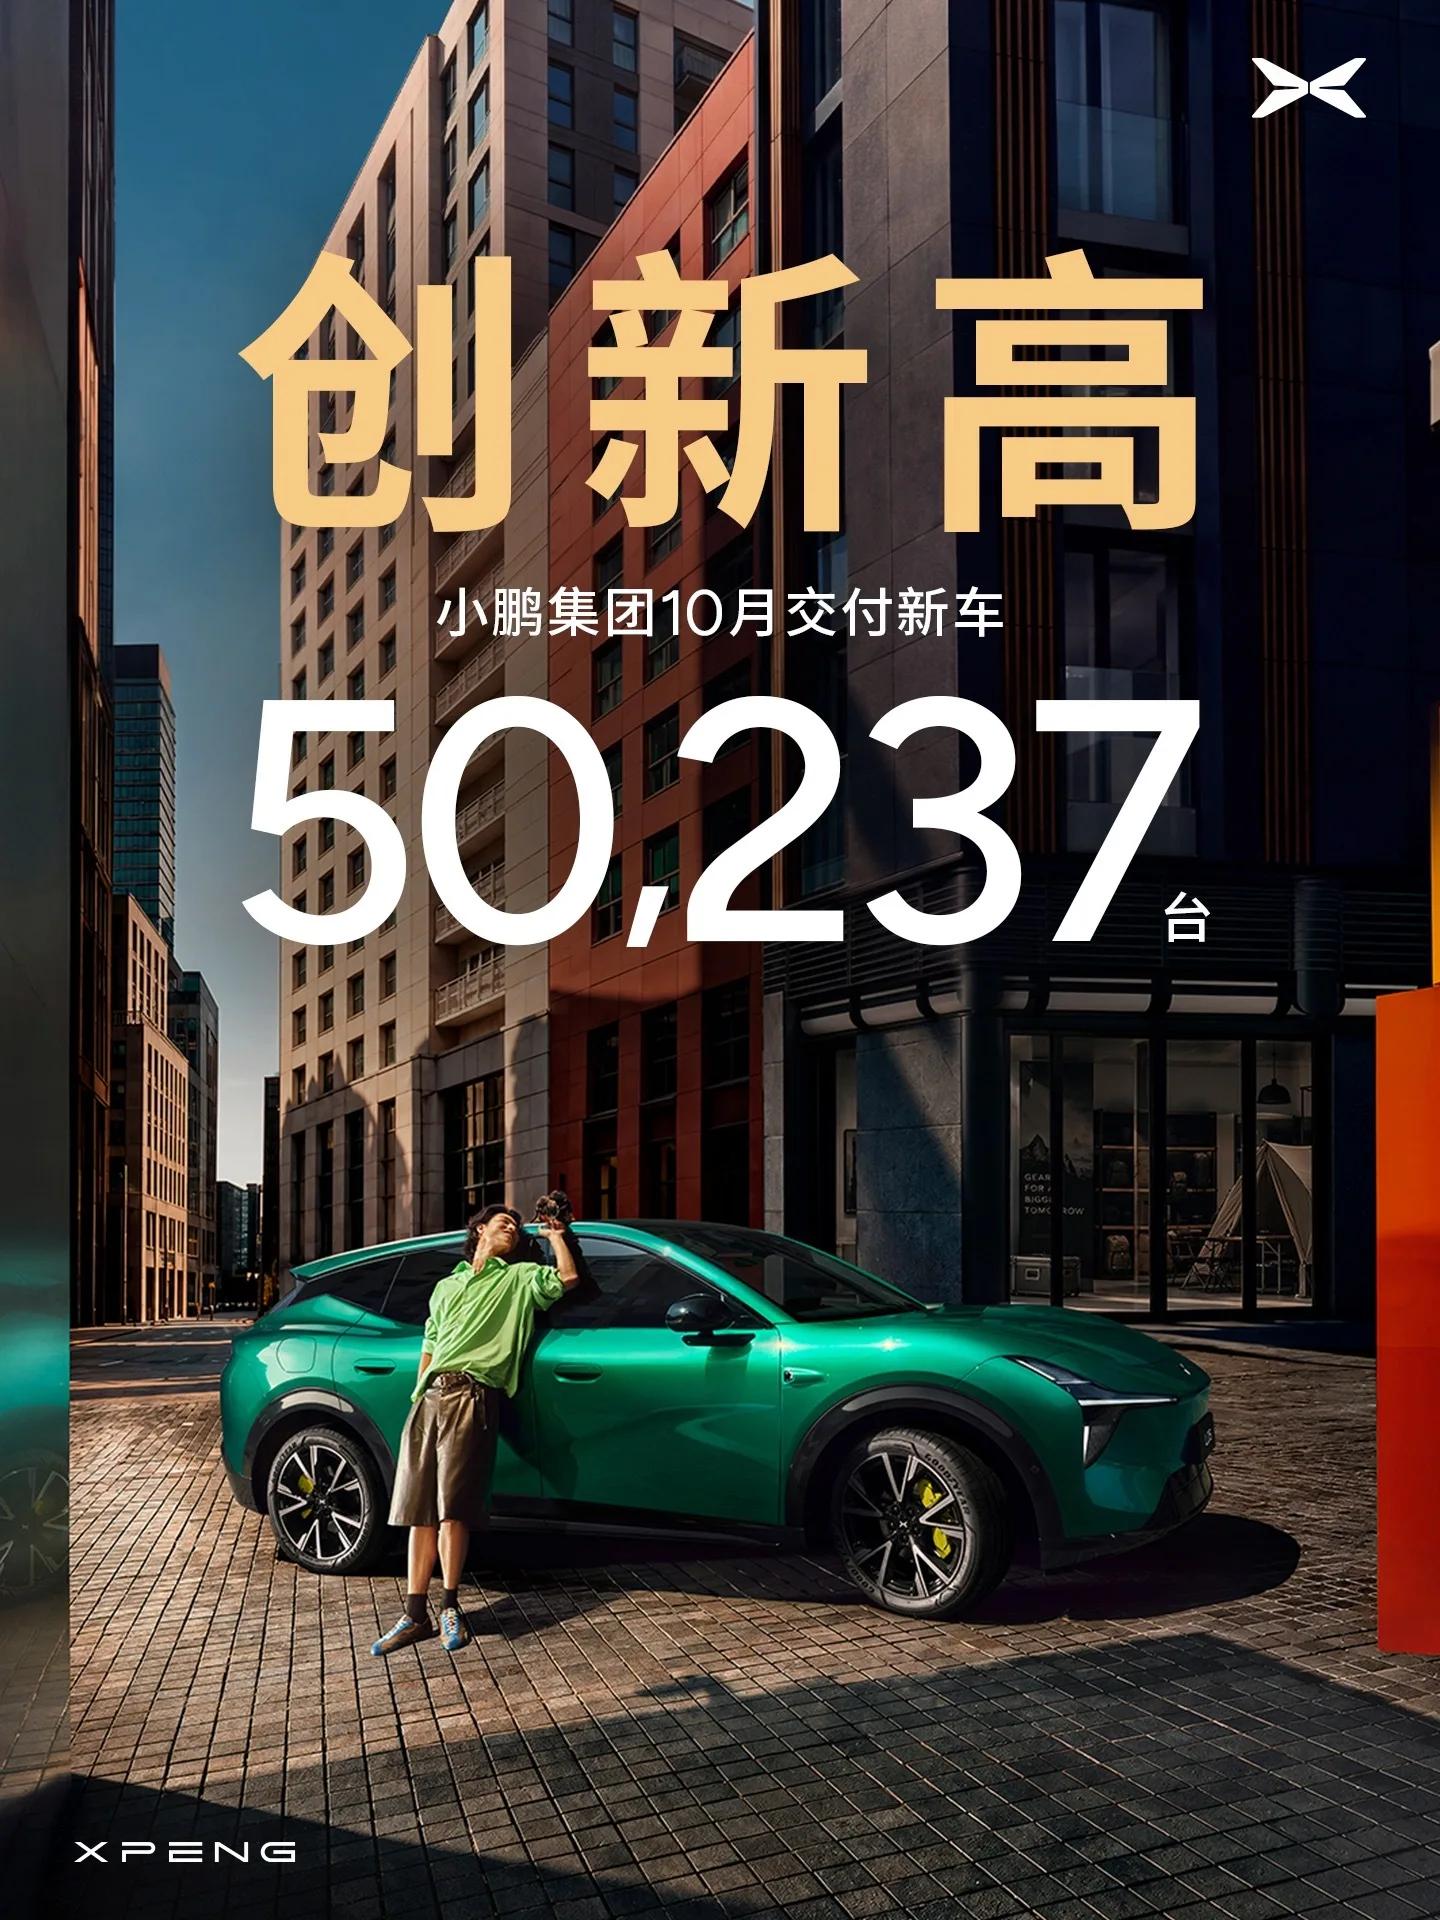
Next is XPeng, whose October deliveries reached 50,237 units, an increase of nearly 9,000 units compared with September, setting its highest monthly delivery record in history.
(Image source: XPeng)
In the report of XPeng MONA L05 launch event a few days ago, EV Insight (ID: dianchetong233) mentioned that XPeng has achieved success in both the mainstream market and the high-end flagship market this year, and XPeng's outstanding delivery performance in October has once again confirmed this view.
Starting from November 1, XPeng MONA L05 has been officially delivered. What kind of sales increment can this model bring to XPeng? Will XPeng's monthly delivery in November hit a new high? EV Insight (ID: dianchetong233) is also looking forward to it.
The fact that both XPeng and Xiaomi's deliveries exceeded the 50,000-unit mark made the "40,000-unit Club" empty in October, and the brands with monthly deliveries exceeding 30,000 units are NIO and HarmonyOS Intelligent Mobility.
First look at NIO, the company's October deliveries reached 34,246 units, a slight decline compared with September. Among them, NIO brand accounted for 18,125 units, Le Dao 8,383 units, Firefly 7,738 units. Compared with September, NIO brand's sales in October declined to a certain extent, while the other two brands remained stable.
It is worth mentioning that NIO has no new car launch plan this year, and the company's current priority is to sell its existing models well, so NIO's monthly deliveries will not change significantly at this stage. However, NIO still has obvious room for growth at present. For example, the Le Dao brand, which targets the mainstream market and family car scenarios, still has considerable growth potential. We expect NIO to continue to make efforts and bring further sales growth across all price segments.
The deliveries of HarmonyOS Intelligent Mobility also declined to a certain extent compared with September, reaching 33,537 units. Against the background that the facelifted AITO M8 has not been officially launched and the Zunjie brand is continuously affected by negative public opinions, HarmonyOS Intelligent Mobility can still achieve monthly deliveries of more than 30,000 units, which reflects consumers' recognition of the brand and also demonstrates the brand's resilience.
Li Auto's October deliveries reached 29,025 units, which also declined to a certain extent compared with September. However, Li Auto was in the stage of switching many models to self-developed batteries in October, and its main mass-market model i6 also underwent facelift that month, so the sales decline is predictable. It is believed that with the completion of production capacity ramp-up of multiple models equipped with self-developed batteries, Li Auto's deliveries will return to the 30,000-unit level.
Traditional Carmakers Achieve Month-on-Month Growth, Sub-brands Accelerate Electrification Transformation
The sales performance of traditional brands in October is also relatively impressive. Although affected by the overall decline of the industry, some carmakers saw a certain year-on-year drop compared with the same period of previous years, many carmakers achieved month-on-month growth when compared with September data. Even BYD and Geely achieved year-on-year growth.
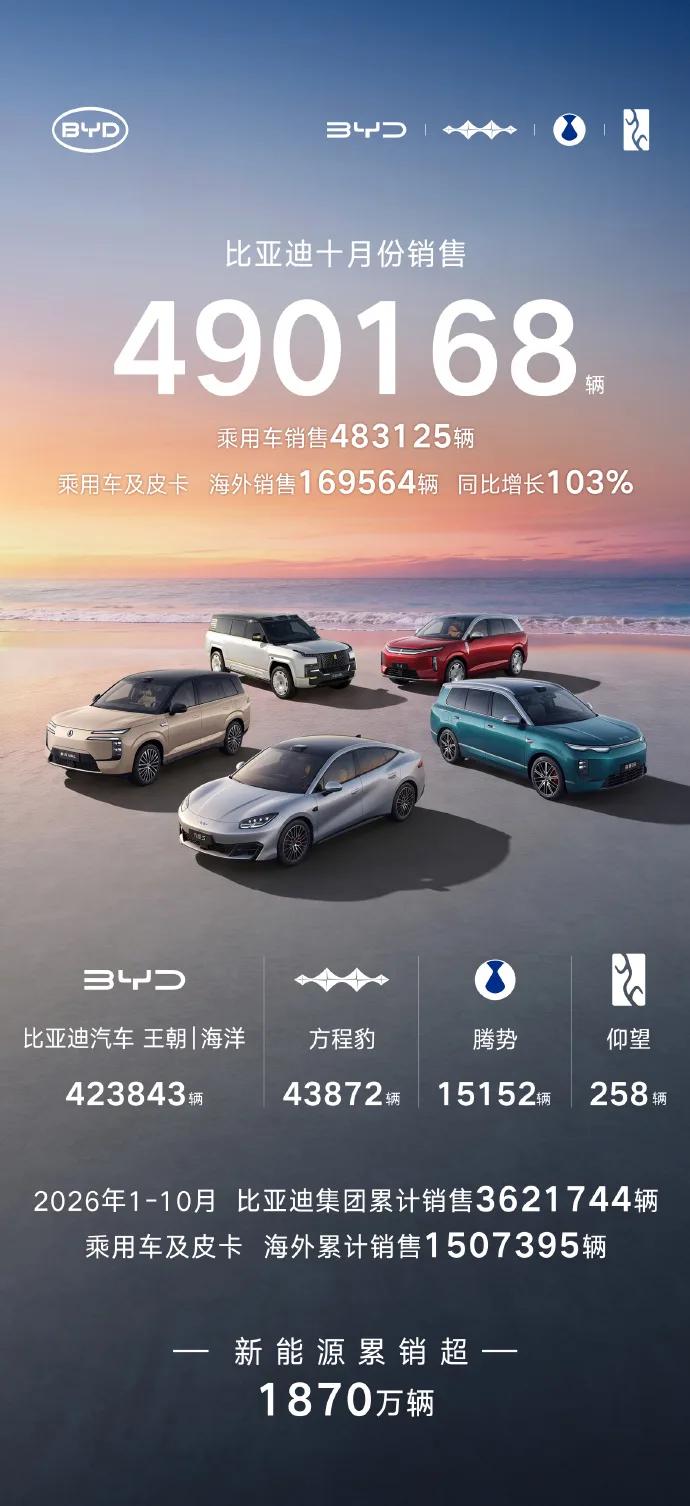
First look at BYD, its total sales in October reached 490,168 units, of which passenger vehicle sales were 483,125 units, and overseas sales of passenger vehicles and pickup trucks reached 169,564 units. Its total sales increased significantly compared with September, but did not break through the 500,000-unit mark for the time being, and its export sales declined slightly compared with September.
Specifically for each sub-brand, the sales of Dynasty + Ocean series reached 423,843 units, Fangchengbao 43,872 units, Denza 15,152 units, and Yangwang 258 units.
(Image source: BYD)
The sales performance of Dynasty + Ocean series in October remains strong. With the supply of second-generation Blade Battery gradually becoming sufficient and more new cars, facelifted and updated models being released, the two brands are bound to achieve higher sales. It is worth mentioning that Dynasty Network and Ocean Network have launched three brand new/updated models in October, namely the new Han, the second-generation Seagull, and the third-generation Qin PLUS. The second-generation Seal 07 and the third-generation Tang will be launched in November. In the remaining two months of this year, the sales of Dynasty Network and Ocean Network are expected to continue to grow.
As for Fangchengbao, its sales performance is basically the same as that in September. At present, the Fangchengbao S is still in the production capacity ramp-up stage, and it is believed that after the production capacity problem is solved, Fangchengbao's sales will see a significant improvement. Denza's sales declined, and we expect the launch of N8 to reverse this situation.
SAIC Motor's total sales in October exceeded 430,000 units, but the group did not release the specific October data of its self-owned brands. Its new energy vehicle sales in October reached 258,600 units, a year-on-year increase of 25.12%. Its sub-brand MG has separately announced its sales data: global new energy sales exceeded 85,000 units, and domestic sales exceeded 31,000 units.
It can be seen that with the launch of models such as MG4 and MG 07, MG brand's sales performance is growing steadily, and its presence in the domestic new energy market is also gradually increasing.
Geely Auto Group's October sales reached 310,183 units, also achieving a slight increase compared with September. Among them, new energy vehicle sales reached 214,996 units, including 140,758 pure electric vehicles and 74,238 plug-in hybrid vehicles, and export sales reached 107,153 units.
The sales data of each sub-brand are as follows: Geely Galaxy 153,385 units, Lynk & Co 21,958 units, Zeekr 32,483 units. The sales of Geely Galaxy and Lynk & Co increased compared with September. Driven by the launch of the new Z20, Lynk & Co's monthly sales exceeded 20,000 units. Zeekr's sales declined slightly, but still maintained a level above 30,000 units. As Geely's high-end brand, Zeekr still plays a benchmark role.
Great Wall's October sales reached 120,374 units, also achieving a slight increase compared with September. Among them, new energy sales reached 49,499 units, and overseas sales reached 62,862 units.
Driven by the launch of the 2027 ORA Good Cat, both the sales of ORA brand and the new energy sales of Great Wall increased in October, and the sales of ORA brand reached 12,187 units.
At present, Great Wall's momentum of promoting electrification transformation remains unabated. In recent months, it has also completed the annual model update of ORA 5 and ORA Good Cat. However, the main reason for Great Wall's sluggish total sales and new energy sales is that its mass-market targeted models fail to achieve expected high sales and cannot compete with other traditional brands and new EV makers, so there is still huge potential to be tapped in terms of sales. But Great Wall is also carrying out transformation and adjustment step by step, and it is believed that its qualitative change will be seen one day.
As of the completion of this article, the total sales data of large groups such as Changan, Chery and GAC have not been released, but the new energy brands under some large enterprise groups have announced their sales data.
Changan Qiyuan and Changan Deepal under Changan recorded October sales of 63,648 units and 32,642 units respectively, and the sum of the sales of the two sub-brands is very close to the 100,000-unit level.
The sales of GAC Aion Hyper BU reached 42,357 units. As Aion is transforming from B-end to C-end, its sales performance has rebounded to a certain extent. Aion Ray7 will also be officially launched in November. It remains to be seen whether this new car positioned for young and sporty users can further accelerate Aion's transformation to the C-end market.
Closing Remarks
The delivery/sales data of various carmakers in October this year is really quite interesting.
The deliveries/sales of many carmakers increased significantly compared with September, which did not follow the usual "Golden September, Silver October" pattern of previous years, showing us the brand new changes brought by electrification transformation to the market.
There are only the last two months left this year, which is the time for many carmakers to sprint for year-end sales. Which carmakers will achieve sales growth in these two months, and which ones will remain unknown? We will continue the discussion at the beginning of next month and the beginning of next year.
This article is from "EV Insight", authorized for release by 36Kr.