After parting ways with Huawei, Seres has suffered another loss.
Seres released its first financial report after announcing the adjustment of AITO's cooperation division of labor with Huawei.
On the evening of October 30, Seres' released financial report showed that its operating revenue in the third quarter reached 28.08 billion yuan, down 41.7% year-on-year; net profit attributable to shareholders was 1.42 billion yuan, a significant improvement compared with the loss of about 2.471 billion yuan in the second quarter. However, after deducting non-recurring gains and losses, the company still recorded a loss of 1.37 billion yuan.
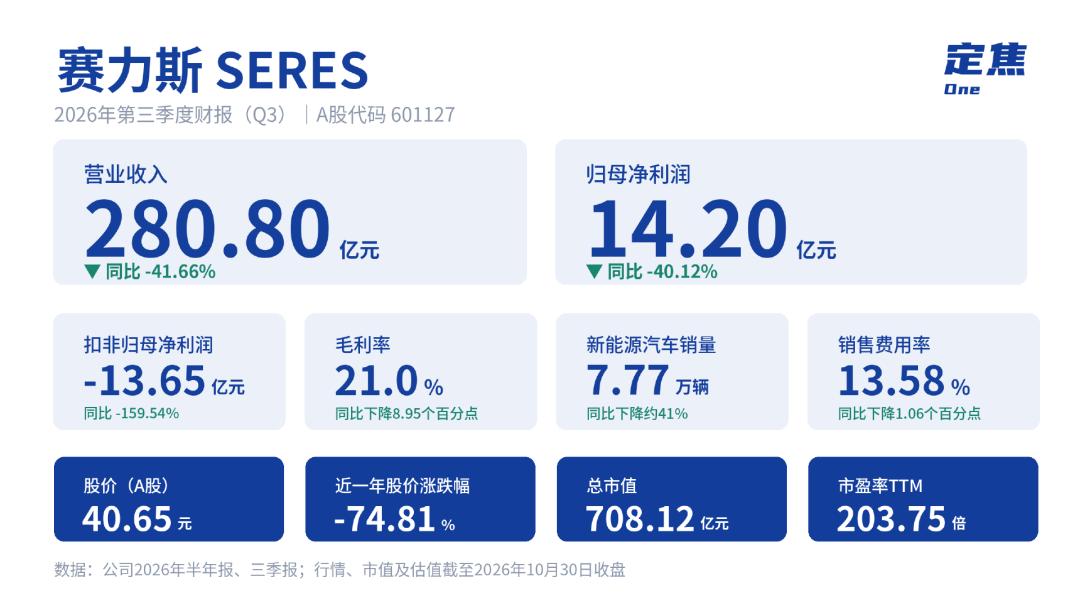
There is a 2.8 billion yuan difference between the two statistical calibers. The bulk of the gap comes from a 2.61 billion yuan "gain or loss from disposal of non-current assets", and the government subsidy included in non-recurring gains and losses is 250 million yuan. This profit is mainly related to the fact that Saidou Technology is no longer consolidated into the financial statement. In July this year, Saidou Technology (formerly Lantian) completed capital increase and share expansion, Seres' shareholding dropped to about 32.96%, it handed over control, the remaining equity is accounted for under the equity method, and the difference remeasured at fair value is included in the current profit and loss at one time.
Seres is divesting inefficient assets, focusing resources on the AITO brand, and covering the loss of its main business with the proceeds from this asset disposal to achieve book profit for the current quarter.
The capital market's expectations for Seres have dropped significantly over the past year.
A year ago, it was one of the most watched automobile companies on the A-share market, with a share price of 162.94 yuan at that time and a market value of nearly 300 billion yuan at one point. On October 30 this year, its share price had dropped to 40.65 yuan, with a total market value of about 70.8 billion yuan, down 75% in a year.
While the share price fell, the cooperation mode between Seres and Huawei was also adjusted. On September 15, HarmonyOS Intelligent Mobility and AITO announced that Seres will take the lead in AITO's product definition, design, brand marketing, channel retail and service system, and Huawei Terminal will participate to empower the business. Yu Chengdong later made it clear that the new AITO models to be launched in 2026 will still be led by the Huawei team in design, and the official switch of leading right will not take place until January 1, 2027. On September 30, the two sides signed a new five-year cooperation agreement and will set up a dedicated team for the AITO business.
Therefore, this third-quarter report mainly reflects the operating conditions before the full switch of the new division of labor. What the market wants to know is nothing more than two aspects: whether the profit structure has improved, and whether Seres' own operation ability can stand the test.
01. Why are cars sold at higher prices but still not profitable?
After deducting this one-off gain, why is the main business still loss-making? Breaking it down to per vehicle will be more intuitive.
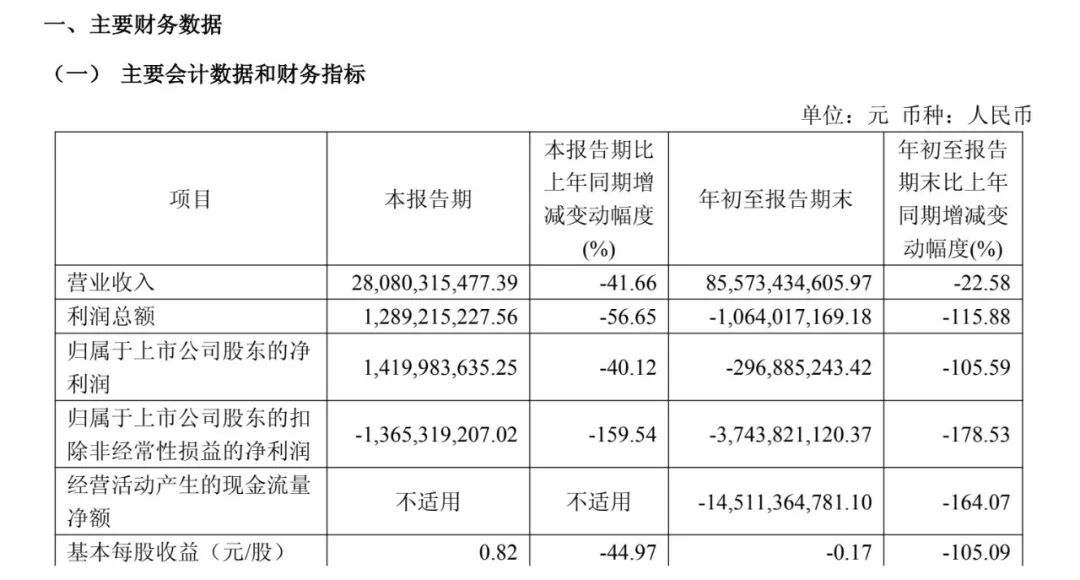
Key financial indicators Source / Seres third-quarter financial report
Let's calculate the per-vehicle revenue first. Seres did not separately disclose the revenue of its automotive business in the third-quarter report, only the consolidated revenue of 28.08 billion yuan. Dividing it by the sales volume of 77,700 new energy vehicles, a rough calculation shows that the per-vehicle revenue is about 360,000 yuan, more than 40,000 yuan higher than the about 317,000 yuan in the second quarter.
The rise of average price may be related to the increase in the proportion of high-priced models. The product launch rhythm supports this point. M9 Ultimate started delivery in mid-September, and the brand-new generation M9 continues to ramp up production, so more expensive vehicles are sold.
In the third quarter, Seres Automobile (AITO series) sold about 66,500 units, down 46% year-on-year; the decline of the entire new energy sector (about 77,700 units) was slightly smaller, at 41%. Among them, M9 sales remained at around 30,000 units, indicating that other relatively low-priced models declined rapidly. The M8 and facelifted M7 that drove sales last year have entered the late stage of the product cycle, M6 is still in the ramp-up phase, and the new M8 will not be available until November. Expensive models did not see sales drop, while cheap models cannot be sold, so the average price is raised in this way.
Cars are sold at higher prices, but no profit is made. The non-recurring profit and loss caliber profit was 2.29 billion yuan in the third quarter of last year, and it turned into a loss of 1.37 billion yuan one year later, with a difference of 3.6 billion yuan before and after.
Continue to calculate the per-vehicle account to see where the money is spent.
The gross profit per vehicle is about 76,000 yuan, then after deducting about 49,000 yuan of sales expenses per vehicle, about 25,000 yuan of R&D expenses, and about 12,000 yuan of management expenses, the book value has turned negative. A car sold for 360,000 yuan is no longer profitable before other expenses are counted.
Why did gross profit decline? The gross profit margin in the third quarter was only 21%, about 9 percentage points lower than the same period last year. There are two reasons: rising costs and declining scale.
First look at the cost. This round of price increases in 2026 is industry-wide. Automotive-grade storage chips rose by about 180% from March to June, and lithium carbonate surged all the way from 75,000 yuan per ton to more than 200,000 yuan per ton. Seres sells high-level intelligent driving vehicles, equipped with lidar, high-computing power platform and multi-screen cockpit. The consumption of storage chips in high-level intelligent driving vehicles is 4 to 8 times that of ordinary entry-level models, so the impact of price increase is naturally more severe.
In terms of scale, the overall sales volume dropped by 40%, while costs such as factory depreciation are relatively fixed. When allocated to fewer vehicles, the per-vehicle cost is raised.
Then the loss was 2.48 billion yuan in the second quarter and 1.37 billion yuan in the third quarter, how was this loss reduction achieved?
Nearly 1.8 billion yuan of asset impairment was accrued in the second quarter, which is equivalent to recording the loss that part of the assets are no longer worth the original amount into the account, so the loss in the current quarter was magnified. In the third quarter, such losses dropped to about 90 million yuan, and expenses were also reduced, so the book loss naturally decreased somewhat. In other words, the loss reduction in the third quarter is due to the concentrated loss recognition in the previous quarter, and the profit from car sales itself has not recovered significantly.
02. Halved sales expenses do not mean the new model is more efficient
Reduced impairment accrual is only a one-off event, and gross profit margin cannot be improved in the short term. Is there any improvement on the expense side?
It seems that there is. Sales expenses in the third quarter were 3.81 billion yuan, compared with 7.05 billion yuan in the same period last year, down about 46% year-on-year, almost halved.
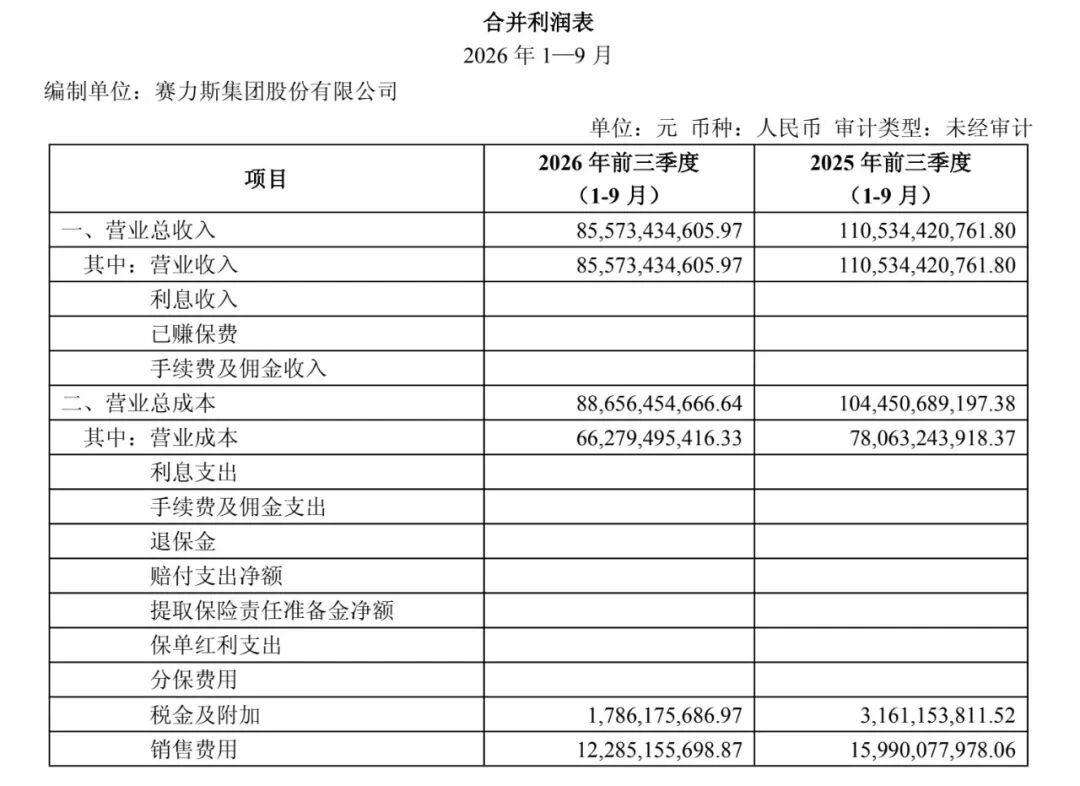
Consolidated income statement, revenue, cost and sales expenses
Source / Seres third-quarter financial report
But the conclusion changes when looking at the expense ratio. Revenue in the third quarter of last year was 48.13 billion yuan, with a sales expense ratio of 14.6%; revenue in the third quarter of this year was 28.08 billion yuan, with a sales expense ratio of 13.6%. The absolute amount of expenses has been reduced by half, but the expense ratio has only decreased by 1 percentage point. This is not enough to prove that the expense efficiency has been greatly improved, and it may just be that the revenue scale has shrunk, and the expenses have shrunk accordingly.
The high expenses in the third quarter of last year were also related to the product cycle. At that time, new cars such as the facelifted new M7 were launched intensively, and promotions, channel construction and marketing investment pushed sales expenses to a high level of 7 billion yuan. In the third quarter of this year, there were fewer new cars and less marketing investment, so expenses naturally came down.
During this period, on September 15, Seres and Huawei just announced the adjustment of AITO's cooperation division of labor. Many people interpreted this decline as a signal: the new model began to take effect, and Seres saved money by managing the channels on its own.
This judgment is untenable for two reasons.
First of all, expenses and revenue declined synchronously. Revenue fell by 41.7%, and expenses fell by about 46%. This is the result of scale decline, not efficiency improvement.
More critically, the official switch of leading right will not take place until 2027, and we are still in the transition period now.
Whether the new model can reduce expenses in the end depends on channel service fees. Under the old smart selection cooperation model, according to the framework of Seres' Hong Kong stock prospectus and calculations by multiple media: Seres pays 8% of the vehicle selling price to Huawei Terminal BG as channel marketing service fee, and pays another 2% of the vehicle selling price to Yinwang Intelligent as technology licensing fee. Roughly calculated based on the average vehicle price of 360,000 yuan, the channel service fee for one vehicle alone is nearly 30,000 yuan.
As for taking back the leading right, it is an opportunity, but it also comes with a price.
An investor who follows Seres said that if channels and marketing are arranged by the company itself, there is room for per-vehicle profit to increase. But in the past five years, Seres exchanged profits for scale, and gave part of the profits to Huawei; when sales grew fast, this set of tactics worked, but once growth slowed down, the pressure increased significantly.
A large part of AITO's brand premium comes from the ecological endorsement of "Huawei" and HarmonyOS Intelligent Mobility. Taking back the leading right means taking over the burden of brand marketing as well. On the day the news was announced on September 15, Seres' share price fell by 5.09%, and the market obviously did not regard this as a pure positive signal.
So it is too early to draw a conclusion on whether the new model will succeed. We need to see whether the sales expense ratio can really go down after 2027; after the channels are transferred to Seres, whether the same marketing investment can bring back the same sales volume and brand premium.
This article is from the WeChat Official Account "Dingjiao" (ID: dingjiaoone), written by JIN Yufan, authorized for release by 36Kr.