Metax has become an LP.
See you again, Muxi.
It is learned from PE Daily - Decoding LP that Shanghai Fuxi Huiqi Venture Capital Fund Partnership (Limited Partnership) was established recently, with a capital contribution of about 200 million yuan, and its business scope includes venture capital (limited to investment in unlisted enterprises).
Through equity penetration, Muxi Co., Ltd. and Futeng Capital under Shanghai State-owned Investment Group are found behind this fund. In other words, Muxi has joined hands with Shanghai state-owned assets to set up a fund.
Looking from this case, a number of industry giants including Muxi, Zhipu AI, GigaDevice, CATL, Andon Health, CXMT and many others are feeding back to the primary market, becoming a rare fresh force in the venture capital ecosystem.
Muxi Teams Up with Shanghai State-owned Assets to Set Up a Fund
More details have emerged.
According to Tianyancha, Shanghai Fuxi Huiqi Venture Capital Fund Partnership (Limited Partnership) (hereinafter referred to as Fuxi Huiqi Fund) was established on October 13 this year, and is jointly held by Shanghai Yulan Business Consulting, Muxi Digital Intelligence (Shanghai) Technology Co., Ltd. (hereinafter referred to as Muxi Digital Intelligence), Shanghai Jiarong Investment Management, Shanghai Wan'ang Investment Management and other entities. Among them, Muxi Digital Intelligence is a wholly-owned subsidiary of Muxi Co., Ltd.
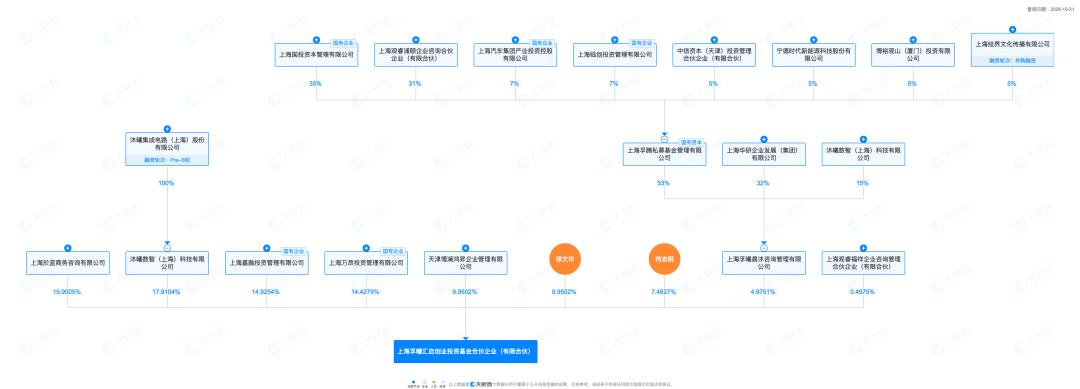
Equity structure penetration shows that the general partner of this fund is Shanghai Fuxi Chenmu Consulting Management Co., Ltd., whose controlling shareholder is Shanghai Futeng Private Equity Management Co., Ltd. (hereinafter referred to as Futeng Capital).
In short, this is a fund jointly funded and established by Muxi in partnership with Shanghai state-owned assets.
The venture capital circle is quite familiar with Futeng Capital, which is also an early investor of Muxi Co., Ltd.
Founded in January 2022, Futeng Capital was mainly initiated by Shanghai State-owned Assets Investment Co., Ltd., and jointly established together with Lingang Group, SAIC Motor, CATL, Bilibili and other entities. At present, its assets under management exceed 44 billion yuan, with total external investment exceeding 25 billion yuan, and it has invested in a number of star hard technology enterprises including Muxi Co., Ltd., MiniMax, JCET, Enflame Technology, Swaying Semiconductor, Brillian, etc.
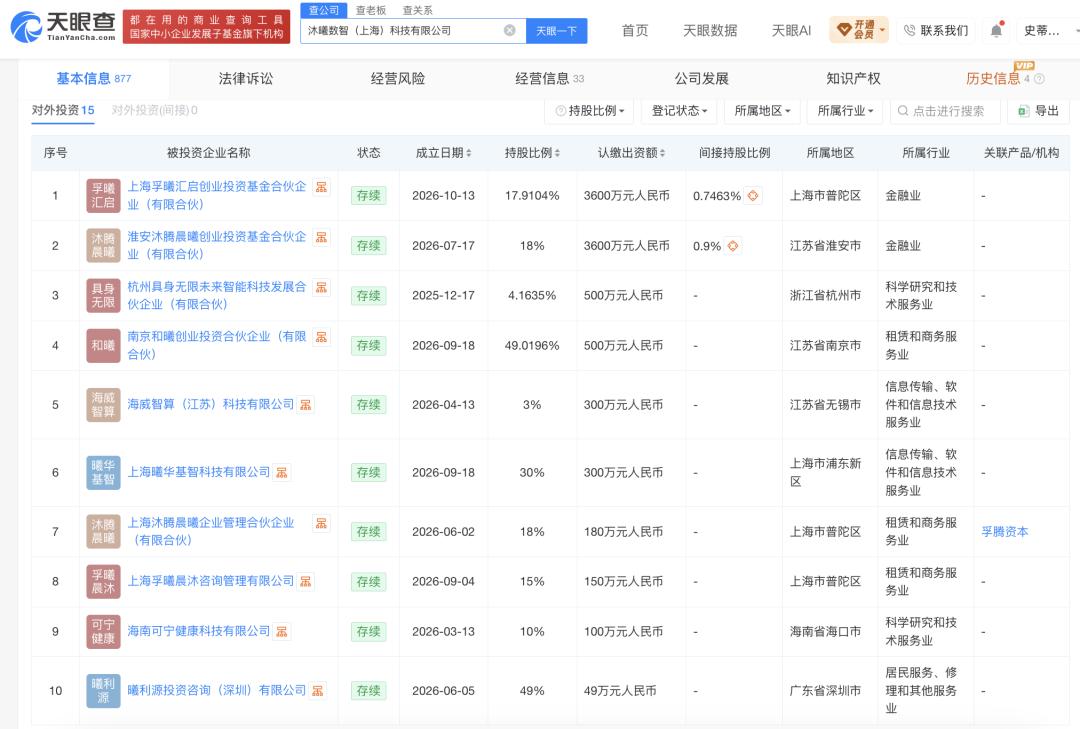
In fact, this is already the second collaboration between the two sides. As early as the middle of this year, Muxi Digital Intelligence subscribed 36 million yuan for Huai'an Muteng Chenxi Venture Capital Fund Partnership (Limited Partnership), and Futeng Capital also stands behind this entity.
Looking back to last December, Muxi Co., Ltd. was officially listed on the Sci-Tech Innovation Board, with the latest market value exceeding 180 billion yuan. After IPO, Muxi's role began to change subtly — it allocates funds to make layout along the computing power industry chain with the help of the fund's network.
Its wholly-owned subsidiary Muxi Digital Intelligence has become an important starting point. According to Tianyancha, Muxi Digital Intelligence was established in January 2026, with Chen Weiliang as the legal representative and actual controller, and it has invested in more than ten enterprises externally.
In addition to Futeng Capital, Muxi Digital Intelligence also established Nanjing Hexi Venture Capital Partnership (Limited Partnership) in September this year together with Heli Venture Capital Management (Suzhou) Co., Ltd. under Heli Capital, to carry out investment activities with its own funds. At the same time, Muxi Digital Intelligence has also made frequent direct investments, backing multiple technology projects including Daxiao Robotics, Muchuang Integrated Circuit, Qimen Power, Orient Computing, Zeno Robotics and others.
From starting a business, going public, acting as an LP to directly investing in technology projects, Muxi is becoming increasingly active in the venture capital circle, and an investment territory spread along the computing power industry chain has taken shape quietly.
Fresh Capital Source
A number of technology companies that were heavily invested by investors in the past are gradually taking seats as LPs, becoming a new source of fresh capital for the venture capital market.
Zhipu AI is a typical representative. Not long ago, Zhipu AI participated in the establishment of Zhejiang Zhipu Jiangmen Cognitive Intelligence Venture Capital Partnership with a scale of 1 billion yuan, which mainly invests in artificial intelligence and its upstream and downstream industries. Interestingly, the manager of this fund, Innoangel Fund, participated in Zhipu AI's Series A financing in 2021; other contributors of the fund including Shangcheng Capital and Hangzhou Urban Construction Investment Group were also shareholders of Zhipu AI before.
GigaDevice also joined the trend. In August this year, it contributed 100 million US dollars through its wholly-owned subsidiary to subscribe for shares of a US dollar fund under Yunfeng Fund. This is not its first time to act as an LP, but investing in a US dollar fund is not common in its investment history.
Insta360 took action even earlier. In June this year, it contributed 100 million yuan through its subsidiary to participate in the establishment of Furuic Fund, focusing on seed-stage and start-up projects in the upstream and downstream of AI and smart hardware. It is worth mentioning that FreeS Fund is exactly one of the early investors of Insta360 — the scene that "you were my investor in the past, and now I become your LP" is happening intensively.
In addition, enterprises including CATL, Andon Health, Zhihu, CXMT, Septwolves, Perfect World and others have successively contributed to industrial funds as LPs, focusing their investment tentacles on new-generation technology tracks such as semiconductors, artificial intelligence, robotics, new energy and so on.
All these scenes outline a new cycle of hard technology venture capital: VC/PEs invest in technology companies one after another, accompanying them to grow and go public. After enterprises gain a firm foothold in the industry, they continuously allocate funds to feed back early-stage innovation forces.
Quietly, industrial capitals with abundant cash flow, built-in scenario and order capabilities are becoming increasingly important players in the fundraising lists of GPs.
In the past few years, US dollar funds have shrunk and pure financial funds have faced difficulties in fundraising, so industrial funds have stepped in timely. Beyond capital, they also bring real product demands, test scenarios, supply chain resources, and even subsequent orders and M&A exit channels for early-stage projects. In the long cycle of hard technology, these resources are often more attractive than pure financial returns.
This is not only a liquidity supplement for the venture capital circle, but also a sign of a mature ecosystem — a number of leading technology industry giants not only reinvest the profits they earned back into the industry, but also pass on their understanding of the industry and awe for the cycle to the next batch of entrepreneurs.
The flow of capital always has far-reaching impacts, and this is exactly the precious fresh force in the current venture capital market.
This article is from the WeChat Official Account "Decoding LP", written by Zhou Jiali, authorized for release by 36Kr.