Sprinting to become "the first publicly listed mobile operation robot enterprise": The true essence of Youibot
On October 16, the official website of the China Securities Regulatory Commission released a filing notice: Hefei Youai Zhihe Robot Co., Ltd. (hereinafter referred to as "Youai Zhihe") plans to issue no more than 49.4778 million ordinary shares for overseas listing to be listed on the Main Board of the Hong Kong Stock Exchange; at the same time, 244 million unlisted domestic shares held by 37 shareholders in total will be converted into overseas listed shares to realize "full circulation".
Youai Zhihe submitted its application as a special technology company under Chapter 18C of the Hong Kong Stock Exchange, with China International Capital Corporation as its sole sponsor. It first submitted its listing application in September 2025 and resubmitted it in March 2026. Now it has cleared the domestic regulatory process, and is only one step away from the listing hearing. If the listing goes smoothly, the title of "the first stock of mobile manipulation robots" will most likely belong to Youai Zhihe.
However, while the filing was approved, doubts surrounding Youai Zhihe also emerged intensively. Generally, there are three main points: first, the company recorded a total net loss of 844 million yuan from 2023 to 2025, and the loss in 2025 did not decrease but increased instead; second, the net cash outflow from operating activities lasted for three consecutive years, and accounts receivable kept growing larger; third, the revenue growth rate dropped from 136.7% to 33.3%, while the proportion of revenue contributed by the top five customers kept rising.
First of all, it should be made clear that all these doubts are based on the public financial statements rather than unfounded speculations. The existence of doubts is a good thing, which can force the market to study the prospectus more carefully. But the problem is that there is another set of data in Youai Zhihe's prospectus that points to a completely opposite direction.
If you only refer to either set of data, the conclusion you draw will be one-sided. The financial statements of Youai Zhihe need to be thoroughly analyzed and then interpreted against the coordinate system of the whole industry.
I. The majority of the loss is "paper loss", and the fundamental business performance is reflected in gross profit
The most significant point among all the doubts is the loss situation.
From 2023 to 2025, the net losses of Youai Zhihe were 260 million yuan, 200 million yuan and 384 million yuan respectively. The net loss in 2025 nearly doubled year on year, and the total accumulated loss in three years reached 844 million yuan. Judging from this set of data alone, the performance does not look good.
However, we need to dig deeper into the profit statement. Of the 384 million yuan net loss in 2025, there is an item called "change in book value of redemption liabilities", amounting to 249 million yuan, accounting for 64.9% of the total loss.
This refers to the shares with special rights issued to primary market investors, which are measured at fair value according to accounting standards. Every time the company's valuation rises, an additional loss will be recognized on the books. This item does not cause any cash outflow, and after the company completes its listing, this part of liabilities will be reclassified into equity, and will no longer affect the profit statement.
In other words, this is an accounting reflection that "the higher the valuation, the larger the loss", which has nothing to do with daily operation. Coupled with the annual share-based payment of about 10 million yuan at the company, the main source of Youai Zhihe's book loss in 2025 is actually not at the operation level at all.
If we switch to the adjusted net loss disclosed by the company, the picture is completely different. From 2023 to 2025, the adjusted net losses of the company were 131 million yuan, 81 million yuan and 106 million yuan respectively, and the adjusted net loss rate narrowed from 122.0% all the way to 31.9% and 31.2%. In three years, the loss corresponding to each yuan of revenue of Youai Zhihe dropped from 1.2 yuan to 0.31 yuan, and the trend of this curve is very clear.
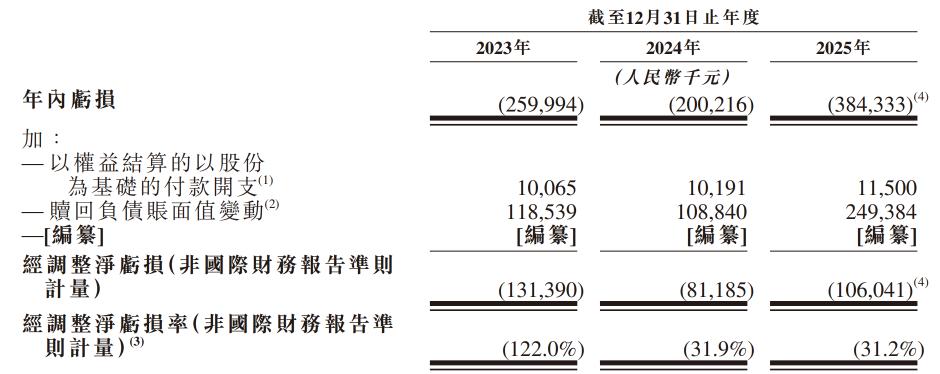
As for the fact that its adjusted loss in 2025 was about 25 million yuan more than that in 2024, the reason is also clearly stated in the prospectus: the company's R&D expenditure was increased from 62 million yuan to 83 million yuan, and the sales expenses also rose as the company expanded overseas markets such as Japan. This is money actively invested by the company, not loss caused by poor business performance.
During the performance recording period, Youai Zhihe's total R&D investment reached 213 million yuan, accounting for 30.3% of its total revenue; 141 R&D personnel account for 33.7% of the total number of employees, with an average working experience of 7.5 years, holding 241 registered patents. Such high investment intensity determines that the company's profit statement at the current stage is not supposed to look very good.
The only question is whether this money is well spent? The gross margin gives the answer.
From 2023 to 2025, Youai Zhihe's gross margin rose from 26.1% to 35.2% and then to 36.5%, with a total increase of 10.4 percentage points; the gross profit increased from 28 million yuan to 124 million yuan, with a compound annual growth rate of 110.2%, outpacing the 77.6% compound annual growth rate of revenue. Among them, the gross margin of the inspection and operation and maintenance solution has risen from 40.3% to 48.1%; the gross margin of the energy and chemical industry solution has risen from 35.6% to over 45%.
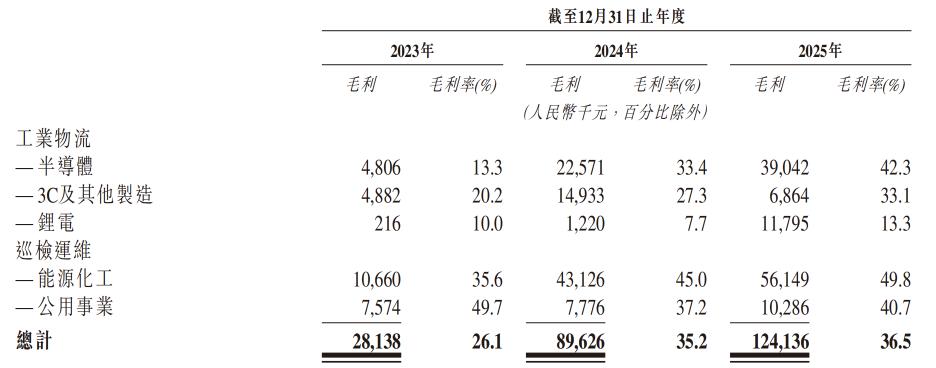
If a company pursues scale expansion at the expense of low prices, its gross margin should decline instead of rising by 10 percentage points in three years. During the same period, the ratio of Youai Zhihe's operating expenses to total revenue was reduced from 161.6% to 72.8%, and the scale effect has begun to show.
Then we look at the situation from the industry perspective. Geekplus (2590.HK), the global leading AMR enterprise, recorded a revenue of 3.171 billion yuan in 2025, which is 9 times that of Youai Zhihe. It also recorded a total accumulated loss of 3.536 billion yuan from 2022 to 2025, and its net loss did not narrow to 10 million yuan until 2025.
In addition, Standard Robots, which is also queuing for Hong Kong stock IPO, recorded a total accumulated loss of 347 million yuan from 2023 to 2025. The expansion of its single-year loss in 2025 also came from a 147 million yuan share-based payment, rather than a sudden deterioration of its operation.
The business model of the robot track is inherently "R&D comes first, profit comes later". The book loss of Youai Zhihe is a common phenomenon in the industry rather than an individual case. When Geekplus was listed in July this year, its Hong Kong public offering was oversubscribed by 133.62 times, which proves that the capital market has already formed a mature pricing logic for this business model.
II. Capital occupation during the expansion period does not mean the loss of payment collection capacity
The second doubt points to the capital situation.
The net cash outflow from Youai Zhihe's operating activities lasted for three consecutive years, reaching 94 million yuan, 80 million yuan and 185 million yuan respectively from 2023 to 2025; trade receivables and notes receivable increased from 51 million yuan to 247 million yuan, and the turnover days extended from 165.9 days to 208.9 days. "The more products sold, the more funds the company advances" is the core of this doubt.
But objectively speaking, this conclusion needs to be corrected.
First of all, let's look at the customers corresponding to the receivables. The downstream customers of Youai Zhihe include semiconductor wafer fabs, large central state-owned energy enterprises and leading lithium battery manufacturers. The company has entered the core production processes of more than ten domestic and foreign wafer fabs, and its energy customers cover the full spectrum of wind power, photovoltaic, hydropower, thermal power, nuclear power, oil and gas.
The common features of such customers are high credit rating and low bad debt risk, but their internal acceptance and payment approval process is very long. The average credit period (including the credit period specified in the original contract) disclosed in the prospectus ranges from 150 days to 270 days. In other words, the long account period has been written into the business model at the moment when the contract is signed, which is the common practice of the To B industrial product industry, rather than the deterioration of Youai Zhihe's payment collection capacity.
The growth rhythm of the receivable balance can also explain this point. At the end of 2025, Youai Zhihe's receivables and notes receivable amounted to 247 million yuan, corresponding to the revenue of 340 million yuan in the same period. The growth rate of receivables is basically synchronized with the expansion of revenue, which belongs to the natural working capital occupation precipitated by business expansion.
The indicator that really deserves attention is whether these customers corresponding to the receivables will make repurchases. In 2025, Youai Zhihe's customer repurchase rate exceeded 70%, among which the repurchase rate of semiconductor industry customers reached 75%, and the repurchase rate of lithium battery industry customers reached 100%. Behind the accounts receivable are leading customers who keep making repeat purchases, so the certainty of recovering this sum of money is far more optimistic than what the book turnover days show.
A horizontal comparison can help us see the position of the company more clearly. For Standard Robots, which is also sprinting for Hong Kong stock listing, its receivable turnover days extended from 144.2 days in 2023 to 272.5 days at the end of April 2026, and the cash on its account was only 50 million yuan at the end of April 2026; while Youai Zhihe's turnover level of 208.9 days is obviously better. At the same time, the company's cash and cash equivalents increased from 76 million yuan at the end of 2023 to 243 million yuan at the end of 2025, and the total amount together with available bank financing reached 427 million yuan, which is at a very high level, so there is no need to worry excessively about liquidity risks.
In addition, Youai Zhihe completed 220 million yuan of equity financing and obtained 210 million yuan of new bank loans in 2025. Under the appearance of negative cash flow from operating activities, the capital market is continuously increasing its investment in the company, and the company's balance sheet is actually getting stronger rather than losing blood.
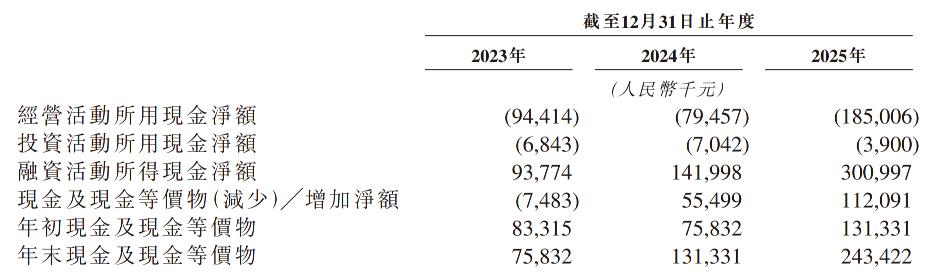
The net cash outflow from operating activities during the expansion period is a common state in the order-driven industrial robot industry, which was also the case for Geekplus before its listing. The key difference lies in whether the cash pool is getting shallower or deeper, and Youai Zhihe is obviously in the latter situation.
III. After the high base period, the growth structure is shifting to a new track
The third doubt targets the growth quality.
Youai Zhihe's revenue growth rate dropped from 136.7% in 2024 to 33.3% in 2025, while the proportion of revenue contributed by the top five customers rose from 28.3% to 35.8%. The slowdown of growth rate combined with the rise of customer concentration is easy to be interpreted as "the growth momentum has peaked, and the company relies on a small number of large customers".
First of all, let's look at the base of the growth rate. The explosive growth of 136.7% in 2024 directly raised the company's revenue base from 108 million yuan in the early stage to 255 million yuan. Based on this base, the 33.3% growth rate in 2025 made the absolute increment of current-period revenue reach 85 million yuan, exceeding 80% of the total annual revenue of 2023.
More importantly, this growth rate has allowed Youai Zhihe to steadily cross the revenue threshold for "commercialized companies" under Chapter 18C. The revenue of 340 million yuan in 2025 has further widened the gap between the company and the threshold line.
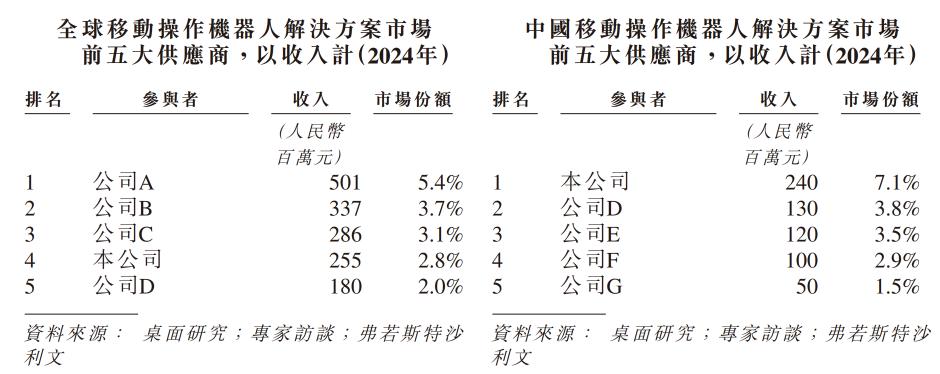
In an emerging track with a global market size of 9.2 billion yuan and only a handful of manufacturers with revenue exceeding 100 million yuan, this volume itself is proof of Youai Zhihe's leading position. Calculated based on the revenue in 2024, Youai Zhihe ranks fourth in the global mobile manipulation robot solution market, and ranks first in the Chinese market with a 7.1% market share; in the caliber of industrial mobile manipulation robot companies, Youai Zhihe ranks first in both the global and Chinese markets.
Then look at the other side of the rising concentration: the customer pool is expanding at the same time.
Data shows that the number of Youai Zhihe's semiconductor industry customers increased from 35 in 2023 to 93 in 2025, and the number of energy and chemical customers increased from 47 to 91. The company now covers more than 400 enterprises in total, and has landed more than 800 industrial projects. The rise in the proportion of its top five customers is essentially the result of increased purchasing volume and deepened repurchase of leading customers, rather than stagnation in the expansion of new customers.
In fact, what deserves more attention than the growth rate figure is the shift of Youai Zhihe's revenue structure. The biggest variable of the company in 2025 came from the lithium battery industry, whose revenue jumped from 16 million yuan in 2024 to 89 million yuan, accounting for 26.1% of the total revenue, and the number of customers doubled from 13 to 27; the revenue of energy and chemical industry increased to 113 million yuan, accounting for more than one third of the total revenue for two consecutive years; the revenue of semiconductor industry reached 92 million yuan, consolidating its fundamental market position. The simultaneous growth of the three vertical tracks means that Youai Zhihe's growth no longer depends on the capital expenditure cycle of a single industry.
