State-owned Capital Players Behind the Embodied AI Frenzy: Scrambling for Projects, Propping Up Favored Enterprises, and Speculating on the Future by Following Official Policy Documents
Author | Huang Nan
Interview | Huang Nan, Qiu Xiaofen
Editor | Yuan Silai
This spring, the regional investment promotion team has become a frequent visitor in the office of FA He Ziyang.
She works at a financial advisory institution serving the hard technology track, and her daily job is to connect embodied startups with investment institutions. On her busiest day, she received four government teams from Tianjin, Shenzhen, Chengdu and Xiamen, most of whom were staff from district-level investment promotion centers, as well as responsible persons from prefecture-level cities.
Some "follower city" investment promotion teams directly told her: "We can't find a clear direction either, we just follow whatever the policy says." Some local teams have unrealistic plans: a county-level city with a population of only hundreds of thousands has profound manufacturing resources. The local side can present a complete local industrial map: ready-made factory buildings, complete supporting facilities, and a large number of small and medium-sized factories in the upstream and downstream sectors. What is missing now is a leading chain owner enterprise to "build up the entire ecosystem".
He Ziyang can feel that they are at a loss, many of them are coerced by some force and have to catch up with a wave they don't quite understand.
For a long time, state-owned capital seemed to be far away from the venture capital market. In the past, the investment feasts of FMCG, entertainment and Internet rose and fell, and the figure of state-owned capital was rarely seen.
However, this is the era of hard technology investment. Relying solely on market-oriented funds, it is difficult to meet higher-level goals. As a result, state-owned capital steps onto the stage. As the most high-profile embodied intelligence track most familiar to ordinary people in the past two years, the participation of state-owned capital is also quite eye-catching.
According to data from IT Juzi, there were more than 300 financing events in China's domestic embodied intelligence track in the first half of 2026, a 137% increase compared with the same period in 2025, and the total disclosed amount of projects reached 935 billion yuan. Among large-scale financing transactions, state-owned capital institutions accounted for 42% of the participants. Joint investment by local state-owned capital, industrial capital and leading VCs has become the mainstream configuration for embodied projects.
From a time perspective, the national team actually entered the market at the end of 2025. Shanghai Embodied Intelligence Fund, Shenzhen Robot Fund Cluster and other funds have been launched one after another and made concentrated investments, becoming one of the most important sources of incremental funds. Outside first-tier cities, robot industry funds in Hangzhou, Suzhou, Hefei, Wuxi, Ningbo, Nanjing and other places have also successively joined this capital competition.
"When the large local fund was established last year, we knew this year would definitely be good, and the facts proved that. Leading companies received rounds of financing at the level of billions or tens of billions of yuan." Liu Kaijie, an investor from a veteran hard technology fund, told Hard Krypton.
For a period of time, investing in embodied intelligence has become an open-book exam that you cannot get wrong. "Everyone is making proposition-style investments. Either invest in Musk, or invest in 'Marx'. It is a consensus that standing with the general direction brings higher certainty." An investor from a state-owned capital fund told Hard Krypton, and this statement was repeated by many interviewees in different ways during our interviews.
Moreover, the "Hefei Model" has set a good example, and no one wants to miss the possibility of making a big profit with a small investment. The hot spots of the embodied intelligence track are constantly changing: first, ontology companies, then upstream components, and finally world models. State-owned capital is never absent in all these segments.
However, the trend took a sharp downturn in September 2026. Unitree's market value halved after listing, the founder of Mechademon posted on Moments denouncing industry chaos, and the Hong Kong Stock Exchange tightened the 18C special technology listing rules.
Investors have gradually recognized an open secret: the IPO expectations of second and third tier enterprises are no longer optimistic. Many interviewed investors told Hard Krypton that the real financing pressure will be released intensively after November 2026. At present, a large number of enterprises still have remaining funds from previous financing on their books, but when the next round of financing starts, the reality of valuation inversion and no exit channels may come at the same time.
This fact directly shakes the exit expectations of local state-owned capital and the industrial investment promotion narrative. "The embodied track changes so fast, with a small iteration every three months, and all previous judgments can be overturned in half a year. The market is in huge confusion." An embodied investor from a regional institution in Shenzhen sighed to Hard Krypton.
Apart from the capital carnival, Unitree is still the world's second largest humanoid robot company by shipment volume, with shipments exceeding 5,000 units in the first half of 2026, and its market value is still double that before listing. However, this brutal market value evaporation has eventually become the starting point for the industry to hit the brakes.
An investor will quote a judgment of "profound changes unseen in a century". The primary market and investment logic are certainly in the midst of drastic changes. We try to use the embodied intelligence industry as an entry point to sort out how state-owned capital comes to the forefront, how it operates, and how it affects the trend of the industry.
State-owned capital enters the market, "spends a thousand gold to buy horse bones"
What exactly can embodied intelligence bring to a region?
When communicating, a state-owned capital investor repeatedly mentions the allusion of "spending a thousand gold to buy horse bones": in the Warring States Period, a monarch was eager to get a thousand-mile horse but failed. His official spent a lot of money to buy a bone of a thousand-mile horse, and told him: this is to tell the people all over the world that you are sincerely seeking thousand-mile horses, so that you would even buy a dead horse, let alone a live one. Less than a year later, the monarch did get three thousand-mile horses.
This logic is still applicable in the primary market 2,000 years later.
For a city that wants to secure a position in the layout of "new quality productive forces" and the 15th Five-Year Plan, the available options are very limited. Commercial aerospace, quantum technology and controlled nuclear fusion are highly dependent on national large-scale facilities, top scientific research talents and special industrial foundations, and only a few cities have the conditions to undertake them. In contrast, the embodied intelligence track has unique advantages, and links such as complete machines, components, software and data can be split and settled in different locations.
This means that what they want may not necessarily be a complete humanoid robot complete machine manufacturer. Even a component company that produces joint motors and reducers, as long as it settles locally, can not only meet the phased investment promotion goals, lay the seeds for tax growth and industrial clusters, but also be sufficient to unfold a grand narrative about the future embodied intelligence ecosystem.
According to Hard Krypton's understanding, some governments do not allow vicious competition between districts, and divide key districts into different concepts and functions: some districts focus on core components, some introduce ontology and brain technologies, some introduce dexterous hands, and each has a clear division of labor.
Some enterprises have seen such demands and adjusted their financing models accordingly. They will study the industrial resources supported by state-owned capital, split their business according to the demands, and locate headquarters, R&D centers, production lines and data centers in different cities to connect with state-owned capital resources in multiple places.
"If the local government lacks complete machines, we promote ontology; if they need components, we focus on motors and reducers; if they want layout and settlement, we build data centers." An investor told Hard Krypton.
For some local state-owned capitals, the most important task is to deliver satisfactory results. By doing so, enterprises can meet their demands in the most cost-effective way. "In fact, they are not necessarily most afraid of projects failing temporarily. Hard technology inherently allows failures, and policies have been emphasizing due diligence and exemption. What they fear most is that there will be no record at all in the files after the project fails."
Therefore, smart companies do not first study customer demands, but the investment promotion gaps of various cities. They sign the base first, get the factory building, buy equipment, then find industrial partners to place a batch of orders, release press releases on time, and attach photos of leaders' inspections. "The materials must form a closed loop first."
As for whether this company can really create value, "it can be studied slowly. In the end, a company that has not made any commercial progress yet has become a core enterprise in the local robot industrial chain in the documents." The above investor concluded, "Everyone thinks they have got the most critical part. In the end, everyone lifts the sedan chair together, and no one is willing to ask first whether there is anyone sitting in the sedan chair."
Differentiation of state-owned capital, one city one policy
To sort out the context of state-owned capital, we first need to understand that China is a unified multi-ethnic country, while there are huge differences between regions. There are complex interweaving between the central government and local governments, and between different local governments, and the bureaucratic system has division of responsibilities across different sectors and multiple leadership structures.
Therefore, the interior of state-owned capital is not a homogeneous capital pool. Different types of state-owned capital have obvious differences in capital sources, assessment mechanisms and risk preferences, and their investment styles are also quite different.
The first type is the capital responsible for the group's industrial chain. Representative institutions are industrial investment platforms under central enterprises, including CITIC series funds, CRRC Capital and so on. These funds have abundant capital, their capital sources include special supporting funds and industrial transfer payments. The focus of assessment is not on the financial multiple of a single project, but on whether it can fill the gaps in the group's own industrial chain and open up new business scenarios.
For example, the CRRC Transformation and Upgrading Fund, which invested in Zhifang, stated directly that it values the "natural ecological synergy" between the two sides. CRRC has high-end manufacturing scenarios, and pays more attention to whether embodied intelligence technology can be embedded into the group's production lines and businesses.
The second type is the capital responsible for local investment promotion assessment. The main bodies are district and county-level state-owned capital platforms and industrial funds, which are also the most active investors in this round of embodied boom. Their funds are constrained by the preservation and appreciation of state-owned assets, with relatively conservative risk preferences, and they prefer mature projects in the mid-to-late stage, with valuations of tens of billions of yuan, close to the PE stage.
For local governments, the core measurement standard for project evaluation is the value of industrial settlement. Wu Jianyu, the person in charge of the regional investment promotion center of a second-tier city, told Hard Krypton: "We care more about whether enterprises can locate their R&D centers, production lines and supporting teams locally, and whether they can drive upstream and downstream component and data service enterprises to form clusters. This is the top priority indicator for capital consideration. The short-term valuation of enterprises and the time to go public are secondary factors."
The third type is market-oriented capital within the state-owned capital system with financial return as the core goal. In recent years, Shenzhen and Shanghai have piloted the classified reform of state-owned capital funds, trying to separate some state-owned capital funds from the positioning of investment promotion tools, and set assessment indicators according to the investment attributes of the funds themselves.
This type of capital does not take local factory construction as a mandatory precondition, and the return investment constraints will also be relaxed. Investment judgment focuses on project growth and exit income. Typical institutions include Toukong Donghai under Shenzhen Investment Holdings, the artificial intelligence terminal industry fund managed by Shenzhen Venture Capital, some sub-funds under Shanghai State-owned Investment, etc. These institutions have all appeared in the investor list of leading embodied intelligence enterprises such as Stardust Intelligence, Agibot, and Independent Variable Robotics.
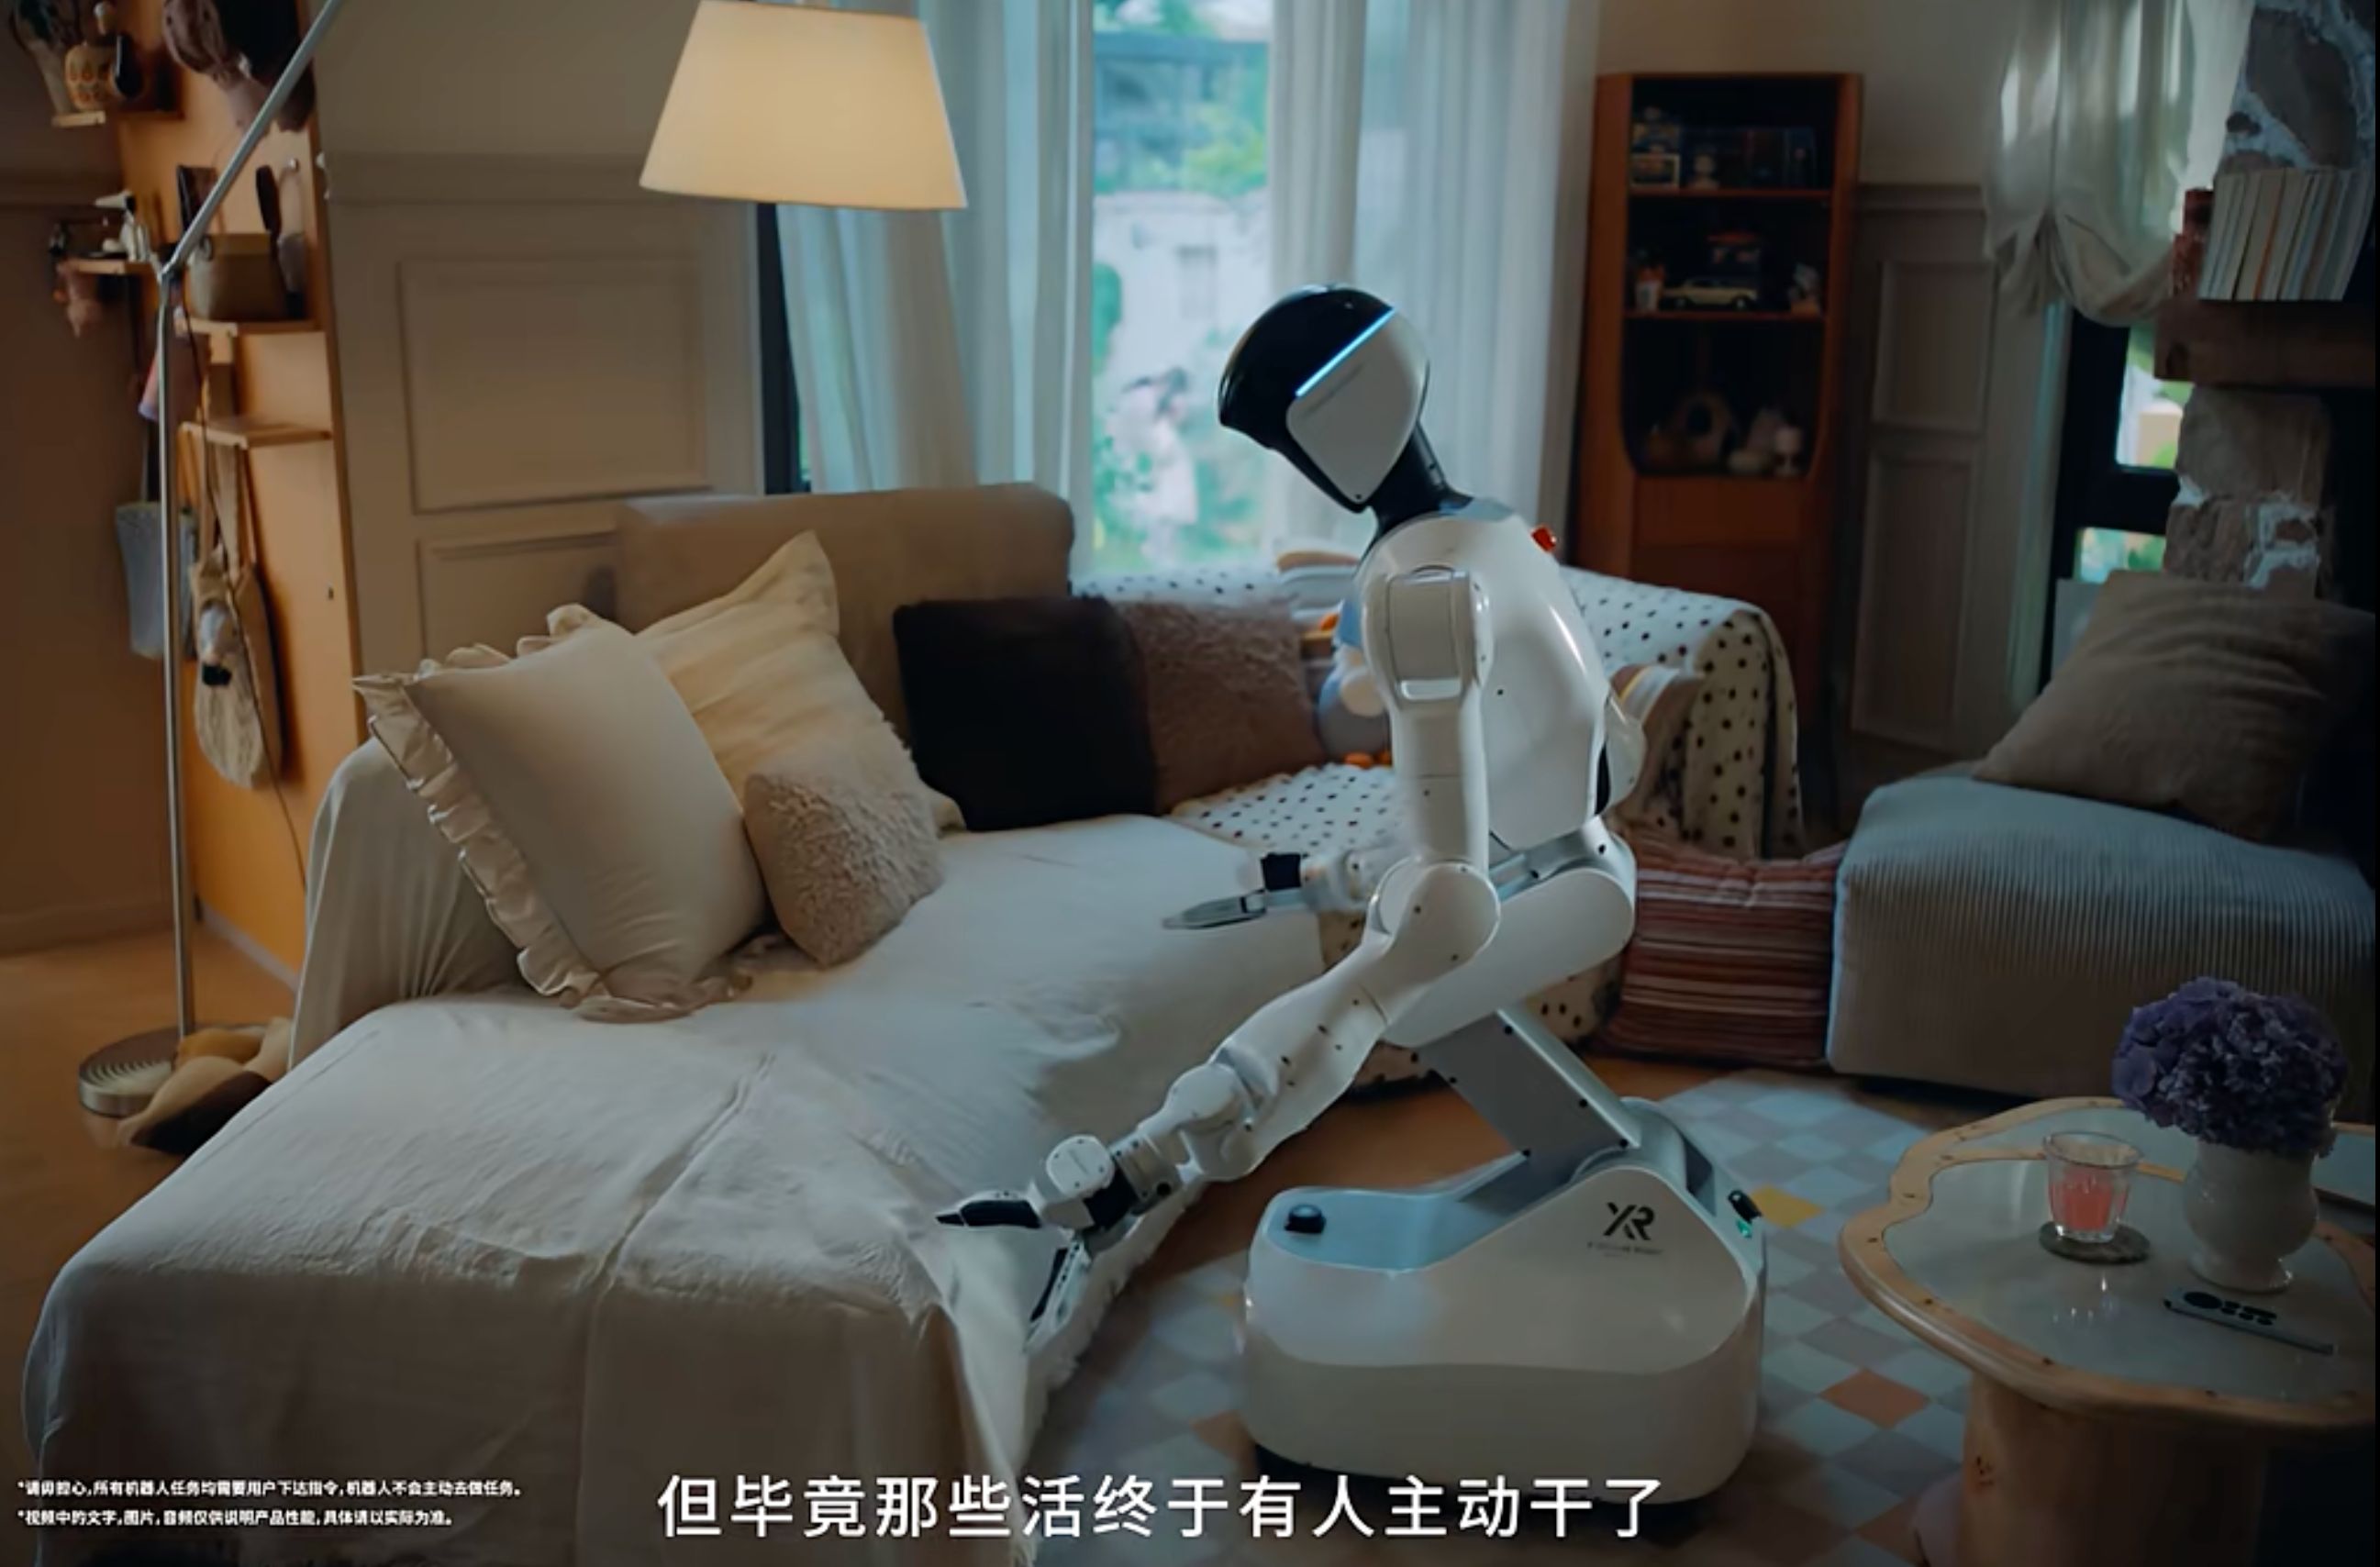
The "Robot Residency in Household Plan" announced at the Independent Variable Robotics press conference (Source/Enterprise)
In addition to the different natures of state-owned capital, there are also great differences between local state-owned capitals. After all, under the "local management" system, local officials not only need to compete in the political field, but also compete in the market.
In the Yangtze River Delta region, the competition between regions is particularly fierce. Some places are extremely insensitive to valuation. Some county-level cities, relying on their manufacturing foundation, have gathered a number of core component enterprises in the upper, middle and lower reaches of the robot supply chain, with strong investment promotion efforts. "With a luxury team and a grand story, even if a valuation of 6 billion yuan is proposed, they dare to invest 100-200 million yuan to attract the enterprise." He Ziyang described.
For them, this is a strategy to attract star projects: grab high-quality targets first, and valuation is not the primary consideration.
This also directly determines the style of investors. "The city you are in basically determines your judgment on the heat of the market." Chen Peng, an investor who has long tracked the hard technology track, told Hard Krypton.
The institution he works for prefers entrepreneurial teams with senior executive backgrounds from large factories, and has previously made several investments in embodied intelligence projects.
However, in the second half of the year, when a project he was in charge of was submitted for review, the review committee finally concluded to postpone the investment. In the past, projects led by senior technical leaders of such leading enterprises would most likely be approved.
"Shenzhen may tighten investment approval today, while industrial funds in Guangxi and some county-level regions in northern Jiangsu are still expanding investment. The rhythm of tightening and loosening is highly regional. As the time window advances, the same city's valuation judgment for the same type of project may be completely opposite." Chen Peng said.
The two styles have different focuses, and it is difficult to tell which is better. A financing director of an embodied intelligence company said bluntly that the preferential policies offered by some regions seem better, but they are easily discounted when implemented. The promised amount cannot be fully obtained after the enterprise settles there. On the contrary, places with long processes and trivial but clear regulations, although the progress in the early stage is slower, have relatively standardized implementation and stronger policy continuity.
For enterprises, choosing which side to go depends on whether they need speed more or certainty more at the moment.
Who is getting the high-quality projects?
It must be admitted that in this competition for embodied targets across the country, it is not the region with the larger capital volume that can lock in high-quality enterprises. The ability to grab good projects depends on the resource endowment of state-owned capital itself and the design of transaction terms. Taking brokerage funds as an example, they are known for their aggressiveness and high incentives, and a team of dozens of people can cover as many projects as a large fund of hundreds of people in first-tier cities.
Of course, in most cases, the state-owned capital investment practice in first-tier cities is a typical sample. A large number of local robot and AI entrepreneurial entities are gathered locally. Relying on the regional industrial network, the investment team has stronger information advantages in project access and due diligence. Taking Nanshan District of Shenzhen as an example, as a high-density industrial cluster city, supply chain, talents, customers and policies can all be reached within half an hour's drive.
The advantage of production factors is only the starting point. With the shift of discourse power in the track, embodied intelligence enterprises have extremely strong bargaining power in financing negotiations. The attractiveness of traditional investment promotion chips commonly used by local governments in the past, such as talent subsidies, tax reductions and exemptions, and industrial land supply, is weakening.
Wu Jianyu told Hard Krypton that leading embodied enterprises have strong bargaining power and are unwilling to accept rigid return investment constraints. "If the local government wants the enterprise to settle in, the investment threshold is often at the 100 million yuan level, requiring heavy bets. Many teams will also complain about the lengthy internal decision-making chain of state-owned capital. On the contrary, some institutions do not set additional conditions for settlement and return investment, which has become the core advantage to attract enterprises."
This is a two-way game, and there is a clear stratification rule: the investment logic of provincial state-owned capital platforms and district-level state-owned capital is diverging.
Most provincial investment companies no longer force enterprises to settle locally or register locally. Since the beginning of this year, many provincial platforms have turned to market-oriented investment without additional conditions. The core reason is that strict settlement and return investment clauses are difficult to capture top projects. In contrast, district and county-level funds still take industrial settlement and return investment as important preconditions for investment.
Behind this change is the top-level guidance correcting the involution of investment promotion. In the past, competitive investment promotion in many places has spawned many potential risks. Local funds bear heavy