Shortly after Muse rose to popularity, Mark Zuckerberg urged it to start monetizing.
In the first week right after Muse launched, Meta had to approach payment firm Stripe to raise its credit limit: users' enthusiasm for letting AI shop on their behalf exceeded all expectations. Roughly six weeks later, over 10 million users in the US and Canada had finished setting up Muse, with shopping emerging as its most popular use case, and the average purchase amount exceeding $200.
Users are willing to spend money, which naturally makes Mark Zuckerberg delighted. However, while payments go to merchants, the AI that runs errands for users consumes Meta's computing power. At the latest earnings call, Mark Zuckerberg stated that Muse would push for commercialization earlier than any of the company's previous new products.
Apart from existing paid subscriptions, he also plans to charge fees from transactions facilitated by Muse, which are expected to be borne by merchants.
Meta remains highly profitable, yet it is indeed under great pressure. Its Q3 revenue hit a new high of $64.601 billion, but its profit was dragged down by a nearly $10 billion litigation settlement cost. Infrastructure investment continues to rise, leaving free cash flow at negative $2.12 billion.
To support subsequent expansion, Meta announced plans to add a new class of non-voting shares, giving the company an extra option for future financing, acquisitions and talent retention, while preserving Mark Zuckerberg's control over the company.
Next, Muse will be integrated into more devices. It will be supported on smart glasses in November, and the dedicated device Charm is scheduled for delivery in December. Mark Zuckerberg hopes users can access their AI at any time, and that more of them will be willing to pay continuously for the service.
The advertising business is still generating steady revenue, and Muse is in urgent need of proving that it can make money for Meta instead of only spending money on behalf of users.
01
Revenue hits a record high, yet Mark Zuckerberg still needs to raise capital
Judging purely from profitability, Meta delivered a strong performance this quarter.
Meta's revenue in the third quarter of fiscal 2026 (ended September 30) reached $64.601 billion, up 26% year on year, marking a new all-time high for a single quarter and exceeding the upper limit of the company's previous guidance of $64 billion.
The advertising business remains robust.
Ad impressions across Meta's apps increased by 10% year on year, while the average ad price rose by 14%. More ads were sold to advertisers, who were also willing to pay higher prices.
For Meta, which is investing heavily in AI, this result at least proves that its core business that supports the company's expansion is still highly competitive.
Mark Zuckerberg, Founder and CEO of Meta, expressed his satisfaction with the results. He noted in the earnings statement that the company's investments are paying off, with its core business delivering strong performance.
However, a closer look reveals a rather noticeable expense: a $9.89 billion litigation settlement cost, which is almost equal to Meta's net profit of $9.86 billion for the quarter.
This expense stems from a 2023 lawsuit over youth social media addiction. Multiple US states accused Meta of knowing that some of its product designs would harm children and teenagers, yet still using features such as infinite scrolling and frequent notifications to maximize their platform stay time.
In August this year, Meta reached a settlement with all relevant parties. In addition to the payment, it also needs to revise the usage rules for minor users, including usage duration limits and nighttime usage restrictions. The settlement amount will be paid in installments as stipulated in the agreement, rather than being paid in full in the third quarter.
After the nearly $10 billion expense was recorded in the books, Meta's operating profit in the third quarter dropped 37% year on year. Excluding this expense, operating profit still grew by roughly 11%.
Therefore, a large part of the impact on profits this quarter comes from old legal liabilities, and cannot be entirely attributed to AI investments.
The signals revealed by cash flow are more worthy of Mark Zuckerberg's attention.
In Q3, Meta generated $32.786 billion in cash from operating activities, but its capital expenditure and principal payments for finance leases reached $34.906 billion, leading to negative free cash flow of $2.12 billion.
The company is still generating cash continuously, but the operating income for the quarter is no longer sufficient to cover these investments.
Moreover, investments will continue. Meta raised the lower limit of its full-year capital expenditure guidance by $5 billion, setting the range at $135 billion to $145 billion. The revenue generated by the advertising business needs to support data centers, servers and an increasing number of new products, and the company is also preparing other funding sources for subsequent expansion.
This time, Mark Zuckerberg has created a new financing tool without diluting his voting control.
The company plans to create a new class of non-voting Class C common stock, to be distributed in the form of stock dividends. For every one share of Class A common stock or Class B super-voting share held, shareholders will receive one share of Class C stock, equivalent to a 2-for-1 stock split. The amendment to the articles of incorporation to create the new share class is scheduled to take effect on January 19, 2027, and the specific share distribution date will be announced separately.
The share distribution itself will not bring new cash to Meta, but it will provide an additional tool for future financing, corporate acquisitions and employee stock compensation. For Meta, which needs to continuously purchase computing power and compete for top talents, this flexibility is very useful. Since the new shares do not carry voting rights, Mark Zuckerberg can also retain his control over the company.
As fund-raising methods increase, the monetization methods for new products must also keep up. This is especially true for Muse, which has just gained popularity and incurs additional service costs for every new batch of users.
02
Muse has to start monetizing as soon as possible at its early stage
Roughly one and a half months after Muse launched, over 10 million users in the US and Canada had completed its setup, around a quarter of whom use it on any given day.
These are the first batch of usage data Mark Zuckerberg shared on the earnings call, which reflects the actual performance of the product more accurately than download figures.
Its most popular use case is shopping.
Susan Li, Meta's CFO, disclosed that more than a quarter of Muse's weekly active users use the shopping feature. Mark Zuckerberg noted that the average purchase amount exceeds $200, including travel expenses. In the first week after launch, transaction volume outpaced expectations, and Meta had to ask payment firm Stripe to raise its credit limit.
This type of task is far more complex than simply answering a question like "what restaurants are nearby". Muse needs to search for and compare products, open web pages, process payment workflows, and may even need to keep running in the background.
So the question arises: these operations save users time, but they also require Meta to provide computing power.
During the earnings call, Mark Mahaney, analyst from investment bank Evercore ISI, directly raised the question to Mark Zuckerberg: In the past, Meta usually expanded its user base and usage volume first, then gradually commercialized its new products. Muse has significantly higher costs, so will Meta speed up the monetization process this time?
Mark Zuckerberg responded that Muse will push for commercialization earlier than any of Meta's previous new products. He explained that both the cost and the commercial opportunity are large enough, so to further scale up the product, the company must make progress on revenue generation.
Muse already had a monetization plan at launch. The basic version is free, while subscriptions for higher usage tiers cost $20 and $100 per month respectively.
The business model Mark Zuckerberg mentioned this time also includes charging fees from transactions facilitated by Muse.
According to his vision, most users can still use Muse for free, and transaction service fees are expected to be paid by merchants. Individuals who need more advanced models and higher usage limits, as well as enterprises that require extra features, will subscribe directly.
Merchant access is also being gradually improved. At the Connect conference in September, Meta announced shopping integrations with Walmart, Best Buy, Sephora and other brands, as well as support for payment methods including Shop Pay and PayPal.
Of course, merchants may not welcome this new model. Amazon has already blocked Muse from shopping on behalf of its customers, stating that Meta did not obtain prior authorization, and raised security concerns about the way Meta processes user credentials and accesses account data.
This means that for Meta to generate revenue from transaction fees, it not only needs to make users feel the product is useful, but also needs to reach cooperation agreements with enterprises that control product and payment entry points. Significant challenges remain.
Ross Sandler, analyst from Barclays, followed up on the per-user cost during the earnings call, and Susan Li stated that no specific figures are available for sharing at the moment.
The fact that users are willing to let Muse spend money on their behalf is already a good starting point. But Muse still faces great challenges in achieving break-even in the future.
03
Hardware is still expected to drive growth
After the earnings release, the market responded positively.
According to Reuters, Meta's share price rose more than 4% in after-hours trading after the earnings announcement.
Meta's Q4 revenue guidance is set at $73 billion to $76 billion, with a midpoint of $74.5 billion, which is higher than market expectations. Advertising growth and next-quarter revenue expectations both support the strong appeal of this earnings report.
In the coming quarter, Meta will launch new initiatives, among which hardware is highly anticipated.
On October 23, Meta Adventurer smart glasses, priced starting at $249, will go on sale, further lowering the purchase threshold. Among already released products, Ray-Ban Meta Audio starting at $349 began shipping on October 13, and the third-generation Ray-Ban Meta starting at $449 was launched in September.
By the end of the year, Meta plans to offer more than 100 styles and configurations of AI glasses.
These glasses will soon share a new common feature. Mark Zuckerberg stated on the earnings call that Muse will be integrated into Meta smart glasses starting in November. Users can talk to their Agent through the glasses, and let it take actions based on products, flyers or long shopping lists in front of them, eliminating the need to take out their phones and input commands.
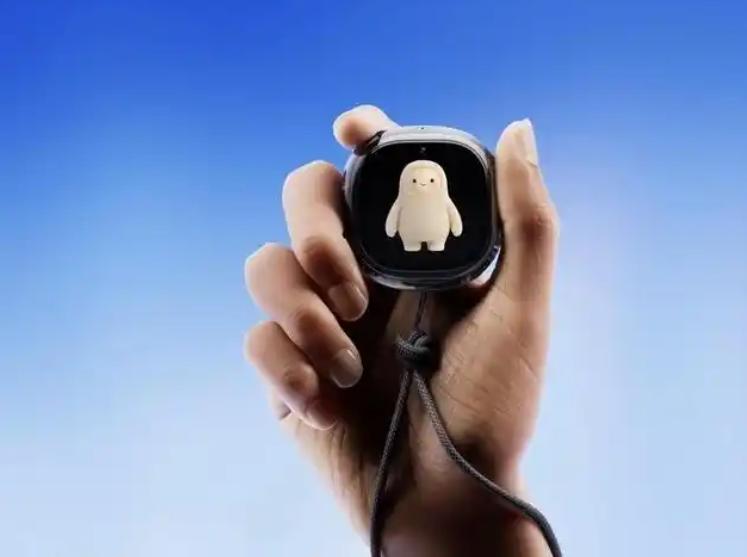
There is also a small dedicated device for Muse called Charm. It is roughly the size of an AirPods charging case, equipped with a roughly 2-inch touchscreen and 5G connectivity, can be hung on a keychain, and is used to interact with Muse. According to the plan Meta disclosed at the Connect conference, this device will be delivered in December for the holiday season, and its price has not been announced at that time.
The reason for such a dense hardware layout goes far beyond simply selling more pairs of glasses.
Mark Zuckerberg explained on the earnings call that the company did not pursue high hardware profit margins when pricing the devices, and hopes to build a larger software and AI business on top of these devices. Glasses and Charm make Muse easier to access at any time, and Meta expects these usages to eventually drive more subscriptions.
However, after the devices are sold, the more frequently users call the Agent, the larger the computing power bill in the background may become. Expanding coverage and reducing service costs need to be advanced simultaneously.
Model updates undertake part of this task. When Muse Wonder was released on October 12, Meta stated that new capabilities would be rolled out to Muse subscribers first, and then Wonder would be used to develop dedicated models to cover more users. During the earnings call, Mark Zuckerberg further mentioned that the company is working on smaller, more efficient models with intelligence levels close to Muse Wonder.
The management's stated goal is to increase computing cost efficiency by more than 10 times in the next year.
Whether users are willing to continuously share more of their information is also a test ahead. Muse needs deep access to users' personal lives to process emails, schedules and shopping tasks. Meta plans to launch Muse Confidential VM within the year, promising to encrypt data and conversations with keys held only by users, so that even Meta itself cannot view the content.
This strategic shift also extends to Reality Labs. The department responsible for virtual reality, augmented reality and related devices is expected to lose $18 billion to $19 billion this year. Meta hopes to narrow its loss to roughly $15 billion next year, and shift more resources to AI.
Susan Li expects the new AI business to start contributing incremental revenue in 2027, but did not disclose specific figures.
From glasses to dedicated devices, from subscriptions to transaction fees, under limited market patience, whether Muse can reduce costs and increase revenue to reach a sweet balance point in time is Meta's biggest challenge in the next stage.
This article is from WeChat Official Account "Alpha AI", author: Xiao Jinya, editor: Wang Jing, published with authorization from 36Kr.