Coreweave and France, two cracks under high interest rates
In the past week, two seemingly unrelated events took place simultaneously: the bond yield of an AI computing power company surged to 15.7%, and the streets of a major European country were engulfed in flames and riots.
On the surface, one is a technical pressure in the capital market, and the other is a political outbreak of social contradictions. But David Curtin, a Goldman Sachs rates strategist, put the two events under the same logical framework — High interest rates are turning the global financial system into a pressure cooker, where pressure erupts concentratedly along the weak links of debt scale, financing cost and cash flow. The first one that cannot hold on may become the first domino in the high interest rate environment.
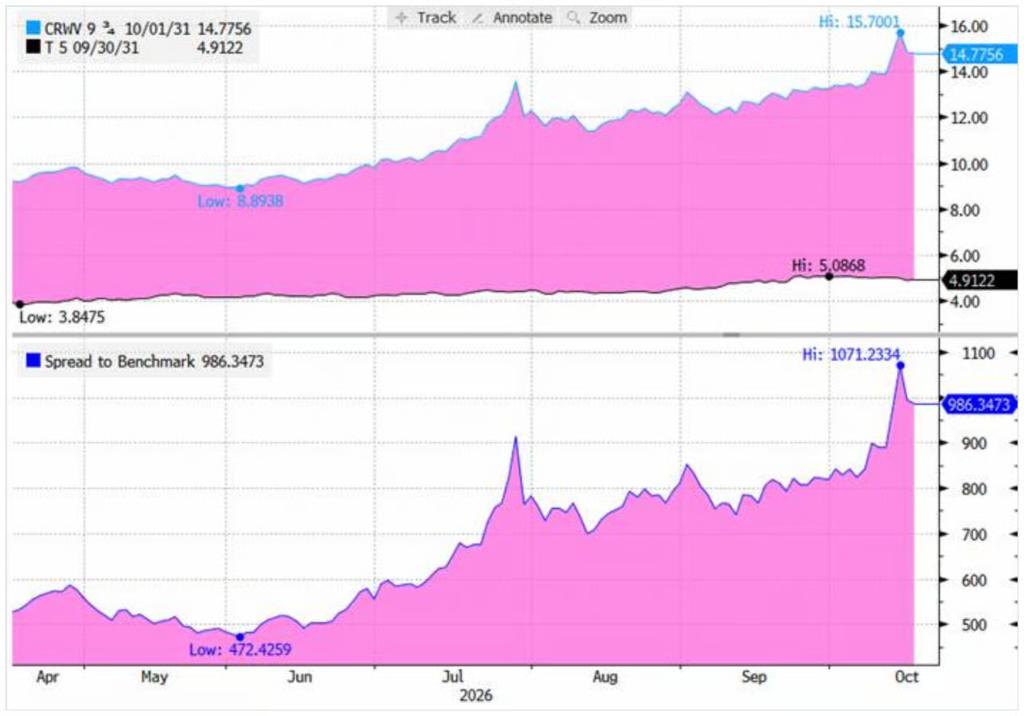
Two sets of figures are enough to illustrate the severity of the situation: the yield of CoreWeave's 9.75% bond maturing in 2031 once rose to 15.7%, and the spread over U.S. Treasuries widened from 472 basis points to a peak of 1071 basis points; the 30-year French government bond yield posted a maximum increase of about 130 basis points since the outbreak of the Iran war, and the French-German spread once hit 142 basis points. What the market is facing is no longer just rising interest rates, but that high interest rates are starting to reshape who can continue to borrow money and who has to pay a higher price for financing.
What is more worth alerting is that Goldman Sachs' analysis points out a counter-intuitive logical closed loop: The AI capital expenditure boom itself is one of the factors driving up long-term interest rates. If high interest rates intensify the financing pressure on AI and force capital expenditure to cool down, long-end interest rates may fall instead — but this does not come without a cost, as the AI industrial chain will face slowing investment, downward revision of asset valuation and adjustment of revenue expectations. Two cracks point to the same possible interest rate inflection point.
The First Crack: CoreWeave, the Financing Cost of AI Prosperity Is Starting to Show
To understand why CoreWeave has become a landmark case under high interest rates, we must first understand its business model.
The logic of CoreWeave follows a typical "debt-driven expansion" path: It purchases NVIDIA GPUs through high-cost financing, builds AI computing power infrastructure, and then gradually recovers investment by relying on long-term contracts signed with large clients such as Microsoft, OpenAI and Meta. This model can generate considerable arbitrage space when interest rates are low; but once financing costs surge, the whole logic starts to come under pressure.
Goldman Sachs data shows that the yield of the 9.75% bond issued by CoreWeave and maturing in 2031 once soared from the low of 8.89% in May to 15.70%, and the spread over U.S. Treasuries also skyrocketed from 472 basis points to a peak of 1071 basis points, then fell back slightly, still staying around 986 basis points. In other words, the market's pricing of CoreWeave's bonds is already close to the most dangerous range among junk bonds. CoreWeave's 5-year Credit Default Swap (CDS) closed at a record 1117 basis points, implying a default probability of about 63% within five years.
What is more alarming is that the risk does not stop at CoreWeave itself: The data centers supported by about 14 billion U.S. dollars of junk-grade bonds have CoreWeave as their sole tenant — and CoreWeave itself also relies on junk-grade bond financing to maintain operations. This forms a rare "junk bond nested in junk bond" structure, where risks multiply geometrically.
The crack has spread to the investment-grade market. Goldman Sachs statistics show that the spreads of 30-year U.S. dollar AI bonds have shown obvious stratification: the spread of Oracle's 30-year bonds is as high as about 300 basis points, SpaceX about 250 basis points, while the 2025 newly issued bonds of Meta and Google are in the range of 170 to 180 basis points, and other leading technology companies are still concentrated around 100 to 130 basis points.
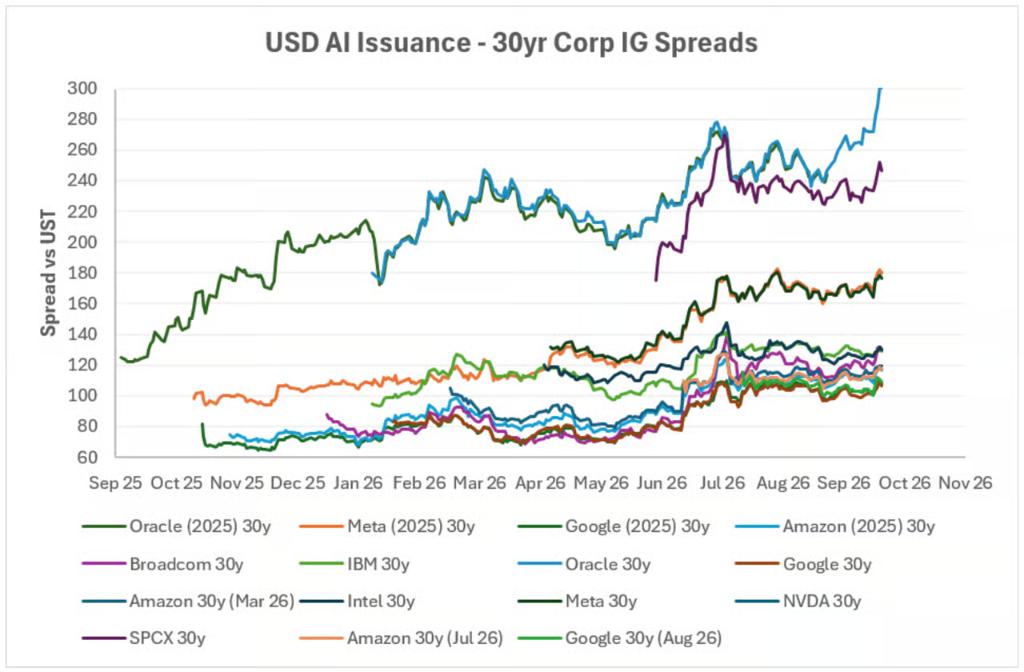
The pricing logic given by the market is very clear: The more money a company needs to borrow, and the more vulnerable it is relative to its own balance sheet, the higher financing premium it has to pay.
Goldman Sachs warns that the core of the current problem is not the weakening of AI computing power demand, but "the cost and scale of financing itself". For hyperscale data center operators, a comprehensive financing cost of 6% to 8% may still be within the acceptable range; but for emerging cloud computing companies with credit ratings below investment grade, high interest rates will "bite the company" faster and more fiercely.
The Second Crack: France, Fiscal Deficit Meets High Long-Term Interest Rates
The problems facing France are logically similar to those of CoreWeave, but with a larger volume and a longer transmission chain.
Since the Iran war triggered the upward movement of global long-end yields, the increase in France's 30-year government bond yield has led among G5 countries — it rose by about 130 basis points from pre-war levels at the peak, and is still about 115 basis points higher now.
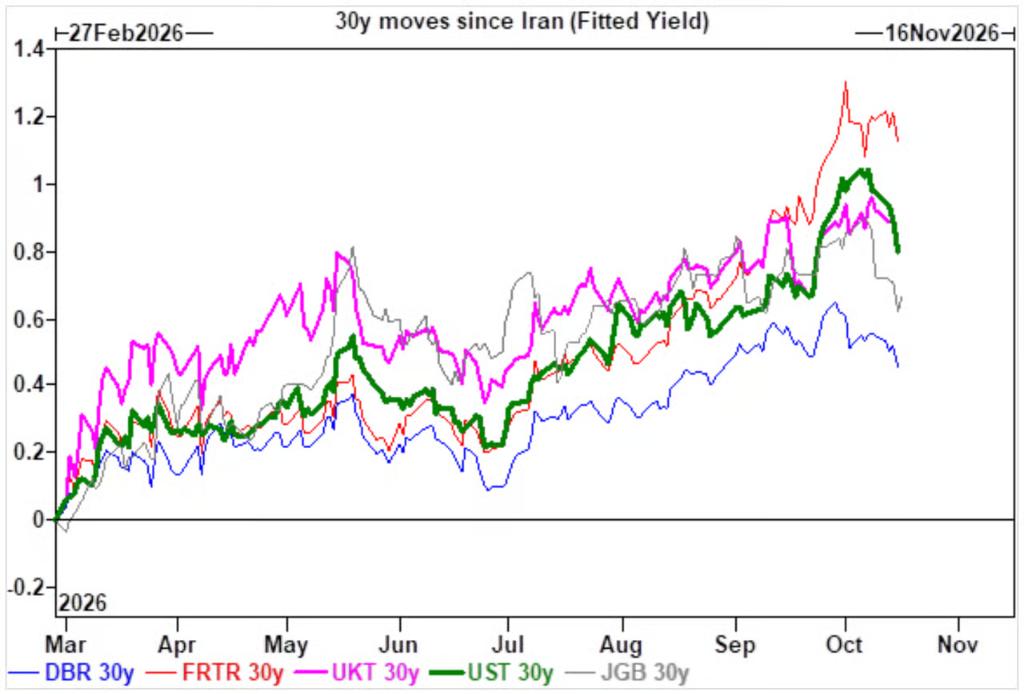
In contrast, German government bond yields only rose by about 45 basis points, and the 10-year French-German government bond spread (OAT-Bund spread) once hit 142 basis points. On the market side, the spread of German short-term government bonds widened, the sovereign credit curve flattened, bank stocks underperformed the broader market, and the euro weakened.
This combination is highly similar to the market reaction during the 2011 European sovereign debt crisis.
France's dilemma lies in: The government needs to continuously roll over huge debts, while bond investors demand higher yield compensation, which means that the cost of both new borrowing and old debt refinancing is climbing. What is more tricky is that the space for fiscal consolidation is extremely limited — Goldman Sachs has a clear skeptical attitude towards France's promotion of fiscal contraction, and points out that the general elections in various European countries in 2027 are unlikely to change this situation.
The Japanese factor is also exacerbating the pressure. Japanese investors have long been important buyers of French government bonds, with holdings of about 23 trillion yen (about 145 billion U.S. dollars). But as the yield of Japan's own government bonds rises, the yield advantage of holding French bonds after exchange rate hedging has narrowed significantly, and capital is withdrawing.
The statement of the International Monetary Fund (IMF) is also worth pondering: the current rise in French yields is "still controllable", but if fiscal consolidation measures are not taken, future financing pressure will further increase. Translated into market language: It is not a crisis now, but if no changes are made, the bond market itself will become a source of pressure forcing the government to adjust its fiscal policy.
Curtin's comment is almost straightforward: France will not take the initiative to cut the deficit unless a bond market crisis forces the government to take action.
Two Cracks That May Point to the Same Interest Rate Inflection Point
Goldman Sachs analysis points out that there are two "strongest driving forces" pushing up global long-end yields — fiscal easing, and the continuous expansion of AI capital expenditure. The former pushes down prices by increasing the supply of sovereign bonds; the latter pushes up the term premium together by supporting nominal GDP growth and a large number of long-term bonds issued for AI financing.
This means that the AI capital expenditure boom is not just a matter of financing demand in the capital market, but also one of the driving forces for the upward movement of long-end yields: The AI construction boom continues to put upward pressure on long-end interest rates through channels such as "supporting nominal economic growth and increasing the supply of long-term bonds". But if high interest rates worsen AI financing conditions and force capital expenditure to cool down, long-term interest rates may fall accordingly.
This logic has been initially verified in the recent market: U.S. CPI and PPI data both exceeded expectations, but the 10-year U.S. Treasury yield unexpectedly fell. The reason is exactly the AI credit concerns triggered by CoreWeave, which have lowered the market's expectations for AI-driven long-term economic growth and long-term bond supply.
However, this is not a "happy ending for all". Goldman Sachs outlines a more complete cycle:
High interest rates suppress the most highly leveraged AI borrowers → debt financing conditions tighten → AI capital expenditure is forced to slow down → long-end interest rates fall due to reduced supply → but the AI industrial chain simultaneously faces downward valuation revision, revenue expectation adjustment and slowing investment.
The bond market may get a respite, at the cost of pressure on the AI industry. This is not the interest rate problem dissolving on its own, but a redistribution of risks across different asset classes.
The Global "Capital War" Has Broken Out
High interest rates are accomplishing one thing: it is forcing the market to reprice a long-forgotten common sense — capital has a cost, and financing has boundaries.
The widening spread of French government bonds shows that the immunity of sovereign debt is declining; the surge in CoreWeave's bond yield shows that the financing foundation of the AI boom is not unbreakable. The two cracks point to the same direction: the impact of high interest rates is transmitting from the pricing level of the financial market to the financing capacity level of real borrowers.
Goldman Sachs analyst Privorotsky warns that in the post-financial crisis era, the world economy operated on abundant savings and structurally low interest rates. The fiscal systems of various governments are also built on the assumption that cheap capital will exist for a long time. And this assumption is now collapsing.
If artificial intelligence investment can generate an internal rate of return of 20%-30%, financing at an interest rate close to double digits is still reasonable. But the question is what about other sectors that also need capital. This may explain why real yields are difficult to fall. If the market expects a large number of high-quality private sector bonds to be issued soon, the attractiveness for investors to buy sovereign bonds will decline.
Privorotsky puts forward two possible outcomes: first, AI gradually achieves self-sustainability, and financing pressure eases; second, capital is rationed in other fields, and the more vulnerable links in the economy start to break.
Pressure erupts concentratedly along the weak links of debt scale, financing cost and cash flow. The one with the most vulnerable balance sheet will be squeezed out first. And when the squeezed-out borrower is large enough — whether it is a country or an AI infrastructure empire — the entire market will have to recalibrate its judgment on the "long-term interest rate center".
This recalibration has only just begun.
This article is from WeChat official account "Wall Street CN", author: Xu Chao, published with authorization from 36Kr.