September Asia (China) Long-term Rental Apartment Development Report
September Asia (China) Long-Term Rental Apartment Market Overview
01 Global Apartment Market Development Dynamics
In September, according to the monitoring data from Asia Travel & Hospitality Big Data Research Institute, the global housing rental market entered the stage of "seasonal correction, slowdown and bottoming out" in the off-season of Northern Hemisphere autumn. From the perspective of rent changes, the month-on-month figure (compared with August) began to show a slight seasonal decline or stabilization at a high level, and landlords started to offer moderate concessions as the late summer off-season approached; the year-on-year figure (compared with the same period last year) generally maintained a slow and moderate increase or remained basically flat.
In the United States, the housing rental market entered the traditional autumn off-season in September, which is overall characterized by "stabilized rent at high level, slowly declining vacancy rate, and polarization between coastal gateway cities and the Sun Belt". The Zillow Observed Index shows that the national average listed rent is about $1,932 per month, and the median listed rent is $1,833 per month. Rents in coastal technology and financial centers remain strong: driven by the recovery of the technology industry, stable employment and limited new housing supply, the average listed rent in San Francisco reaches $3,400–$4,750 per month, leading the country in year-on-year growth; the median rent in San Jose (Silicon Valley) is about $3,310–$3,800 per month; the figure in New York is about $3,615–$3,695 per month, remaining at a high level due to extremely tight supply. Core cities in the Midwest show steady performance: the average rent in Chicago is about $2,022 per month. Without concentrated excessive construction in the early stage, the demand is stable and there is no backlog of inventory, so the rent shows a moderate increase. Cities in the Sun Belt and southern regions are under pressure and remain sideways: a large number of new apartments in Austin and other areas were delivered intensively under the construction boom in previous years, leading to oversupply in the market and limited bargaining power of landlords. The average listed rent is about $1,620–$1,986 per month, and the rent is in the stage of "squeezing out the bubble".
In Italy, the housing rental market entered the stage of "slight seasonal adjustment and bottoming out at high level" in late summer and early autumn. With the end of the summer tourism peak and the gradual absorption of rental demand for the new semester of universities, the overall market continues to remain at a historically high level, while showing signs of slight sideways cooling month-on-month, and maintaining a moderate upward trend year-on-year. According to data from mainstream Italian real estate platforms (Immobiliare.it, etc.), the national median monthly rent of rental apartments is about 934 euros. The price in Milan still ranks first in the country, but affected by factors such as tenants' affordability approaching the critical point and the ebb of summer short-term rental boom, the price shows a slight high-level correction, with the average listed rent at 22.32 euros/㎡/month; due to the imbalance between long-term and short-term rental supply in the historical and cultural center of Florence, the price remains high, with the listed rent at 21.75 euros/㎡/month; relying on the strong demand for employment, education and international tourism in the capital, Rome maintains a strong year-on-year increase, with the listed rent at 19.13 euros/㎡/month; after the autumn enrollment reservation in September comes to an end, the listed price in Bologna drops slightly from the summer peak, reaching 16.51 euros/㎡/month.
In the UK, the housing rental market ushered in a strong demand peak of university opening and autumn employment, and the average rent across the UK hit a new all-time high. According to the authoritative statistics of HomeLet and Zoopla in September 2026, the average listed rent across the UK rose to £1,387 per month. Driven by the concentrated opening of international students and the relocation tide of workplace in September, Greater London and some education and high-tech towns recorded strong growth, while some regions showed a slight seasonal adjustment after the rise in late summer. The Greater London area rebounded strongly and led the price, with the average rent reaching £2,272 per month (the median rent of newly listed high-quality apartments in Zone 1-2 of the core area is close to £2,750–£2,800 per month); the average rent in southeast England is £1,472 per month, up 1.8% year-on-year; the average rent in eastern England is £1,340 per month, up 2.0% year-on-year; the average rent in southwestern England (including Bristol and Exeter) reaches £1,274 per month, up 5.4% strongly year-on-year; the average rent in Scotland (Edinburgh, Glasgow) is about £1,060–£1,070 per month, driven by the demand of the opening season of famous universities such as Edinburgh, up 4.9% year-on-year.
02 Asia-Pacific Rental Market Development Dynamics
In Australia, after experiencing the sharp surge in previous years, the housing rental market as a whole entered a rational consolidation period of "bottoming out at high level, slight monthly decline, and low year-on-year growth". According to data from institutions such as CoreLogic (Cotality) and SQM Research, the national median weekly rent of residential properties in Australia is 627 Australian dollars per week (about 2,717 Australian dollars per month). The price in Sydney still leads the country, but the rent has touched the ceiling of tenants' affordability, with a slight month-on-month decline of 0.2% in September, showing a trend of "squeezing out the bubble" at high level, and the median weekly rent is 780–840 Australian dollars per week; the rent threshold in Melbourne is relatively low among the large cities on the east coast, but with the continuous inflow of migrant population, the apartment rental market shows strong resilience (a slight increase of 0.1% in September), and the median weekly rent is 575–640 Australian dollars per week; after the previous sharp surge, the overall weekly rent in Brisbane decreased slightly by 0.1% in September, entering a stable period of supply-demand game, with the median weekly rent of 630–670 Australian dollars per week; Perth, driven by both the active resource-based economy and the continuous net inflow of population, has a vacancy rate of only about 0.7%, which is still the most in-demand and fastest-growing market in Australia, with the median weekly rent reaching 680–720 Australian dollars per week in September.
In Singapore, the residential rental market continues the operation pattern of "overall stable consolidation at high level, balanced supply and demand, and more prominent regional differentiation". The median listed rent of apartments across the island remains at about 4,300–4,800 Singapore dollars per month, basically flat month-on-month, with a slight low year-on-year increase and tending to stabilize. By apartment type, the rent for one-bedroom is 3,100–4,100 Singapore dollars per month, two-bedroom 4,000–5,500 Singapore dollars per month, and three-bedroom 5,200–7,200 Singapore dollars per month. The HDB rental market attracts strong rigid demand by virtue of its cost-effectiveness, with extremely strong rent performance, and the annual rent growth rate across the island slows down to around 3.2%. Among them, the rent for 3-room (two bedrooms, one living room) is 2,800–3,300 Singapore dollars per month, 4-room (three bedrooms, one living room) 3,400–3,900 Singapore dollars per month, and 5-room (three bedrooms, two living rooms) 3,800–4,400 Singapore dollars per month.
It is worth noting that a large number of pre-sold private residential properties in suburban areas such as Lentor and North Tampines were completed and delivered in the second half of the year, and the publicly available rental housing stock increased significantly, effectively breaking the previous situation of supply shortage. At the same time, the policy of imposing an additional 60% buyer's stamp duty on foreign buyers who do not hold Permanent Resident (PR) status remains effective, so the vast majority of high-paid foreign talents choose "long-term rental transition", which provides a solid demand base for mid-to-high-end private residential properties. In this context, although landlords no longer raise rents sharply as they did in the previous two years, squeezed by high mortgage interest rates and property taxes, the cost of holding properties remains high, and the vast majority of landlords also refuse to cut prices significantly. The overall market maintains a high-level consolidation at the "reasonable median" level.
In South Korea, after experiencing the peak of summer relocation and school district reservation, the residential rental market entered a tense operation state of "continuously rising Jeonse and monthly rent prices, deepening supply shortage, and irreversible trend of monthly rent". The national average monthly rent is about 838,000 – 850,000 won per month (equivalent to about RMB 4,300 – 4,400 yuan), and the average initial deposit is about 54.5 million won. The average monthly rent of apartments in Seoul Special City reaches 1.62 million – 1.65 million won per month (equivalent to about RMB 8,300 – 8,500 yuan). The average monthly rent of small-sized units such as studio apartments/Officetel/Villa is concentrated at 800,000 – 1,000,000 won per month. The average monthly rent in the Capital Area (Gyeonggi-do, Incheon) is 860,000 – 1,010,000 won per month. The average monthly rent in major local metropolitan cities (Busan, Daejeon, Ulsan, etc.) is 670,000 – 760,000 won per month.
03 China's Rental Market Development Dynamics
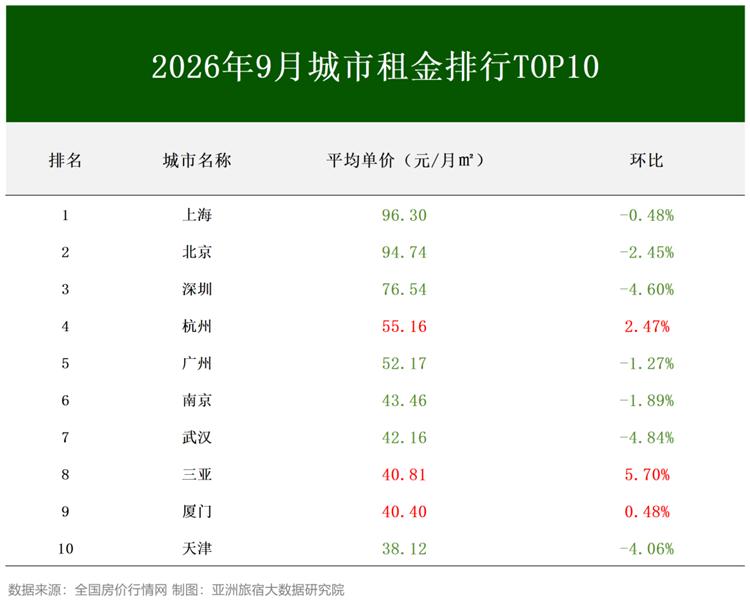
In September, the rents of top 10 key monitored cities rose in 3 cities and fell in 7 cities month-on-month. According to the data from China Housing Price Market Network, the national median rent is 1,700 yuan per month, down 2.86% month-on-month. In September, the city with the largest month-on-month decline among the top 10 cities is Wuhan, with a decline of 4.84%, and the city with the largest increase among the top 10 cities is Sanya, with an increase of 5.7%.
04 Opening Dynamics of Rental Enterprises
In September, according to the monitoring of Asia Travel & Hospitality Big Data Research Institute (ABN Index), a number of apartments or rental housing projects were opened and signed. Representative projects are as follows:
China Merchants Shekou CM+U One Apartment Jiayu Tsim Sha Tsui opened. On September 3, the China Merchants Shekou CM+U One Apartment Jiayu Tsim Sha Tsui project was officially opened, and the "CM+U One Apartment Jiayu" and "C Star Youth Innovation & Entrepreneurship Friend" brands were officially unveiled. As a new product line extended from China Merchants Shekou's "One" series apartment brand to Hong Kong, CM+U not only represents Youth and University, but also focuses on You (every one of you), placing the deep expectation of "cheer for you". Based on the concept of "safety, reassurance and comfort", the project builds a warm and comfortable "second home" for young people studying in Hong Kong. As the first landing project of this product line, the Tsim Sha Tsui project covers multiple types of apartments including single, double and multi-person units.
Hanyue Apartment Kaide Xiyuan Second Store opened. On September 14, Wuhan Urban Construction Group released the news that its subsidiary Hanyue Apartment Kaide Xiyuan Second Store was opened. The project is located in Building 3, Kaide Xiyuan, Fu'an Street, Hongshan District, Wuhan, providing 445 housing units. The one-bedroom units cover an area of 44.45–68.87 square meters, and the one-bedroom one-living room units cover an area of 70.75–88.93 square meters. The project focuses on fine decoration and check-in with luggage, which is suitable for single, couple and family tenants.
Beijing Lehu Apartment Yayuncun Store opened. In September, Beijing Lehu Apartment Yayuncun Store opened. The project is located on the south side of No. 118 North 4th Ring East Road, Chaoyang District, in the east area of Anhuqiao, adjacent to Huixin West Street North Station of Metro Line 5, with convenient transportation. Positioned as a "single-person hedonistic living community", the project has 225 guest rooms, featuring independent units, fine decoration and check-in with luggage, equipped with open kitchen, separated dry and wet bathroom, smart door lock and other facilities.
Ascott's new brand YAYU signed its first store in Kunming. On September 4, Ascott officially announced its new layout, and its YAYU brand officially entered Kunming to launch the first service apartment project in the city. The project has a construction area of about 20,000 square meters, with 183 fine-decorated apartments planned, covering multiple unit types such as studio, one-bedroom and two-bedroom.
Lingju Apartment signed its first store in Wuhan. On September 17, Jin Jiang International Hotels' long-term rental apartment brand Lingju Apartment disclosed that its first store in Wuhan was officially signed. The project is located in the core section of Jianghan Economic Development Zone, close to the Second Ring Road and Changqing Elevated Road, about 700 meters away from Yuanboyuan Station of Metro Line 7, with bus stations around and convenient commuting. The project is a single independent building with a total of about 120 units.
Yuexing Apartment signed to enter the core area of Guangzhou Baiyun Airport Economy. On September 22, Guangzhou Yuexiu Star Apartment Management Co., Ltd. and Guangzhou Airport Asset Operation and Development Co., Ltd. jointly signed the project cooperation agreement for Konggang Yueju · Yunyi Garden Store. The project is located in the core area of Guangzhou Baiyun Airport Economy, close to Baiyun Airport, in the Jianggao-Shuili commercial and industrial agglomeration area. The total construction area of the project is about 66,400 ㎡, with 684 entrusted housing units, totaling 2,344 rooms, equipped with multiple unit types such as exquisite three-bedroom (85 ㎡), comfortable four-bedroom (110 ㎡) and premium spacious four-bedroom (130 ㎡), which can meet the living needs of different family structures.
Nanyang Sanguanli in Henan signed a cooperation with The Sebel under Accor. On September 24, Minglun Sanguanli Commercial in Nanyang, Henan signed a cooperation with "The Sebel", a high-end apartment and extended-stay hotel brand under Accor Group. The project is located at the intersection of Chezhan Road and Gonggeng Road, close to the Wolonggang Cultural Park, facing the Han Dynasty Painting Museum, rooted in the 50,000 ㎡ immersive cultural tourism commercial block of Sanguanli. Sanguanli is positioned as a composite ecology of "trendy commerce + immersive cultural tourism + international high-end residence", and the addition of The Sebel completes the closed loop from commerce, cultural tourism to international high-end accommodation.
05 Entry Dynamics of Indemnificatory Rental Housing and Talent Apartments
In September, driven by both policies and capital, the indemnificatory rental housing and talent apartment market is developing steadily towards large-scale, professional and refined direction, providing more diverse and high-quality housing security for new urban residents and young talents.
GEM Community Yangpu Riverside Store launched 662 indemnificatory rental housing units. On September 1, GEM Community Yangpu Riverside Store officially entered the market, launching 662 fine-decorated apartments (all 28-32 ㎡ fine-decorated one-bedroom units, check-in with luggage, equipped with brand home appliances and furniture). The apartment is located on the core coastline of Yangpu Riverside, about 800 meters away from the Yangpu Riverside industrial belt, with gathering of science and innovation enterprises such as Bilibili, Meituan and ByteDance around, with convenient commuting.
Longgang plans to acquire 2 buildings with 88 housing units through market-based operation for indemnificatory rental housing. On September 2, Longgang District of Shenzhen released the procurement intention of feasibility study service for market-based acquisition of commercial housing as indemnificatory housing projects, planning to carry out acquisition feasibility study for 2 indemnificatory rental housing buildings, involving 88 housing units and a construction area of 6,319.42 square meters.
The sixth batch of talent apartments in Zhengzhou launched 1,091 units with 1,252 rooms. On September 11, Zhengzhou released the public rental announcement for the sixth batch of talent apartments in 2026. This batch is operated by Zhengzhou Chengfa Anju Co