A-share Research Report Map: Research resources are concentrated in companies with a market value of over 20 billion yuan, and 344 electronic enterprises are focused on.
The number of research reports is one of the most intuitive indicators to measure institutional attention to A-share listed companies.
Since 2026, against the backdrop of intertwined factors including performance verification, industrial iteration, and the transformation of sell-side research business in the A-share market, the coverage rhythm of securities firms on listed companies has changed significantly. Through statistical data such as the total number of research reports released within the year, covered targets, and industry distribution, we can clearly see the changes in the research focus of institutional funds and the pattern of further differentiation of A-share research resources.
According to data from Tonghuashun, 2910 listed companies have been issued research reports by research institutions since the beginning of this year. The data shows that the focus of institutional research has shifted heavily to leading enterprises in various industries, and from an industry perspective, the electronics industry has taken a sharp lead.
Kweichow Moutai ranks first with 184 research reports
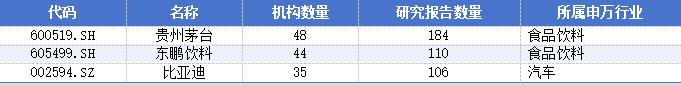
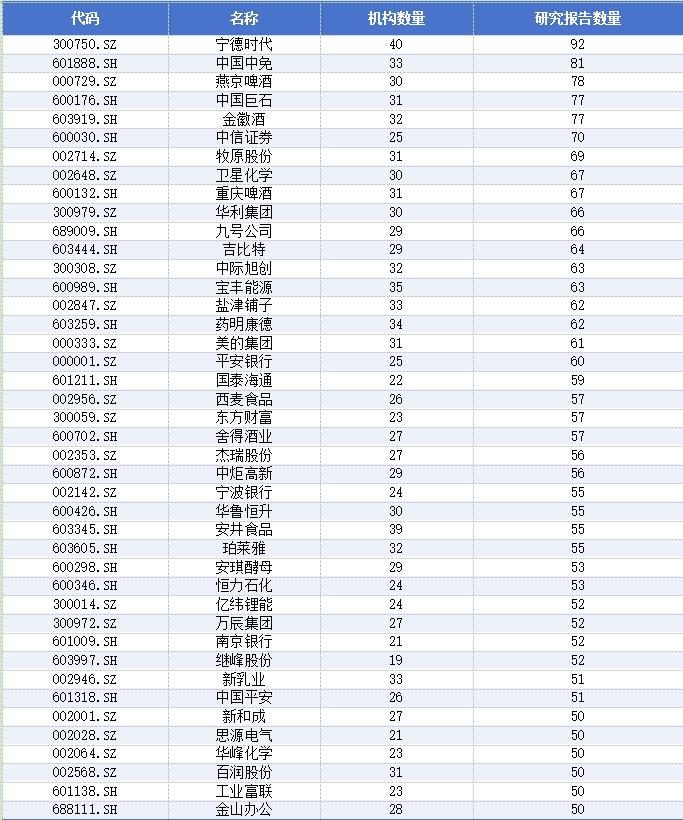
Data from Tonghuashun shows that 45 listed companies have received more than 50 research reports since the beginning of this year, almost all of which are well-known leading enterprises. Among them, Kweichow Moutai, Dongpeng Special Drink and BYD rank top 3, with 184, 110 and 106 research reports respectively.
As the benchmark of core assets in the A-share market, Kweichow Moutai is a standard position in the portfolios of public funds, social security funds and foreign capital. The institutional position base is large, and every change in quarterly financial reports, batch prices, sales momentum and distribution channels will trigger continuous tracking by institutions. Institutional investors need high-frequency updated earnings forecasts and valuation calculations, which naturally generate a large number of continuous tracking research reports, making it a "mandatory covered core position target".
BYD is the leader of new energy passenger vehicles, with a long industrial chain and many variables (sales volume, price war, overseas expansion, new technologies, production capacity). Monthly production and sales data and policy changes will cause disturbances to fundamentals. Analysts need to continuously update their models, and institutions have a high allocation weight in the new energy sector with active transactions and strong tracking demand.
Dongpeng Special Drink is relatively special. As the leader in a segmented consumer track, institutional allocation has continued to increase after its listing. The energy drink track still has growth narratives, coupled with highlights such as performance flexibility and channel expansion. It is a large target in a small segmented track, and analysts in the consumer team continue to track it.
In addition, well-known enterprises such as CATL, China CDFG, Yanjing Beer, China Jushi, Jinhui Liquor, CITIC Securities, Muyuan Co., Ltd., Satellite Chemical, Chongqing Brewery, Huili Group, Ninebot, G-bits, Zhongji Innolight, Baofeng Energy are all classified as listed companies that have received more than 50 research reports.
It can be seen that the main track status is prominent, and most of them are benchmark targets in their respective sectors. For example, CATL is the global leader in power batteries and the core anchor of the new energy sector; Muyuan Co., Ltd. represents the pig breeding track; China Jushi (fiberglass), Satellite Chemical and Baofeng Energy belong to the chemical/material cycle track; Zhongji Innolight represents the popularity of the AI computing power industrial chain.
The listed companies that have received more than 50 research reports are as follows:
20-billion-yuan market cap acts as the watershed
The distribution of A-share research resources shows a clear feature of "concentrating on mid and large-cap targets".
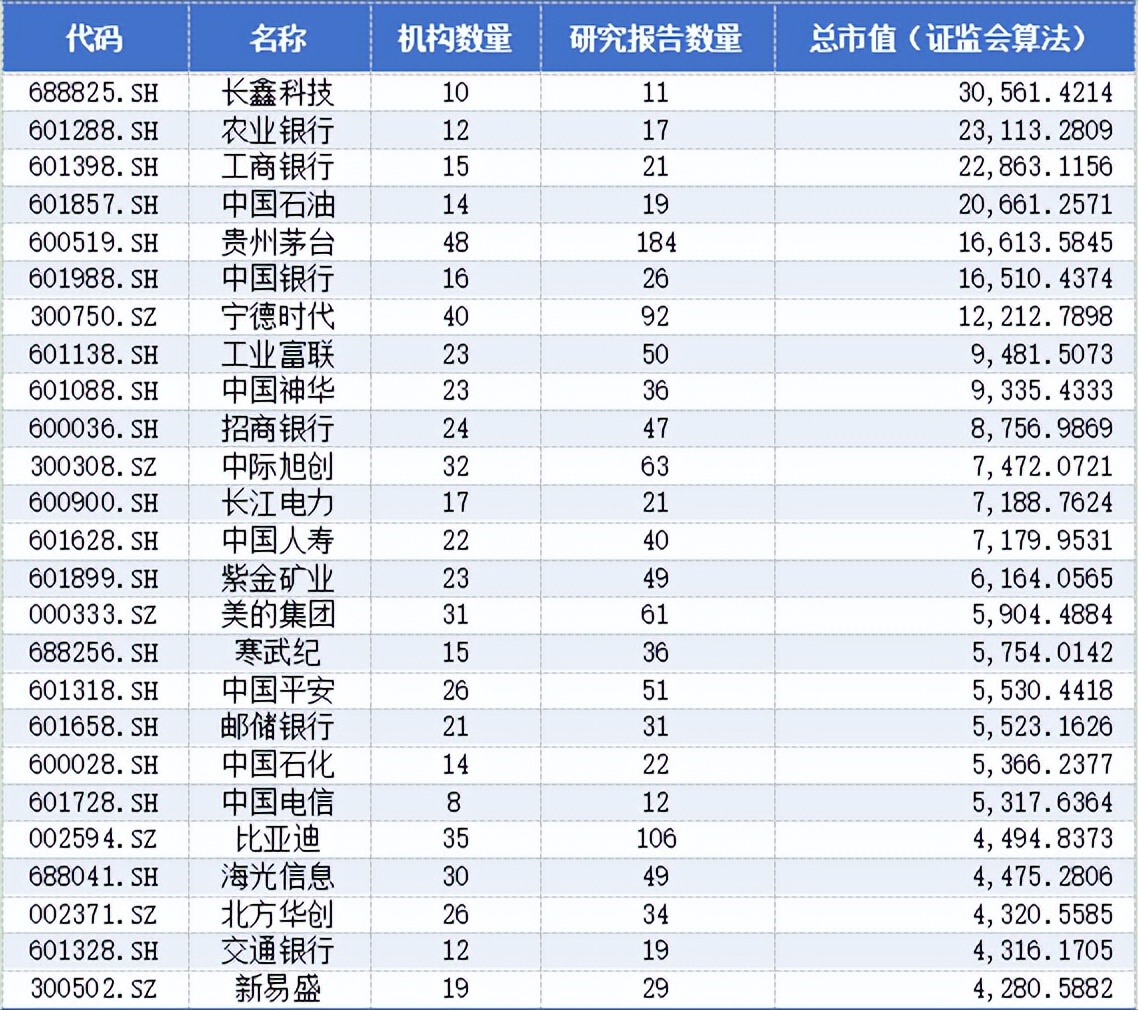
According to statistics of the 2910 listed companies covered by research reports across the market, the total number of cumulative research reports reaches 26754. Among them, the number of research reports corresponding to companies with a market value of more than 20 billion yuan reaches 14256, accounting for more than 50%.
After further breaking down the structure, the degree of resource tilt is even more prominent. Among all the 2910 covered listed companies, there are only 828 enterprises with a market value of more than 20 billion yuan, accounting for only 28.45%. This means that less than 30% of the mid and large-cap targets in the whole market directly take more than half of the analyst research output, and the trend of research resources concentrating on leading entities remains very clear.
CITIC Securities covers the largest number of companies
From an institutional perspective, since the beginning of this year, CITIC Securities, Changjiang Securities, Tianfeng Securities, Huatai Securities, Industrial Securities, China International Capital Corporation, GF Securities, Kaiyuan Securities and Guosen Securities have been relatively active in updating research reports, covering 1060, 841, 777, 725, 686, 684, 707, 702 and 680 listed companies respectively.
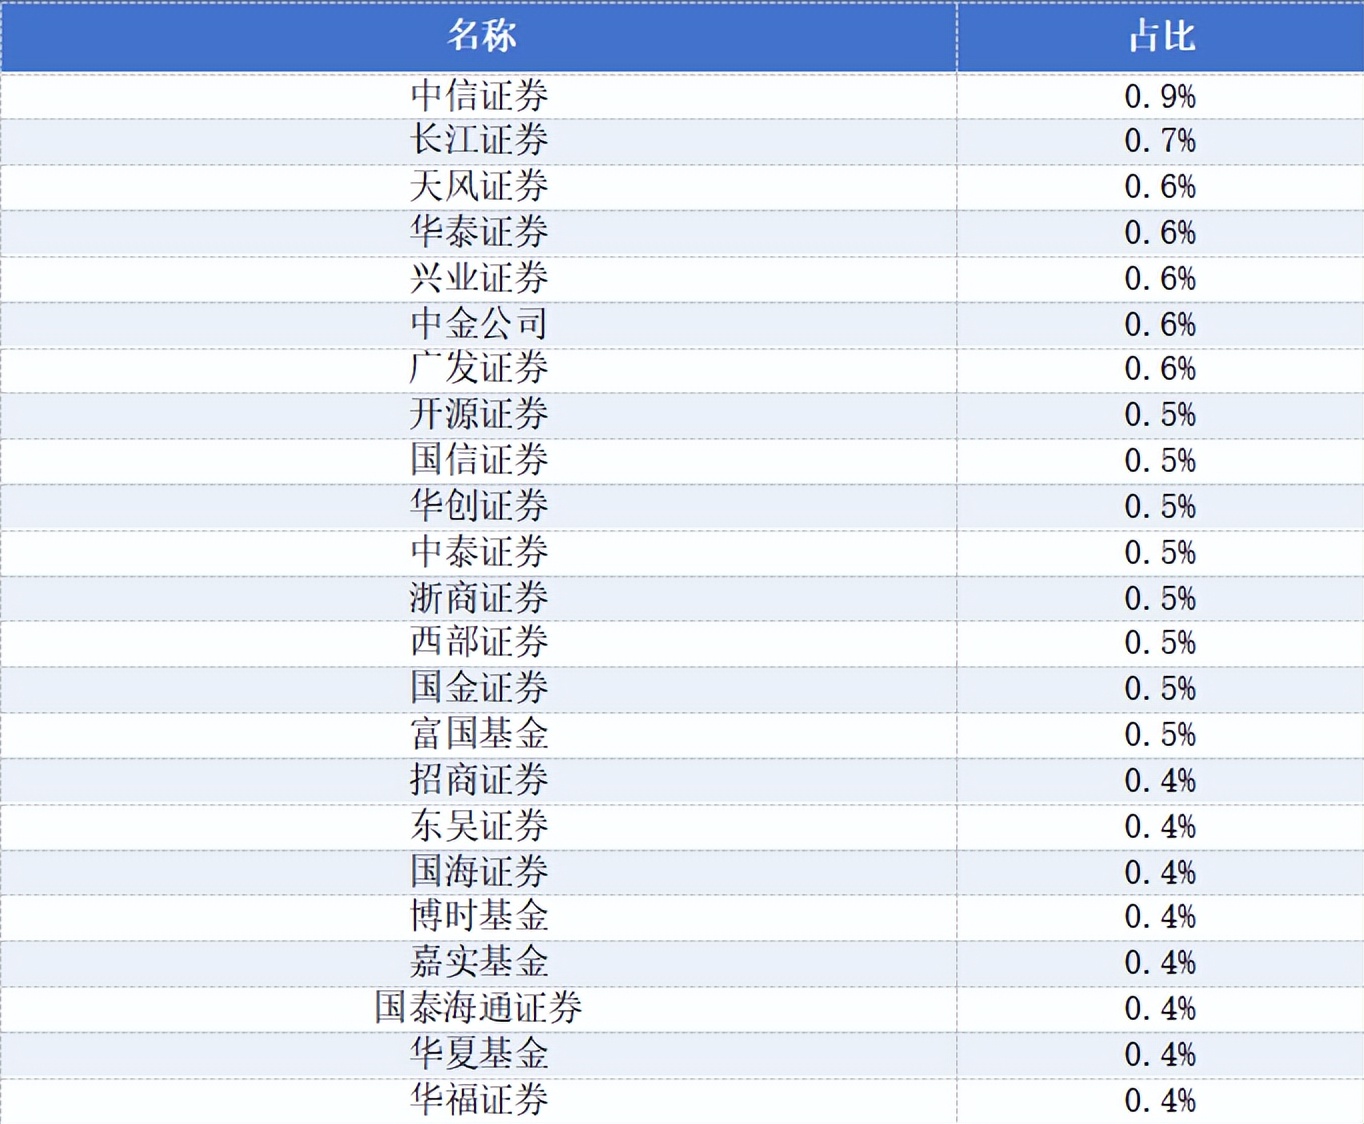
CITIC Securities covers 1060 companies, significantly higher than its peers. Behind this is the largest sell-side team in China, with complete industry group configurations, covering large-cap blue chips and track leaders, while also sinking to cover a number of mid-cap targets. Its clients cover diverse institutions such as public funds, insurance, foreign capital and private equity. The rich client types determine that the research coverage must be wide enough, not only to serve long-term funds that hold heavy positions in core assets, but also to meet the needs of various institutions to explore small and medium-sized targets, so the number of covered listed companies leads by a large margin.
The electronics industry is far ahead
From an industry perspective, the electronics industry has the largest number of listed companies that have been issued research reports, reaching 344; in addition, the number of listed companies that have been issued research reports in the pharmaceutical and biological, mechanical equipment, basic chemical, power equipment, automotive and computer industries all exceed 100.
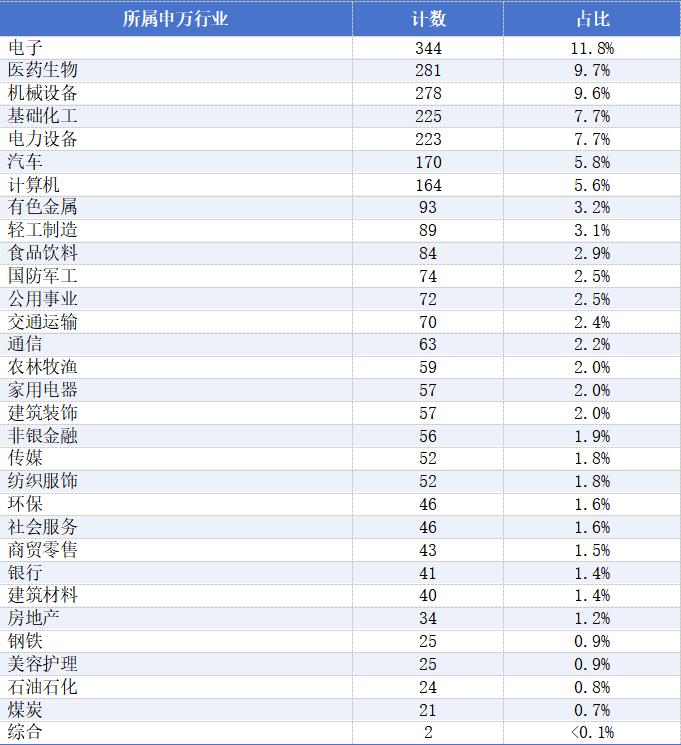
It can be considered that this set of industry distribution data clearly outlines the current track focus of sell-side research: high-end manufacturing and technology growth tracks occupy the main body of the research report coverage pool, while the research coverage breadth of traditional industries is obviously weaker.
The electronics sector takes the leading position as a result of multiple overlapping factors. On the one hand, the electronics sector itself is one of the sectors with the largest number of A-share listed companies, with extremely many segmented tracks: optical modules, semiconductors, PCB, consumer electronics, display panels, components, etc., with clear industrial chain stratification. The AI computing power boom drives the entire upstream hardware chain to continuously generate new variables, and overseas customer orders, technology iteration, inventory cycles and price fluctuations continuously generate tracking events; on the other hand, institutional funds are actively allocated in the technology hardware sector, with rich segmented targets, including thousand-billion-yuan leaders such as Zhongji Innolight and a large number of small and medium-sized segmented component targets. Analysts have enough targets to cover, so the number of companies covered by research reports is far ahead.
This article is from the WeChat official account "Lanfu Finance", authored by Lanfu Finance, and published with authorization from 36Kr.