The IPOs of AI companies have begun to collectively hit the brakes.
Recently, a rather abnormal phenomenon has emerged in the US stock market.
The primary market is still offering sky-high valuations to AI companies, but when it comes to the listing stage, secondary market investors have begun to reject such valuations.
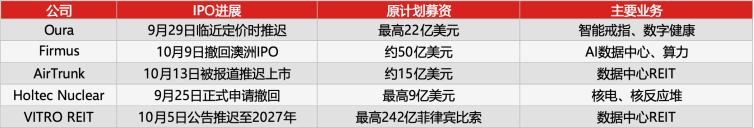
In less than a month from mid-September to mid-October, at least four enterprises related to the AI industrial chain or AI investment narrative have successively announced the delay or withdrawal of their listings, covering smart hardware, AI computing power, data centers and nuclear power.
On October 9, Firmus, an Australian AI data center company in which NVIDIA holds a 7.2% stake, officially withdrew its IPO application.
The company has received support from investment institutions such as NVIDIA, Blackstone and Coatue, and its customers include OpenAI and Meta. Logically speaking, it has almost all the bonus points: AI concept, star shareholders and large key clients.
Yet it still failed to complete the IPO.
Earlier, Oura, a smart ring manufacturer, also suddenly announced the delay of its IPO on the day when the issue price was supposed to be determined. The core reason was that no agreement on the valuation was reached.
On the one hand, the valuation of AI assets in the primary market keeps rising, while on the other hand, the secondary market has begun to say "no" to these high valuations. The pricing logic of this round of AI assets is undergoing subtle changes.
Today, Silicon-Based Commentator will talk about this issue.
/ 01 / The secondary market has turned its back on "new AI stocks"
Among the AI companies that have pressed the brake on IPOs, the most well-known one is Oura, the smart ring manufacturer.
On September 21, Oura officially launched its IPO roadshow, planning to raise a maximum of 22 billion US dollars, corresponding to a fully diluted valuation of about 15.6 billion US dollars.
In fact, this company is not short of performance. In the past 12 months, Oura achieved revenue of 1.21 billion US dollars, a year-on-year increase of 74%. It is expected that its revenue for fiscal year 2026 will grow by 90%, and it has already achieved profitability.
According to Reuters, Oura's IPO had already obtained about 4 times over-subscription at that time. But on September 29, the day originally scheduled to determine the issue price, Oura suddenly announced the delay of the IPO.
A similar situation has also occurred in the AI infrastructure sector.
On October 9, Firmus, an Australian AI data center company in which NVIDIA holds a 7.2% stake, officially withdrew its IPO application.
The company has received support from investment institutions such as NVIDIA, Blackstone and Coatue, and its customers include OpenAI and Meta. Logically speaking, it has almost all the bonus points: AI concept, star shareholders and large key clients.
Previously, the company planned to raise about 70 billion Australian dollars, corresponding to a valuation as high as 440 billion Australian dollars. To attract investors, Firmus once considered cutting the issue price from 11 Australian dollars to 8.25 Australian dollars, but still failed to get sufficient support.
A few days later, on October 13, AirTrunk, a data center operator under Blackstone, also came out with the news of suspending its Singapore REIT listing plan.
Compared with Firmus, AirTrunk has a much more mature business. Back in 2024, Blackstone acquired this company with an enterprise value of more than 240 billion Australian dollars, and its data centers already have more than 800MW of customer committed capacity.
Even so, AirTrunk's listing deal originally planned to raise about 1.5 billion US dollars is still likely to be delayed to 2027.
What is more noteworthy is that this change has been transmitted along the AI industrial chain to the energy sector.
On September 17, US nuclear power enterprise Holtec announced the delay of its IPO, and officially withdrew its listing application on September 25.
Holtec directly mentioned in its statement that the recent nuclear energy sector has encountered adverse market environment, and one of the important reasons is the uncertainty of the prospect of AI data center construction.
From smart hardware to computing power infrastructure, then to data centers and nuclear power, these companies have very different businesses, but they have encountered listing resistance almost at the same time. Behind this, a noteworthy change is reflected:
The secondary market is becoming more cautious about the valuation of AI assets.
This scene also appeared 26 years ago during the dot-com bubble period.
On March 10, 2000, the Nasdaq Composite Index hit an intraday high of about 5132 points, and then began to fall continuously.
A month later, a large-scale wave of IPO withdrawals suddenly appeared in the US IPO market.
On April 19, 2000, Wired published a report titled "More Delays in IPO Land". Among the 18 companies that were originally scheduled to go public that week, only one completed the issuance as planned by the time the report was released.
Among them was AltaVista, one of the most well-known Internet search engines at that time.
In 1999, when CMGI, an Internet investment company, acquired most of the equity of this company, the transaction consideration was about 2.3 billion US dollars. In April 2000, AltaVista originally planned to raise 280 million US dollars through IPO.
How popular was AltaVista at that time?
According to data from Media Metrix, an Internet traffic monitoring agency, in December 2000, AltaVista still had about 19 million unique visitors, ranking 11th among the most visited websites in the United States.
In addition to search, it also had a very popular translation product called Babelfish, which processed more than 1 million translation requests every day.
But even such an Internet star enterprise with a huge user base failed to catch the last train of IPO.
In April 2000, on the eve of the official issuance, Nasdaq began to plummet, and AltaVista suddenly announced the delay of its listing. After that, with the continuous burst of the dot-com bubble, this search giant finally failed to successfully land on the capital market.
AltaVista is not an isolated case.
At that time, Internet companies such as Coolsavings and Yupi Internet successively delayed their IPOs, and even the most sought-after Internet infrastructure enterprises by capital were forced to cut prices.
For example, 360networks, which built transnational optical fiber networks, originally planned to raise 860 million US dollars, but later had to reduce the target financing scale to about 600 million US dollars to complete the issuance.
This change then spread rapidly.
According to the statistics of the IPO market at that time, in the first quarter of 2000, there were only 20 IPO withdrawals or extensions in the United States, and in the second quarter, this number suddenly increased to 85. The number of enterprises that lowered their issue price range also increased from 8 to 32.
It is worth mentioning that the 2000 IPO withdrawal wave occurred after Nasdaq peaked and began to plummet.
In this round, AI assets obviously have not reached that stage yet. But at least for some AI assets, the high valuation expectation of the primary market has begun to diverge from the pricing of secondary market investors.
/ 02 / The premium for long-term growth has disappeared
Behind this divergence, there are two main reasons.
First, the valuation dividend of AI has been cashed in advance by the primary market.
In the past few years, a very obvious trend in the global investment and financing market is that the steepest part of the valuation rise of technology companies is increasingly taking place before listing.
There are two sets of data worthy of attention.
In the US private market report released by Cambridge Associates in July 2026, it was disclosed that in 2025, the return rate of the US venture capital index reached 21.1%, hitting the best performance since 2021.
But on the other hand, data from Renaissance Capital shows that for technology companies listed in the US in 2025, calculated from the issue price to the closing price on December 17, the average return was -7.3%.
Even if we only look at tech IPOs with a financing scale of more than 100 million US dollars, only about a quarter of the enterprises still have a price higher than the issue price by the end of the year.
Of course, the statistical calibers of these two sets of data are not completely consistent, but the market contrast they reflect is still worthy of attention.
In the past, IPO was often an important starting point for the value growth of technology companies. But today, more and more star technology companies have completed most of their valuation expansion in the private market.
In the AI field, this trend is particularly obvious.
In September 2025, Firmus' private placement valuation was only 1.85 billion Australian dollars. By August 2026, with the participation of institutions such as NVIDIA and Blackstone in the financing, its valuation quickly climbed to about 15 billion Australian dollars.
But only two months later, Firmus proposed a valuation of 44 billion Australian dollars in its IPO. That is to say, in just one year, Firmus' valuation soared by nearly 23 times.
Even if the company later considered cutting the issue price by 25%, the corresponding valuation still reached 33 billion Australian dollars, which is more than twice the valuation of the previous round of private placement.
Oura is no less impressive. At the end of 2024, Oura's private placement valuation was about 5.2 billion US dollars. In October 2025, this figure rose to 11 billion US dollars. When planning for this IPO, the company hoped to raise the valuation to 15.6 billion US dollars again.
In less than two years, the valuation has increased by about twice.
This means that for these enterprises, multiple rounds of financing before listing have completed a considerable part of valuation expansion.
When the primary market has cashed in the valuation dividends for the next few years in advance, the potential return space left for secondary market investors will naturally be squeezed.
Second, the volatility of AI assets has intensified, and the secondary market has begun to re-examine the value of long-term growth.
In the second quarter of 2026, driven by the rebound of tech stocks and the AI investment boom, the Renaissance IPO ETF surged by 42%. The strong market performance also made many companies preparing for listing raise their expectations for the issue price.
But entering the third quarter, with the intensification of market volatility, investors began to demand that valuations truly match the revenue structure, profitability and capital investment.
Oura is a typical case. According to the previously drafted issue range, Oura's corresponding valuation is about 12.8 billion to 15.6 billion US dollars, equivalent to about 9 to 11 times its revenue in the past 12 months.
Such a valuation is not uncommon for a fast-growing software company.
But Oura's actual revenue structure is still highly dependent on hardware sales.
The prospectus shows that in the nine months ending June 2026, Oura's subscription revenue was about 240 million US dollars, accounting for about 20% of the total revenue, and the remaining 80% mainly came from smart ring sales.
This means that although Oura has built a subscription business, it is still an enterprise dominated by hardware sales on the whole.
Hardware and software usually correspond to two different sets of valuation logics in the capital market.
Software subscription usually has strong revenue predictability and economies of scale, while hardware needs to continuously bear the costs of manufacturing, inventory management and product iteration. This is also the core reason for Oura's valuation divergence.
Firmus is also facing this test.
Although Firmus has proposed an AI data center construction plan with a capacity of up to 1GW, according to data from Reuters Breakingviews, its actual operational capacity at that time was only 42MW, less than 5% of the target scale.
In other words, more than 95% of the planned capacity has not been put into operation.
This means that if investors buy in at the proposed IPO valuation of 44 billion Australian dollars, they are largely paying in advance for the company's construction and growth in the next few years.
Not only that, to actually complete the construction of the planned data centers, Firmus also needs to continuously raise huge amounts of capital.
Lochlan Holloway, a strategist at Morningstar, believes that according to the company's forecast, after all the data centers are completed, Firmus' debt may reach 300 billion US dollars, about 6 times its forecast operating profit in 2028.
For an enterprise with a small actual operating scale, investors not only need to believe that the demand for AI computing power can continue to grow, but also need to believe that the company can build the data centers as planned, obtain financing, and finally achieve the expected profit.
If any link goes wrong, it may affect the final investment return.
The valuation divergence between Oura and Firmus, to a certain extent, reflects that the market's concern about risks has begun to outweigh the fear of missing out on AI opportunities.
/ 03 / The interest rate hike cycle is also exerting pressure
In addition to market volatility, the rise in interest rates has further amplified this contradiction.
On September 16, the Federal Reserve announced a 25 basis point interest rate hike, raising the target range of the federal funds rate to 3.75%-4.00%.
For AI enterprises that rely on long-term growth, the rise in interest rates means twofold pressure.
On the one hand, the increase in the risk-free rate and the market-required rate of return will lower the present value of future cash flows. The more an enterprise relies on profits several years later to support its valuation, the more obvious the impact it usually suffers.
On the other hand, for heavy-asset enterprises such as AI data centers, rising interest rates will also directly increase financing pressure.
Building data centers requires a large amount of upfront capital investment, and enterprises often need to maintain expansion through debt financing. When borrowing costs rise, the originally expected investment returns may also be eroded by increasing interest expenses.
Interestingly, the burst of the dot-com bubble 26 years ago also took place in a round of interest rate hike cycles.
According to the historical data of the Federal Reserve, from June 1999 to May 2000, the Federal Reserve raised interest rates six consecutive times, raising the target federal funds rate from 4.75% to 6.5%, with a cumulative increase of 175 basis points.
The continuously tightening monetary environment raised the cost of capital, and also brought pressure to the Internet enterprises at that time that relied on long-term growth expectations to support high valuations.
Of course, today's AI industry is very different from the Internet in 2000, and the degree of tightening of the Federal Reserve is far from reaching the level of that year. The setbacks of several enterprises in IPO alone are not enough to judge that the entire AI bubble is bursting.
Of course, today's situation is also very different from that in 2000. The setbacks of several enterprises in IPO alone are not enough to judge that the entire AI bubble is bursting.
But the successive cold reception of AI asset IPOs has also exposed an important change:
The industrial growth of AI may be far from over, but the growth premium that the capital market is willing to pay in advance has begun to shrink.
This article is from the WeChat Official Account "Silicon-based Observation Pro", written by Aqi, and published with authorization from 36Kr.