OpenAI's revenue forecast has shrunk, while Manus has raised 500 million US dollars: the trend of the AI track has changed
Recently, the tech industry has witnessed a highly dramatic scenario of starkly contrasting fortunes.
On the other side of the Pacific, OpenAI disclosed that its annualized revenue is close to 50 billion US dollars, around 20 billion US dollars less than the nearly 70 billion US dollars previously cited by the market. The news immediately sparked panic that the AI bubble might burst: the Nasdaq fell 1.25%, the Philadelphia Semiconductor Index dropped 3.39%, and the AI sector of the Hong Kong stock market suffered a collective sharp slump.
While in China, AI Agent company Manus officially announced the completion of a new round of financing of over 500 million US dollars. Boyu Capital and IDG Capital led the investment, while Tencent and HSG continued to increase their holdings. Its post-money valuation is about 4 billion US dollars, doubling compared with the acquisition price by Meta, marking a highlight moment for the company.
On one side is the global panic that AI cannot make profits, on the other side is the capital carnival with doubled valuation. This sharp contrast reveals the most authentic profile of the current AI industry: the faith in large models is ebbing, while the real tangible value of the application layer is being re-priced.
18-month Roller Coaster: From Acquisition by Tech Giants to Regulatory Reshaping
The 18-month experience of Manus can be regarded as a dramatic commercial blockbuster.
In March 2025, Manus emerged as the "world's first general-purpose AI Agent" with a dominant posture. Its visits exceeded 10 million within 4 hours after launch, and the internal test invitation code was speculated to be sold for tens of thousands of yuan. In just 8 months, its ARR (Annual Recurring Revenue) exceeded 100 million US dollars.
Capital always has the sharpest sense of smell. In December 2025, Meta announced the acquisition of Manus for more than 2 billion US dollars, setting its third-largest acquisition record in history. Xiao Hong, the founder, was proposed to be appointed as Meta's vice president, which seemed to be a perfect story of "starting a business in China and cashing out in the United States".
But the turning point came in April this year. The Office of the Work Mechanism for Security Review of Foreign Investment of the National Development and Reform Commission issued a ban, stopping the transaction. This is the first prohibition order issued by China in the AI sector against foreign acquisition since the implementation of the "Measures for the Security Review of Foreign Investment".
The logic of supervision is clear and firm: the core technology is developed within the territory of China, product training relies on data within the territory of China, and attempts to evade supervision through "domestic R&D + overseas relocation + foreign acquisition" are obviously not allowed.
Subsequently, a Chinese capital consortium led by Tencent repurchased all the equity of Manus from Meta at a valuation of about 2 billion US dollars, becoming the largest single shareholder. On September 1, Manus officially announced the resumption of independent operation. This regulatory intervention not only retained a star company, but also unexpectedly built a very high competitive barrier for Manus. Under the background of the game of AI sovereignty, this barrier is more valuable than any technical patent.
Product Hidden Card: Underlying Reconstruction from Usable to User-friendly
After resuming independence, Manus did not rest on its past laurels. Manus 2.0 released on September 28 shows its ambition at the product level.
The first is the reconstruction of the underlying framework. The new self-developed Agent framework Cascade reduces Token consumption by 23.2%, shortens task completion time by 28.2%, and cuts operating costs by 32%. In the Agent track, efficiency means profit, and these three figures directly respond to the market's doubts about Agent's money-burning situation.
The second is the expansion of scenarios. The desktop application is upgraded to Manus Studio, covering all scenarios including documents, spreadsheets, PDFs, slides, websites, codes, games, videos and more. It is no longer a simple dialog box, but a shared workspace for humans and AI.
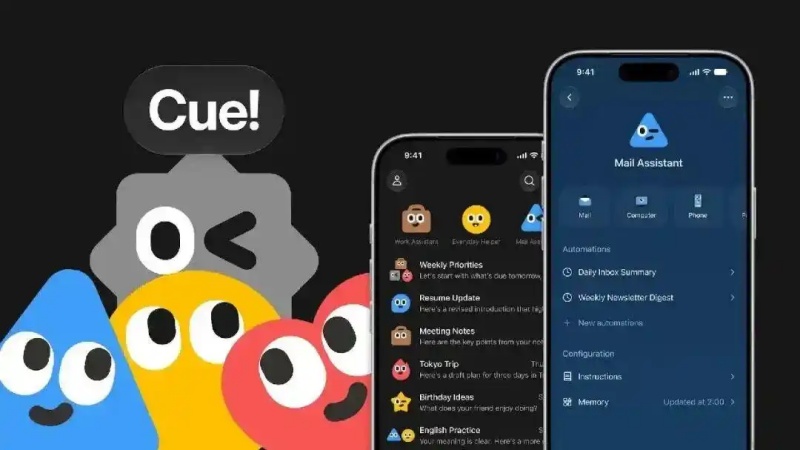
The most noteworthy is the launch of the personal agent Cue. Each Cue has an independent email, phone number, wallet and computer, which can send external messages, make payments within the budget, answer calls for users, and multiple Agents can also work in teams. This marks that Manus has officially entered the Personal Agent track, extending from B-end tools to C-end life scenarios.
By the way, Manus's architecture remains "large model + cloud virtual machine". It does not develop underlying large models by itself, but integrates third-party capabilities such as OpenAI GPT-4 and Anthropic Claude. As of early December 2025, it has processed more than 147 trillion tokens and created more than 80 million virtual computers.
This strategy of "not building wheels, but building cars" has become a pragmatic survival wisdom at the moment when competition at the model layer is white-hot.
Three Logics Behind Manus's Counter-cyclical Financing
The Agent track is cooling down. There were 83 financing deals in the first half of this year, with a year-on-year increase of 131%. The popularity dropped sharply in the second half of the year, and VC enthusiasm turned to embodied intelligence and AI4S (artificial intelligence for scientific research). Vibe Coding lowered the application threshold, and the pessimistic argument that "large models will swallow all applications" spread, and Manus's monthly visits also dropped from 28 million to 23 million.
So the question arises, under this background, why can Manus get 500 million US dollars of financing against the trend? There are three reasons:
First, ARR has proved its commercialization capability. The ARR that exceeded 100 million US dollars in 8 months is not a number on the PPT, but verification of real tangible revenue. In the panic that the AI bubble may burst, profitable companies always enjoy a premium.
Second, the regulatory barrier has unexpectedly become a moat. With Tencent's underwriting and the principle of Chinese jurisdiction, Manus has obtained unique competitive advantages in the domestic market. At a time when data security is increasingly sensitive, this inherently compliant identity is more effective than any marketing.
Third, the product iteration speed is still accelerating. From the Cascade framework of Manus 2.0 to the launch of Cue, Manus has proved that it is not a flash-in-the-pan marketing product, but a product team with continuous evolution capabilities. At the application layer, iteration speed is the lifeline!
To put it bluntly, when overseas markets re-evaluate the value of the model layer, Manus's 500 million US dollar financing has become a landmark case in China's AI application track, representing a change in the capital consensus of China's primary market: compared with re-investing huge sums of money to train a general-purpose basic large model, AI applications that can directly face users, solve real work pain points and generate continuous revenue are more worthy of betting.
Three Major Challenges for Manus to Overcome
Of course, while enjoying the capital carnival, Manus must always stay sober, because there are three major challenges lying ahead:
The first is the dimensionality reduction strike from large model companies. Kimi from Moonshot AI, Claude from Anthropic, and Codex from OpenAI all have built-in Agent capabilities. When the underlying model directly provides Agent services, the living space of the middle layer will be sharply compressed. What's more, products from large manufacturers such as Tencent WorkBuddy and ByteDance Trae IDE are also eyeing covetously.
The second is the winner-takes-all situation in the Personal Agent track. In the personal assistant track that Cue enters, there are many competitors such as Muse, Kimi, Today AI and others. This track is characterized by extremely high user stickiness and high switching cost. Once ecological lock-in is formed, it is very difficult for latecomers to break through.
The third is the pressure of the profit schedule. The 500 million US dollar financing is not the end, but the starting point of a new round of capital expenditure. Before the capital market's patience runs out, Manus must prove that it can generate sustainable revenue. It should be noted that the lessons of OpenAI, which bears more than 600 billion US dollars of computing power procurement commitments and has postponed its IPO to 2027, are right in front of us.
Industry Resource Reallocation After the Fade of AI Frenzy
Back to the contrast at the beginning. The panic caused by OpenAI's revenue shrinkage is essentially the market's disenchantment with the faith in the model layer. Manus's counter-cyclical financing is the re-pricing of the application layer's verified value by capital. This is not the continuation of the AI bubble, but the reallocation of capital resources to the real value side after the AI narrative ebbs. In the past two years, capital has poured into the model layer frantically, betting on who will be the first to make AGI. Now, the game has entered the second half, and capital begins to ask: Who can make money with AGI?
What Manus represents is the certainty that head application layer players can indeed make profits after a round of clearance. Its 4 billion US dollar valuation is not a faith premium for general-purpose AI, but a rational pricing for ARR + regulatory barrier + product iteration. Others are panicking, while Chinese investors are placing bets. It is not just a bet on Manus alone, but a bet on the historical inflection point of the AI industry's transformation from technology-driven to business-driven.
At this inflection point, the ones that can survive are not the ones who shout the loudest slogans, but the ones who do the work best. In the long run, the model layer and the application layer are not mutually exclusive competitive relationships, but complement each other. The continuous iteration of the underlying model reduces the reasoning cost, which can provide more living space for the application layer; the massive real scenario data and user feedback from the application end in turn continuously feed back the optimization of the underlying model.
The profit distribution pattern of the AI industry in the future will most likely be reshaped: the profit of model manufacturers that simply burn money will continue to be under pressure, while AI application enterprises that truly grasp customer pain points, build product barriers and complete commercial closed loops will get a larger share of value. What do you think?
This article is from the WeChat official account "Gong Jinhui", authorized by 36Kr for release.