More and more Hilton hotels with room rates of just over 200 yuan are opening up in growing numbers.
This Hilton Is Not That Hilton
The three characters "Hilton" were once a byword for luxury.
In 1988, Hilton entered China, with its first store located on Huashan Road, Shanghai. It is said that the opening ceremony alone cost 800,000 US dollars and lasted for three full days; the guest rooms were full of overseas distinguished guests, and dozens of imported fruits were displayed at the banquets. Now 38 years later, the Hilton of today is no longer the Hilton of the past.
Before the Mid-Autumn Festival holiday, Wang Qi, a post-90s white-collar worker, planned a trip to Qingzhou, Shandong. When she opened the hotel booking app, in addition to familiar brands like Ji, Atour and Orange, a "Hampton by Hilton" also popped up. It has a great location close to the ancient Qingzhou City. The superior king room on the day of Mid-Autumn Festival only costs 296 yuan per night, including two breakfasts. By comparison, the same room type at Ji without breakfast costs 298 yuan, and the price with two breakfasts is 376 yuan.
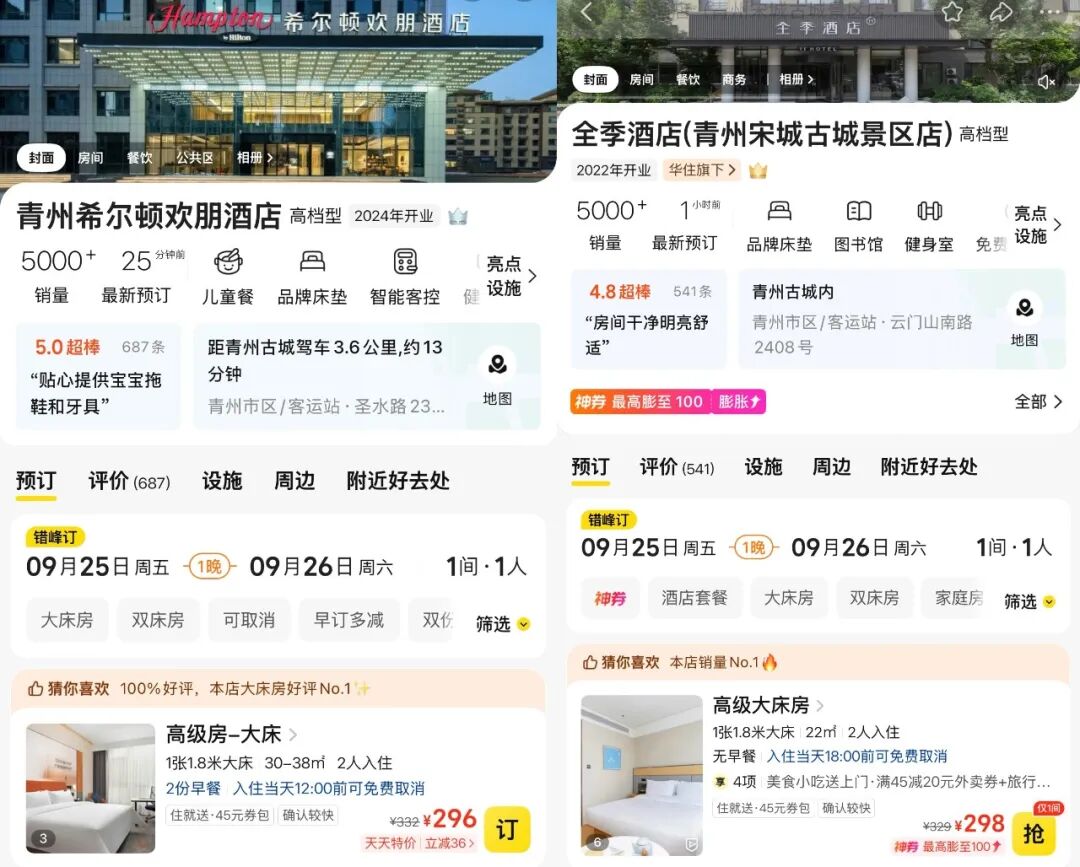
Source/Screenshot from a booking platform
"There is even a Hilton in a small county town?" "Does it have to compete with Ji for guests by low prices?" Two questions popped up in Wang Qi's mind. Then came the third one — could this be a fake Hilton?
Gao Min had the same doubt. During this year's May Day holiday, she traveled to Xingtai, Hebei, and booked a Hilton Garden Inn on Fliggy. The room rate for one night was only 241.58 yuan, much cheaper than Atour and Ji. She thought she had got a bargain, but was greatly disappointed after check-in. "Not only the breakfast options were limited, but the elevator was extremely small, and you had to wait for a long time every time you took it."
"Although it is labeled as Hilton, this Hilton is not the one you think of, it is just an ordinary hotel." Gao Min said frankly to *Caijing Tianxia*. The core reason why Hilton is Hilton lies in its excellent hotel facilities, magnificent lobbies, spacious elevators, standard bathtubs, not to mention the high-quality service. The Hilton she stayed at obviously did not meet those standards.
In July this year, Qian Yu stayed at a Home2 Suites by Hilton in Hohhot, and the experience was also unsatisfactory. The room was very small with loud noise, the elevator had to be waited for more than 2 minutes during peak hours, and you had to queue for breakfast. More importantly, the hygiene was substandard, there were hairs on the bed. Qian Yu said helplessly: "I feel like I stayed at a fake Hilton, and I never want to stay at such a hotel again."
The Hilton-branded hotels that Wang Qi, Gao Min and Qian Yu stayed at are actually not the same as the five-star Hilton that the public perceives. Experienced guests usually classify them into the same category as Ji and Atour, without holding too high expectations.
Take Hampton by Hilton as an example. Hilton only provides the brand, responsible for outputting standards and the membership system. From development and preparation, supply chain to daily operation, all are managed by Jin Jiang Group, which is commonly known as the "hybrid model" in the industry.
Hilton Garden Inn and Home2 Suites by Hilton follow a similar model. The former was originally Hilton's "own brand", but after the franchise model was launched in 2021, the daily operation of newly opened hotels was directly handed over to the property owners. The latter is the product of the "hybrid" cooperation between Hilton and Phoenix Hotels & Resorts under Country Garden.
Relying on Hampton by Hilton, Hilton Garden Inn and Home2 Suites by Hilton, Hilton has achieved remarkable results in rapid expansion across China. In August, Hilton announced that the number of hotels operating in the Greater China region has exceeded 1,100, among which Hampton by Hilton accounts for 550, nearly half of the total.
Along with the expansion of the number of stores, there is also the public's disenchantment with the word "Hilton".
Some people booked hotels just for the name "Hilton", expecting high-standard services, only to find that it was just like an ordinary hotel after check-in. "The bottled water in the rooms of Atour and Ji is at least Nongfu Spring, but Hilton uses C'estbon, I feel like I stayed at a fake five-star hotel." "It says there is a bar, but it's just an empty counter, which automatically turns off the lights at 9:30 p.m. I really can't tell if it's Hampton or seeing off guests."
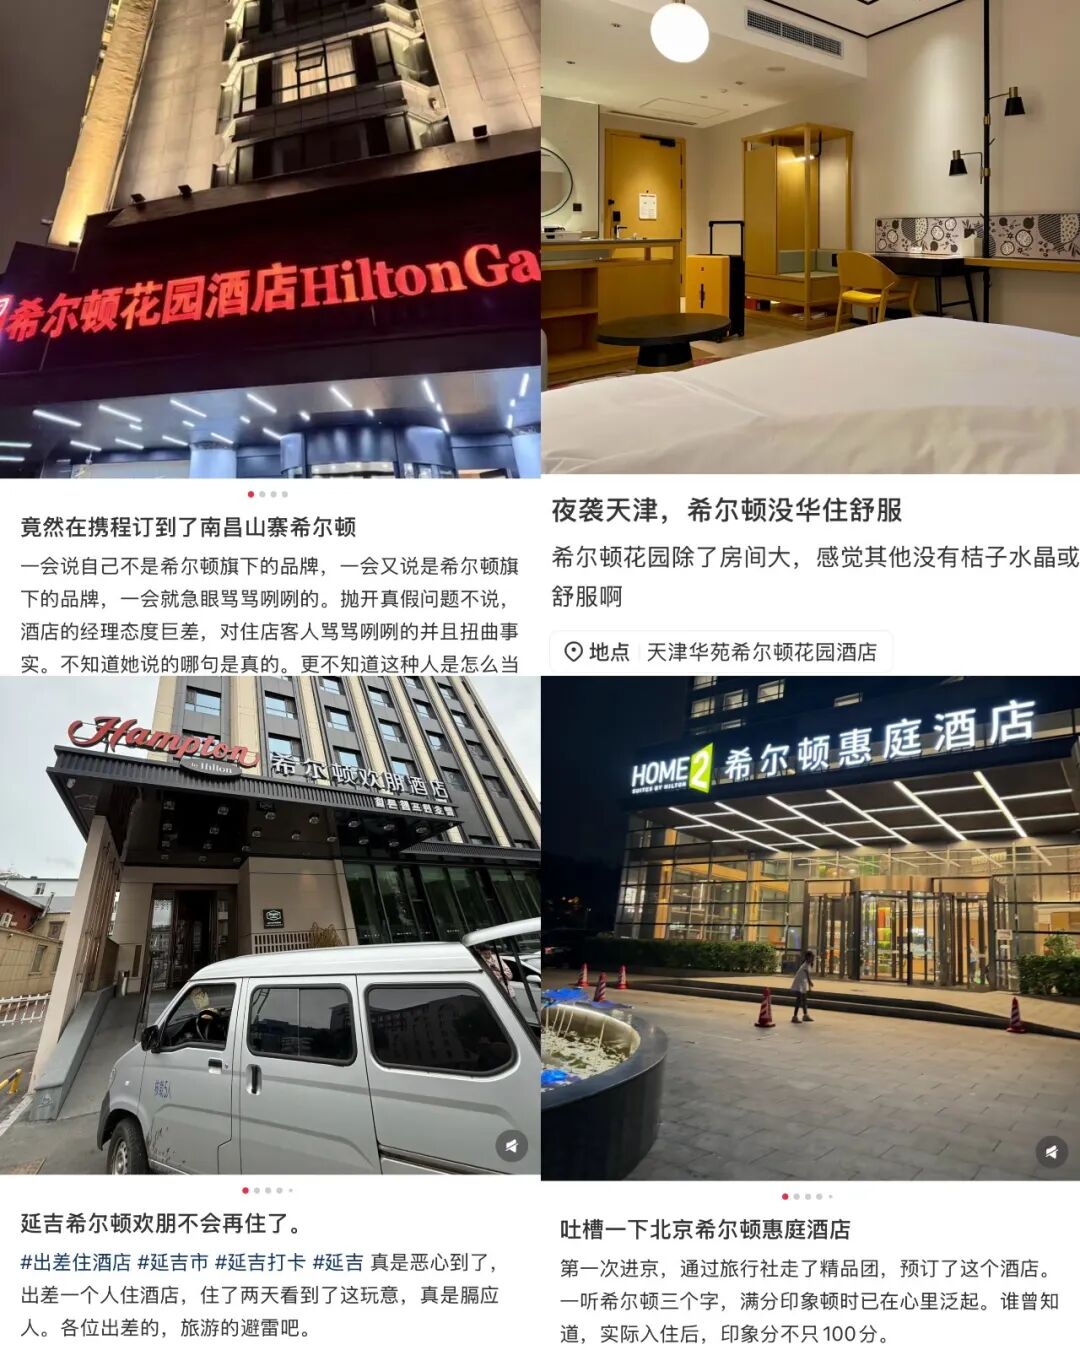
Source/Xiaohongshu
Some other guests stayed at a Hilton Garden Inn in Shanghai, and found that the TV had no screen casting function, and the socket at the bedside was loose and could not be used for charging. What's more notable are those inconspicuous details: the disposable slippers are visibly thin, and there are no welcome fruits at all.
After the huge gap between expectation and reality, some people shared their experiences on social media, saying that "you get what you pay for" and reminding other netizens to be careful. Later, Gao Min stayed at a Hilton in Zhuhai, which was a completely different experience. Before she arrived at the hotel, the housekeeper had communicated with her about all the details in advance. Although the price of 800 yuan per night was a bit high, the view was very good, facing the Macau Tower, and someone helped her carry the luggage as soon as she got off the car.
The Product of Mid-tier Hotel Competition
The widespread presence of Hilton-branded hotels across China is actually the result of Hilton sinking into the Chinese market.
Looking back at the development history of China's hotel industry, 2014 was a landmark year. In this year, local groups and foreign giants all set their sights on the same mid-tier "cake".
On the one hand, after more than 10 years of rapid expansion, economy hotels have become saturated, and the price war has eroded almost all profits. In order to find new growth points, many franchisees opened stores in fourth- and fifth-tier cities, only to find that the room rates cannot be raised at all. On the other hand, affected by relevant policies, the demand for government consumption dropped sharply, and five-star hotels also faced excess stock.
Coupled with the data support from McKinsey — the potential consumer group of China's mid-tier hotel market is expected to continue to expand at an annual growth rate of about 10%, the entire industry has reached a consensus tacitly: the one that wins the mid-tier market wins the whole market.
It was in this year, under such a background, that Hampton by Hilton was introduced into China.
In the past, foreign high-star hotels in China mostly controlled their operations in person. But in the mid-tier market, this set of tactics failed. The competition for mid-tier hotels lies in who expands faster, who controls costs lower, and who better understands the needs of local franchisees. These are exactly the strengths of local hotel groups. As a result, foreign giants all changed their tactics: "lease" out the brand, and step back to the backstage to collect management fees.
At that time, a senior executive of Hilton Group said that the cooperation with Plateno (later acquired by Jin Jiang) was finalized within one month, and the Hampton by Hilton brand was launched three months later.
The advantage of this "hybrid" model first lies in its fast expansion speed. Originally, international hotel brands needed multi-level internal approval for franchisee review, but through cooperation with Plateno, Hilton Group fully transferred the decision-making power, which greatly shortened the cycle from site selection to contract signing for franchise stores.
In December 2015, the first Hampton by Hilton opened in Sanya. In less than 3 years, the total number of stores exceeded 50. After that, Hampton by Hilton took 6 years to increase the number of stores by 8 times, exceeding 400.
In order to compete for franchisees with local brands, the model of Hampton by Hilton is more asset-light. Heavy supporting facilities such as banquet halls, executive lounges and all-day dining restaurants are greatly streamlined, only retaining the core accommodation function. The saved area and construction cost reduce the pressure on franchisees, and also leave room for lower room rates.
In 2019, Wang Wei, then president of Hampton by Hilton, revealed that the construction cost per room of Hampton by Hilton was 150,000 to 200,000 yuan. In 2025, after multiple product iterations, the construction cost of the new generation of products is about 170,000 yuan. Although it is still slightly higher than Atour and Ji, with the brand name of "Hilton" and the member introduction from Hilton Group, it can always attract some franchisees to join.
Even saving time for franchisees has become a bargaining chip in the competition. Hilton Garden Inn once stated that through comprehensive modular and standardized design, the hotel preparation time can be minimized, ensuring that the owners complete all design and preparation work within 6 to 8 months.
In this whole set of logic of competing for the mid-tier market, cost control, franchisee interests and scale growth rate are the key points. Whether it can bring high-end experience to consumers is not in the priority sequence of this logic.
A New Round of Rapid Expansion
Of course, this is not the only choice made by Hilton.
Over the past 10 years, from Accor, Marriott to Hyatt, almost every well-known international luxury hotel group has found local "partners" in the Chinese market to enter the market in a similar way.
In 2014, Accor and Huazhu signed a strategic alliance. According to the agreement, Huazhu will become the exclusive master franchisee of Accor in China and Mongolia, responsible for the operation and development of Accor's brands including Grand Mercure, Novotel and Mercure.
In 2016, Marriott signed a contract with Dongcheng Group, transferring the development and management rights of its mid-tier brand "Fairfield" in China (excluding Hong Kong, Macao and Taiwan) to Dongcheng. In terms of specific cooperation mode, Marriott outputs the brand and controls the standards, while Dongcheng is responsible for development and management, and the two sides' reservation systems and membership systems are connected and shared.
Hyatt has more tactics. In 2018, it first authorized Mingyu Hotels & Resorts as a partner company, focusing on managing two brands: Hyatt Place and Hyatt House. In 2019, Hyatt established a joint venture with BTG to launch a new brand "UrCove".
Although the specific cooperation models of different brands are different, the underlying logic is highly consistent: international groups are responsible for outputting brand IP and standards, while local partners provide franchisee networks, property resources and localized operation capabilities. One side pursues scale expansion, the other earns brand premium, and both get what they need.
However, due to the obvious differences in authorization tightness and the capabilities of partners, the results of this collective bet are uneven.
Brands such as Fairfield and UrCove did not expand rapidly as expected. Only 3 years later, the cooperation between Marriott and Dongcheng was terminated in advance. An interesting detail is that in 2025, Marriott directly followed Hilton's example and added "Marriott" directly in front of Fairfield, trying to use the aura of the parent brand Marriott to endow this mid-tier brand with extra appeal.
Hilton has achieved large-scale expansion, but on the other side of the coin, the gold content of its parent brand is constantly being diluted.
For international brands, China's mid-tier market is still a highly attractive market. Not long ago, the vice president of InterContinental Group publicly stated that stratification has emerged in China's hotel consumer market. The silver economy, intergenerational wealth inheritance of Gen Z, and the county market opportunities brought by urbanization together constitute the driving force for the growth of mid-tier hotels.
All parties have set off a new round of rapid expansion, competing for this mid-tier cake.
According to media statistics, since 2026, from Marriott's Four Points Select to Hyatt's Hyatt Junlin, from InterContinental's Garner to Hilton's Motto, four new international hotel brands have been intensively launched in China. Extending the timeline a little, 13 brands have entered China successively in the past year and a half, almost all targeting the "mid-to-high end select service" segment.
At the same time, in the sinking market, it is increasingly common to see Hampton by Hilton and Marriott Fairfield competing for the same location. The focus of store opening for Hampton by Hilton and Hilton Garden Inn is also shifting from the core areas of first- and second-tier cities to transportation hubs and new districts in third- and fourth-tier cities.
Behind the bustling rapid expansion, there is still the same unsolved problem.
International groups want to use the reputation of their parent brands to obtain scale in the sinking market, but the more stores there are, the closer the room rate is to local chain brands, the easier it is for the originally lofty brand filter to wear off. Franchisees want the premium brought by the international brand name, but eventually they are drawn into the price war with Ji and Atour. Consumers book hotels for the familiar brand name, but often find a gap between expectation and reality after check-in.
After all, you get what you pay for. The so-called brand premium, when it can be supported by actual experience, is called a brand; when it cannot be supported, there is nothing left but the premium itself.
(The names Wang Qi, Gao Min and Qian Yu in the text are all pseudonyms.)
This article is from the WeChat Official Account "Cai Tian COVER", author: Caijing Tianxia, published with authorization from 36Kr.