August Asia (China) Long-Term Rental Apartment Development Report
Overview of the Asian (China) Long-term Rental Apartment Market in August
01 Global Development Trends of the Apartment Market
In August, according to the monitoring data from the Asian Hospitality Big Data Research Institute, after the global housing rental market experienced the demand peak of summer relocation and graduation season, it presented an operating state of "high consolidation/slight month-on-month rise, steady bottoming out compared with the same period of last year, and obvious regional differentiation".
In the United States, the rental market is characterized by "slight overall recovery, obvious regional differentiation, and emerging structural inflection points". According to the Zillow Observed Rent Index (ZORI), the typical monthly rent across the United States in August was $1,948, up 0.2% month-on-month and 2.5% year-on-year. The single-family home rental market performed strongly, with the average listed rent remaining at a historically high level (approximately $2,246 per month). In August, under the Federal Reserve's interest rate policy, the 30-year mortgage rate still remained at a high level above 6.5%. The high housing purchase cost and monthly mortgage burden (the median monthly housing purchase payment across the US is about $1,897) have blocked a large number of potential buyers from the housing market, forcing them to stay in the rental market, which provides solid demand support for the rental market. The typical rent in San Francisco in August was $3,409, up 10.8% year-on-year, rebounded strongly, becoming one of the gateway cities with the fastest rent growth in the United States. The typical rent in San Jose in August was $3,815, up 7.6% year-on-year, and the typical rent in Chicago in August was $2,210, up 4.9% year-on-year. As the core representative of the central and western regions, it has high cost performance and no excess new supply, rising steadily.
In Italy, the residential rental market maintains high-level operation, showing an overall development trend of "slight increase in the national average price, differentiation and adjustment in core metropolises". According to data from Immobiliare.it, the average listed rent of residential properties nationwide is 15.02 (EUR/㎡/month), up 4.38% over the same period. The average price in Milan in August is 23.0 - 24.5 (EUR/㎡/month), which is still the city with the highest rent in the whole country. The high living cost has prompted some young white-collar workers and students to flow to surrounding satellite cities (such as Monza). The average price in Florence in August is 21.7 (EUR/㎡/month), ranking the second highest in the country, but there is a slight correction in both single month and year-on-year (the month-on-month decrease is about 3.1%), which is mainly due to the release of short-term rental supply at the end of the peak tourist season and the impact of policy supervision. The average price in Turin in August is 13.1 (EUR/㎡/month), with a month-on-month increase of 1.3%, reaching 13.1 (EUR/㎡/month). With relatively moderate living costs and high-quality university resources, it has absorbed a large number of college students and young people overflowing from Milan.
In the UK, the rental market presents an operating trend of "steady rise, slowing growth, and structural tension between supply and demand". According to data released by the Office for National Statistics, the average monthly rent across the UK in August was £1,382, up 4.1% year-on-year. The average monthly rent in London is £2,238, which is still the region with the highest rent and strong growth, up 1.4% month-on-month and 5.1% year-on-year. The concentrated return of international students, financial and technology practitioners has pushed the rent of high-quality apartments in the core area and Zone 1-2 to continue to rise. The average monthly rent in Manchester / Liverpool is £1,117. Core cities such as Manchester and Liverpool continue to absorb commuters and young professionals from high-consumption areas such as London, and the rent maintains a steady growth rate (2.4% annual increase). The average monthly rent in Scotland (Edinburgh/Glasgow) is £1,064. Driven by the Edinburgh Art Festival and the start of the new semester, the demand for rental housing in Edinburgh and Glasgow is extremely strong. The overall monthly rent in Scotland increased by 0.5% month-on-month and 4.2% year-on-year.
02 Development Trends of the Asia-Pacific Rental Market
In Australia, the rental market is characterized by "rent remaining at a historically high level, overall growth slowing down but structural differentiation intensifying". The average weekly rent of residential houses across the country is about $735/week for independent houses (House) (up about 8.1% year-on-year); about $700/week for apartments (Apartment/Unit) (up about 7.7% year-on-year). The proportion of ordinary families' rent expenditure in disposable income remains at a historically high level of about 33%, and the rental burden is still relatively heavy. The median weekly rent of independent houses in Sydney is $800 – $850/week, which is still the most expensive rental market in Australia. The rent of independent houses has hit a record high, but the high affordability has approached the limit, and the month-on-month increase has begun to narrow. The median weekly rent of independent houses in Melbourne is $600/week, which is relatively cost-effective among the large cities on the east coast, but the apartment rent shows a strong momentum of catching up, and the vacancy rate has rebounded but remains tight. The median weekly rent of independent houses in Brisbane is $665 – $680 / week. After the rise in the previous two years, there was a slight month-on-month adjustment (-1.5%) in August, but supported by cross-state immigrants, the overall year-on-year increase is still strong.
In Singapore, the residential rental market as a whole has entered a platform period of "high-level stability and slight rise". The median monthly rent across the island is about S$4,500 – S$4,800. Core Central Region (CCR): covering Orchard Road, Marina Bay, Bukit Timah, Chilin Road, and the core CBD sections of the city center, the rent has stabilized and rebounded. The rental demand for multinational company executives and high-net-worth foreigners has steadily recovered. High-end private residences have strong anti-fall properties, and the monthly rent for two-bedroom units is S$5,200 – S$7,500. Rest of Central Region (RCR): covering Queenstown, Potong Pasir, St. John's, and Marine Parade, the rent is relatively stable / transactions are the most active. Close to the urban area with outstanding cost performance, it is most favored by middle managers and foreign professionals in finance and technology enterprises. The monthly rent for two-bedroom units is S$4,000 – S$5,500. Outside Central Region (OCR): covering Tampines, Yishun, Jurong, Punggol, and Dairy Farm, the rent growth slows down / partial concessions. Due to the concentrated delivery of a large number of new large properties in 2025–2026, rental options have increased, and landlords have greater bargaining power. The monthly rent for two-bedroom units is S$3,200 – S$4,200.
In South Korea, the residential rental market continues the tense situation of "increasing supply shortage, overall rise of Jeonse and Wolse prices, and structural acceleration of monthly rent transformation". The average Jeonse deposit for apartments in Seoul has exceeded 700 million won (about 475,000 US dollars / 3.4 million RMB) for the first time. The cumulative increase in Jeonse deposits for apartments in Seoul from the beginning of the year to August has exceeded 6.3%, which is more than 5 times the growth rate in the same period of 2025. The average monthly rent of apartments in Seoul remains at a high level of 1.6 million – 1.62 million won/month (about 1,200 US dollars/month), with a cumulative increase of nearly 6% since the beginning of the year. For Officetel and Villa (low-rise apartments), the average monthly rent of Officetel nationwide is about 811,000 won/month, of which the average monthly rent in Seoul has climbed to 949,000 won/month (close to the 1 million won mark). The alternative demand in Gyeonggi-do and Incheon is strong, and a large number of young families and white-collar workers who cannot afford the high Jeonse deposit and high monthly rent in Seoul overflow outward. The Jeonse and monthly rent prices of apartments and Officetels along the high-speed railway/subway lines in Gyeonggi-do and Incheon continue to rise. The main wide-area cities in local areas (Daejeon, Ulsan, Busan) are steadily strengthening. The cumulative increase in Jeonse deposits in Ulsan during the year is about 4.1%, and that in Busan is about 2.6%.
03 Development Trends of China's Rental Market
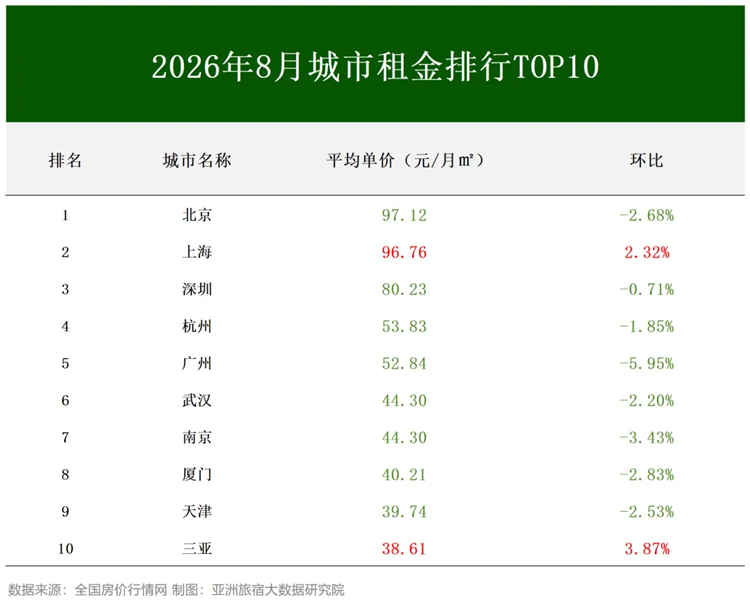
In August, the rents of the top 10 monitored cities saw 2 increases and 8 decreases month-on-month. According to the data from China Housing Price Market Network, the national median rent is 1750 yuan/month, down 2.78% month-on-month. In August, the city with the largest month-on-month decline among the top 10 cities was Guangzhou, with a decline of 5.95%, and the city with the largest increase among the top 10 cities was Sanya, with an increase of 3.87%.
04 Opening Dynamics of Rental Enterprises
The Taoxichuan Ziruli community in Jingdezhen opened. On August 1, the Taoxichuan Ziruli community in Jingdezhen was officially opened. This is a large-scale maker rental community jointly built by Ziroom Asset Management and Taoxichuan Cultural Tourism Group, positioned as "an art settlement in life". The total construction area of the project exceeds 93,000 square meters, with more than 1700 high-quality residences planned. There are various apartment types, including studio (20-65㎡), one-bedroom (48-104㎡), two-bedroom (80-121㎡), three-bedroom (145-156㎡) and other types, to meet different needs such as living alone, sharing with friends, and integrating creation and life.
The Yiming 101 Mansion in Shenzhen opened. On August 10, Shenzhen Yiming 101 Mansion (the mid-to-high-end product line of Boyu) was officially opened. It is positioned as a 5.4-meter high-rise LOFT long-term rental apartment integrating business and residence, mainly targeting young entrepreneurs, freelancers and urban youth. The project covers 38㎡ elegant single room, 55㎡ warm one-bedroom, 55㎡ cozy two-bedroom, and 55㎡/65㎡ Loft apartment types (some are 5.4-meter high-rise duplex), with apartment types ranging from 1 bedroom to 2 bedrooms, and some apartments are equipped with balconies and independent kitchens.
Two projects of Hanyue Apartment opened. On August 17, Hanyue Apartment under Wuhan Urban Construction Group recently launched new housing sources for two projects (Phase II of Menghu Yunzhu in Qiaokou District, Phase II of Tanghu Guanzhu in Economic Development Zone), with a total of 235 units. Hanyue Apartment · Phase II of Menghu Yunzhu has a total of 172 units, with three bedrooms, two living rooms and two bathrooms (125㎡/142㎡), which are hardcover apartments. Hanyue Apartment · Phase II of Tanghu Guanzhu has a total of 63 units, including two-bedroom, three-bedroom (97-137㎡) and 196㎡ spacious four-bedroom units.
The Shanghai Zhangjiang Marriott Executive Apartments opened. On August 26, Shanghai Zhangjiang Marriott Executive Apartments was officially opened. This is the first time the Marriott Executive Apartments brand has landed in Shanghai, and it is also the 13th in Greater China. The project is located at No. 1666 Haike Road, Pudong New Area, Shanghai (the core area of Zhangjiang Science City, adjacent to Zhangjiang Science Gate and Zhangjiang Science Hall), providing a total of 249 serviced apartments, focusing on the medium and long-term living experience of "hotel services + home functions".
The University Town Store of Ronghui · Star Apartment opened. On August 28, the third store of Ronghui · Star Apartment in Hefei, the University Town Store, was officially opened. The University Town Store is the first work after the brand renewal of Ronghui Star Apartment. The project is located in the Feicui Lake University Town block of Hefei. The project provides 42-65㎡ diverse apartment types (covering living alone, couples living together, and friends sharing), with high-quality configurations in the whole house, supporting check-in with luggage.
The Boudin International Apartment on Boyuan Road, Zhongshan, Guangdong opened. In August, Zhongshan Cuiheng Group and the Boudin brand under the Ease Group reached a new cooperation again, and the Boudin International Apartment project will be implemented on Boyuan Road, East District, Zhongshan, Guangdong Province. Boudin is a mid-to-high-end serviced apartment brand under the Ease Group. Combined with the moderate size of the project, this time it did not copy the first store model, but implemented the Boudin International Apartment product line to create a pure mid-to-high-end serviced apartment format, focusing on business travel and medium and short-term living needs.
Two stores of Chengfa Chengji, Phase II of Meilihui and Emerald Park, opened. In August, Chengfa Chengji, the housing rental brand under the Asset Operation Company of Jinan Urban Construction Group, launched two stores, "Phase II of Meilihui" and "Emerald Park". Both stores implement direct rental by state-owned enterprises, providing check-in with luggage and butler services. The project is located in Buildings 16 and 17 of Luneng Meilihui at the intersection of Wangyue Road and Likang Road; Emerald Park is located at the intersection of Huayuan East Road and Yingxiu Road. The two projects implement direct rental by state-owned enterprises, with apartment types covering about 30-123 square meters, equipped with furniture, home appliances and operation services.
CASA Jiasha signed a contract with Tianjin Huayuan Jinhaitong Park. On August 7, the second stop of CASA Jiasha, the new product line of Boyu, the long-term rental apartment brand under Vanke, completed the signing in Tianjin Huayuan Jinhaitong Park, which is expected to be officially launched in September. The project is located in Huayuan Jinhaitong Industrial Park, Xiqing District, Tianjin (Huayuan is a mature industrial and residential block in Tianjin, surrounded by technology enterprises, industrial parks and a large number of office workers).
Ascott China signed a contract with Zengcheng Urban Investment Group. In August, Dongjin Chengkai Company, a directly affiliated enterprise of Zengcheng Urban Investment Group, officially signed a cooperation agreement with Ascott China, injecting high-quality living supporting facilities into the core platform of the headquarters economy in the eastern center of Guangzhou, accurately making up for the shortcomings of regional mid-to-high-end business travel supporting facilities, and meeting the high-end business travel living needs.
05 Market Entry Dynamics of Indemnificatory Rental Housing and Talent Apartments
In August, the overall entry of indemnificatory rental housing and talent apartments across the country showed a trend of "continuous policy optimization, accelerated supply of housing sources, and steady market transition". Combined with the 15th Five-Year Plan, all regions have made remarkable progress in the fundraising of indemnificatory rental housing, talent housing security and financial support.
Vanke Boyu · Future Xingchen · Boyu Yuan'er launched 1488 housing units. On August 8, Vanke Boyu · Future Xingchen · Boyu Yuan'er (Life Science Park Community) signed the contract. The large-scale indemnificatory rental housing community jointly built by Future Science City Group (state-owned enterprise) and Vanke Boyu (market-oriented institution) has been incorporated into the indemnificatory rental housing management system. The project has a total of 1488 hardcover housing units, which are in ready-for-occupancy state, mainly targeting young researchers, enterprise employees around the Life Science Park and the demand for enterprise whole rental.
Anxinju Meifeng Community launched 620 housing units. On August 12, Anxinju Meifeng Community, a key indemnificatory rental housing project in Xiamen, was officially put into use, and the first batch of 620 housing units welcomed young residents to move in. The project is located at No. 1-7 Xingtianli, Tong'an District, Xiamen, with a total construction area of 208,900 square meters. 3664 indemnificatory rental housing units are planned, supporting 6400 square meters of street-side commercial facilities and 1169 motor vehicle parking spaces.
Ningchao · Chaoyu Xianting launched 749 indemnificatory rental housing units. On August