"Black Wednesday" for US Treasuries: four major blows erupt on the same day
A slew of bearish factors converged on a single day, pushing the U.S. Treasury market through its worst one-day selloff in nearly 18 months.
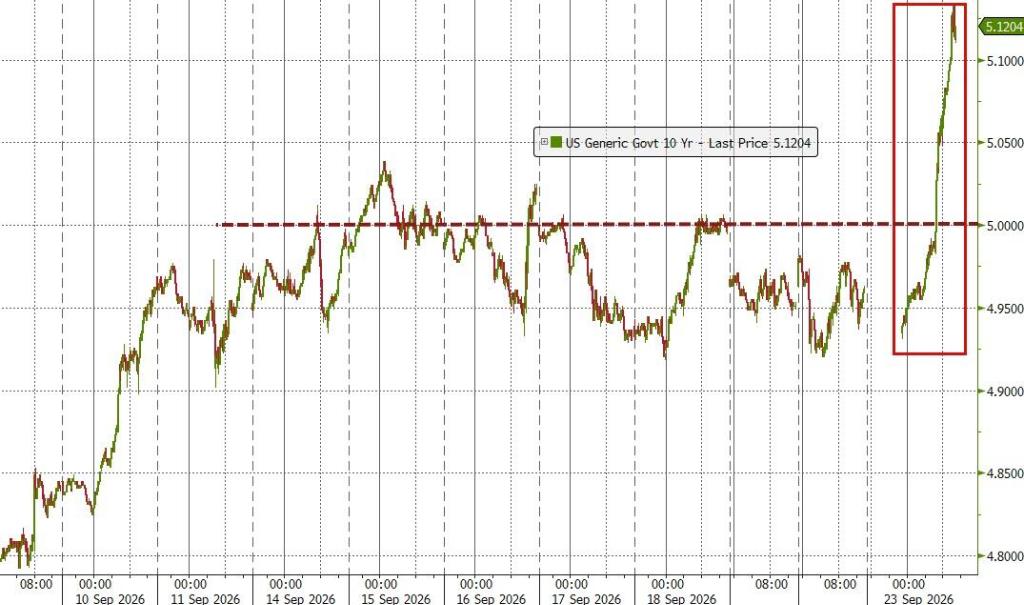
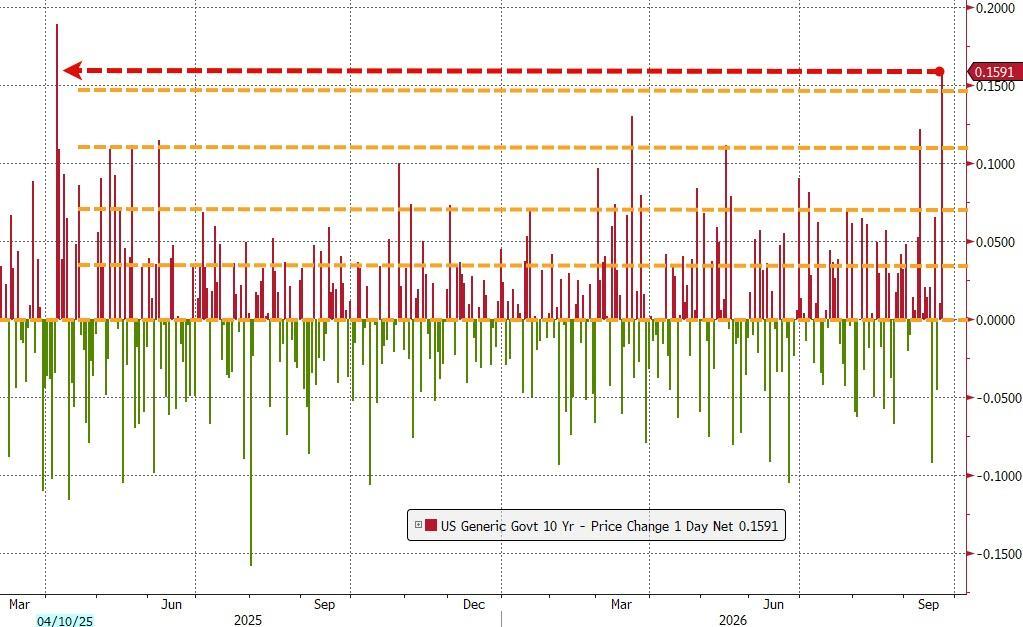
The 10-year U.S. Treasury yield surged by roughly 14 basis points on Wednesday to close at 5.113%, hitting a new high since 2007, marking its biggest one-day jump since the shock of the so-called "reciprocal tariff day" under Trump last April. Market participants described this trend as a "perfect storm" — robust PMI data, rising tensions in the Middle East, hawkish remarks from Federal Reserve officials, and weak Treasury auction results, four major blows landed one after another in the same trading day.
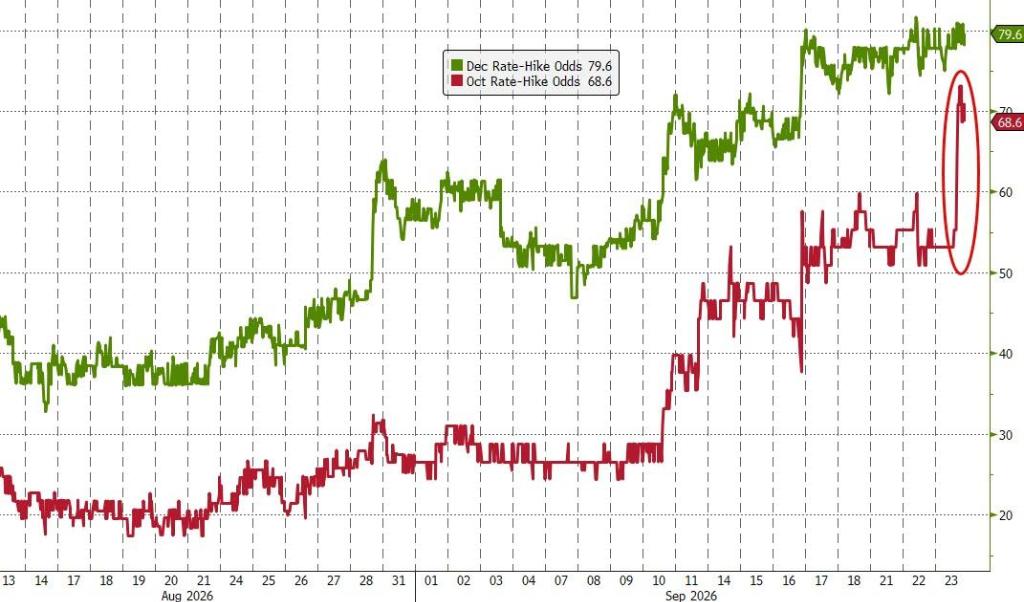
The core signal of this shock is that market bets on another interest rate hike by the Federal Reserve in October have risen sharply. Current pricing in the futures market shows that the probability of a rate hike at the end of October has risen to 68%, just a few days before the U.S. midterm elections. Meanwhile, the swap market has fully priced in expectations of three 25-basis-point rate hikes in the coming year, with significant hedging for a fourth hike. If all are realized, the federal funds rate target range will rise to 4.75% to 5%.
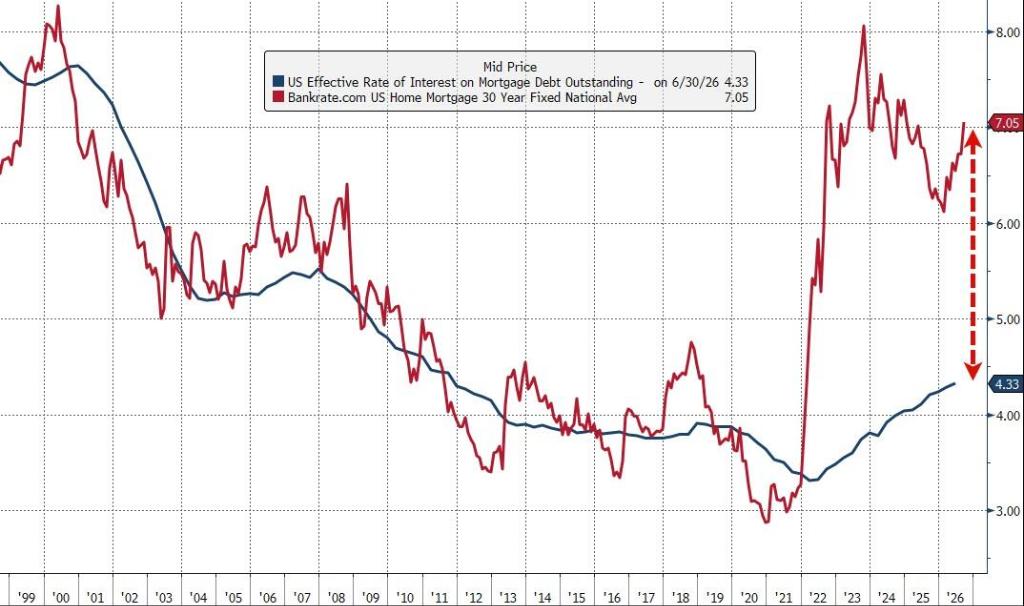
Meanwhile, the continuous rise in yields is transmitting to the real economy. The 30-year mortgage rate has exceeded 7%, increasing pressure on sectors relying on debt financing such as private equity. The Treasury buyback program launched by Treasury Secretary Bessent has failed to effectively curb the selloff, and market confidence is clearly insufficient.
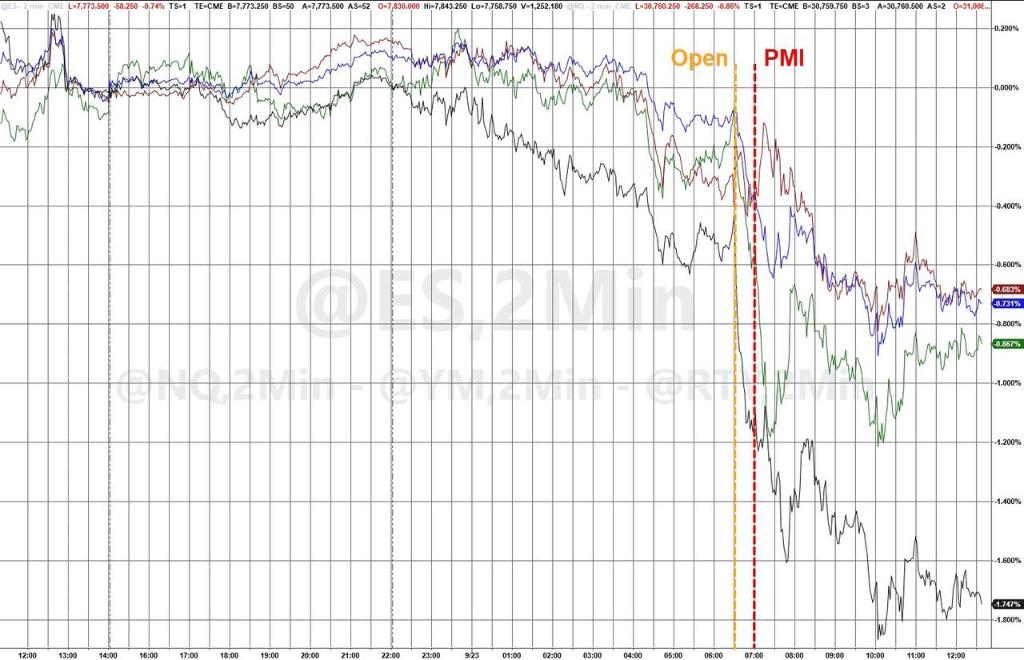
The stock market fell in tandem, but the decline was relatively moderate — the S&P 500 closed down about 0.8%, the Nasdaq Composite fell 1.1%, and the Dow Jones Industrial Average dropped roughly 352 points.
01
Four consecutive blows, the "perfect storm" takes shape
The collapse of the bond market on Wednesday did not stem from a single event, but from the superposition and resonance of multiple bearish factors in the same trading day.
The first blow: Soaring oil prices, dashed hopes for Middle East diplomacy.
Earlier that day, international oil prices surged during the European trading session. Previously, the market hoped that the ongoing UN General Assembly in New York could ease US-Iran relations, but remarks by Iranian President Masoud Pezeshkian dashed this expectation — he stated that Iran is willing to negotiate, but will not accept Trump's "bullying", and warned that as long as sanctions continue, Iran will not fully open the Strait of Hormuz. Brent crude, the benchmark for international oil prices, closed up nearly 4% that day. As the continuous rise in oil prices may transmit to broader inflation, bond yields have moved highly in tandem with oil prices in recent months.
The second blow: Blowout PMI data, heightened concerns about overheating economy.
S&P Global released its initial September U.S. Composite PMI report, showing that U.S. business activity expanded at its fastest pace in more than five years, with employment growth hitting its highest level in more than four years.
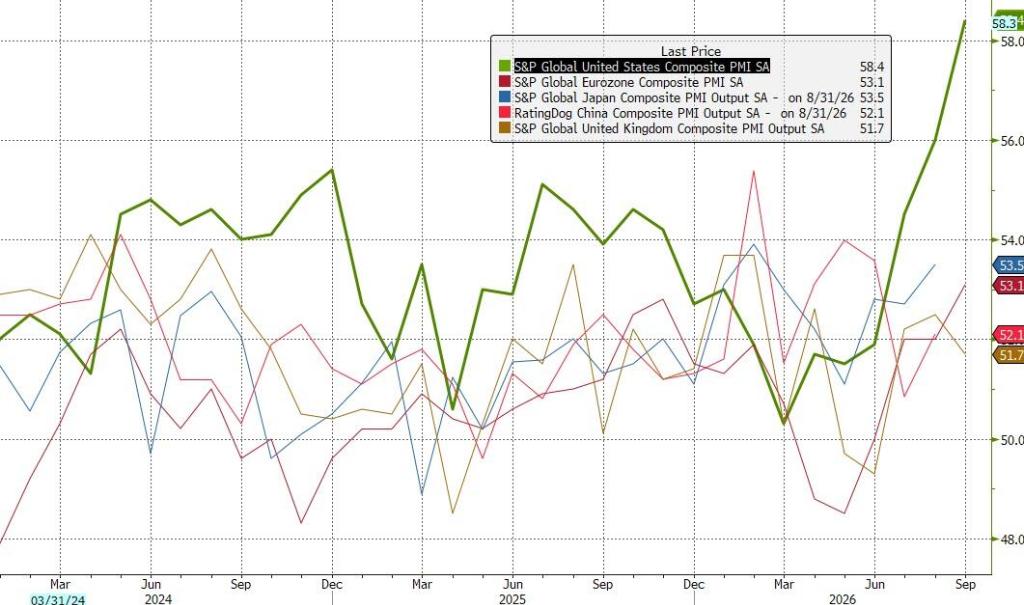
Chris Williamson, Chief Business Economist at S&P Global, said, "Aside from the post-COVID lockdown demand rebound, this improvement in business activity is the largest since early 2015." After the data was released, both short-end and long-end Treasury yields jumped.
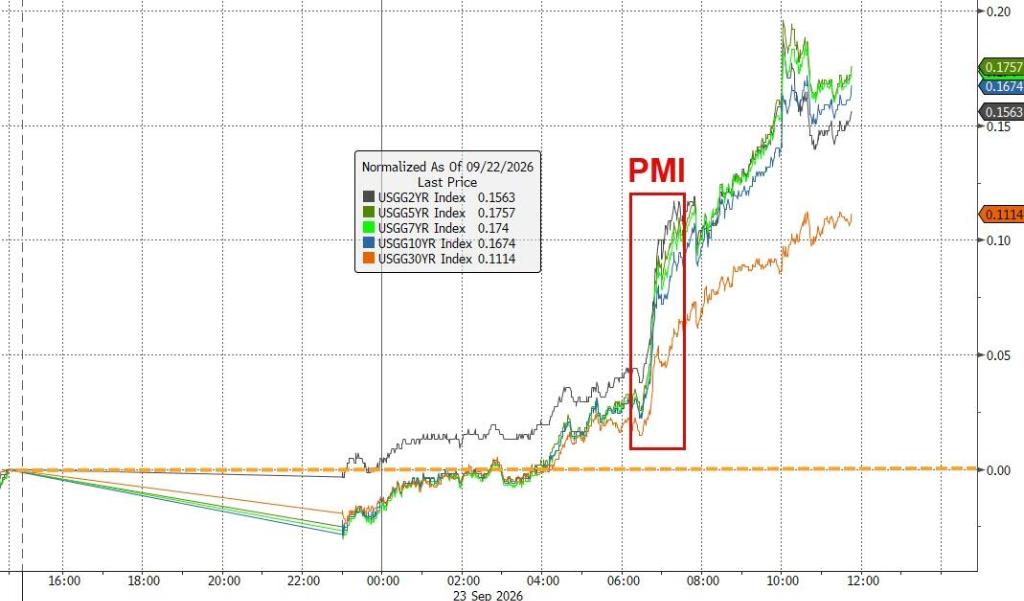
The third blow: Fed officials make hawkish statements.
Fed Governor Michael Barr delivered a speech in Chicago, explicitly stating that "inflation is above the 2% target, and there is no clear trend of moving closer to the target", and that "in my baseline scenario, further policy adjustments may be needed to ensure that inflation falls back to the target level in a timely manner".
Dhiraj Narula, U.S. Rates Strategist at HSBC, pointed out that the market is worried that "the Fed is willing to keep raising rates despite the pressure from supply shocks, which means the hawkish stance may not loosen at all".
The fourth blow: Disappointing 5-year Treasury auction, panic spreads faster.
The U.S. Treasury's $70 billion 5-year Treasury auction received a cold response. The awarded yield was 5.033%, roughly 3 basis points higher than the market trading level before the auction — this premium is quite significant in this huge market that usually digests supply smoothly.
Underwriters (primary dealers) were forced to take on an unusually large proportion of the bonds, the highest since 2024, indicating little interest from other potential buyers. After the auction results were released, yields moved higher, and panic spread accordingly.
02
Yields break through key levels across the board, hitting multi-year highs
The severity of this selloff is fully visible in the data.
The 10-year U.S. Treasury yield closed at 5.113%, marking the first time it has stood above 5% since 2007, with a one-day increase of roughly 14 basis points, the largest one-day jump since the shock of the so-called "reciprocal tariff day" under Trump last April, and also constituting an extreme fluctuation of about 4 standard deviations — just two weeks ago, the market experienced a 3-standard-deviation shock, putting pressure on the VaR (Value at Risk) of various risk books.
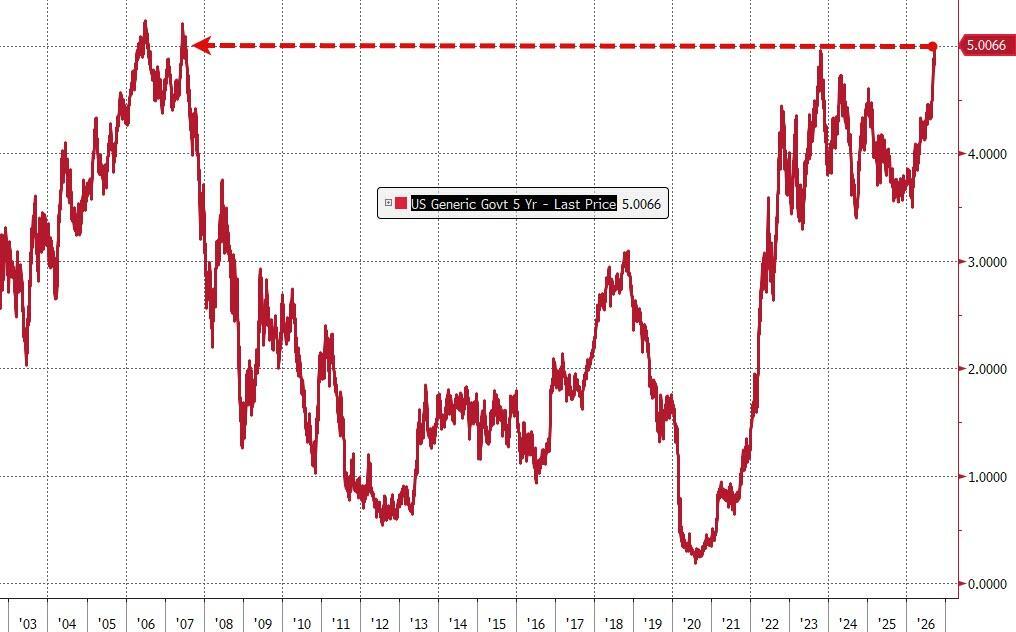
The 5-year yield surged by nearly 20 basis points on the day, breaking through 5% for the first time since 2007, and the failed auction further accelerated this trend.
The 30-year yield rose to its highest level since 2004. The 2-year yield once climbed to its highest level since 2024, then fell back slightly to 4.90%, up 12 basis points from the previous day.
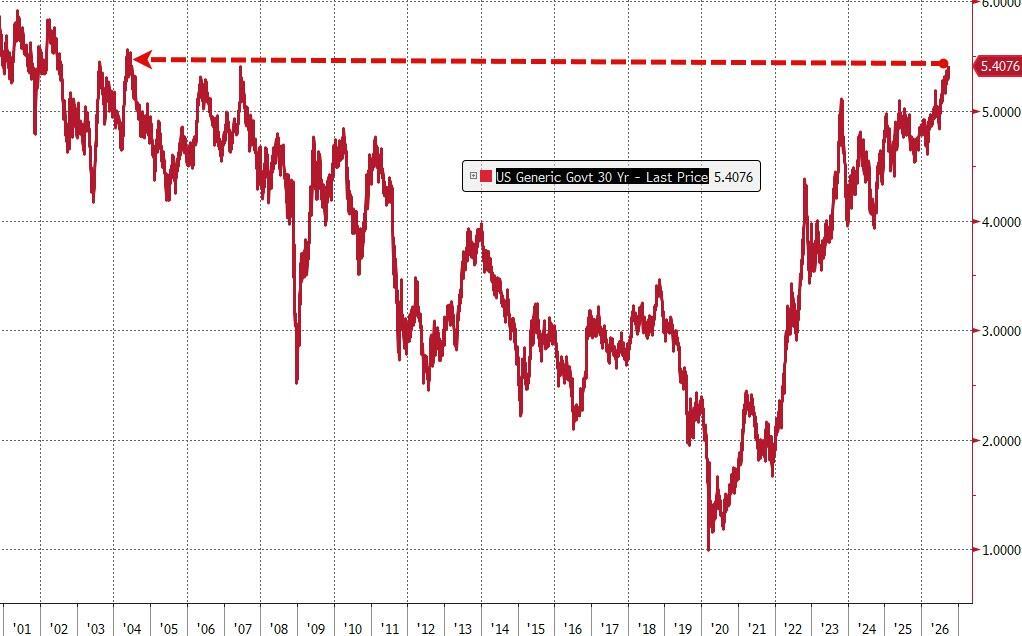
Bond volatility indicators jumped sharply in tandem, showing that the market's confidence in the future trend is seriously insufficient. Sean Simko, Head of Fixed Income Portfolio Management at SEI Investments, summed up the situation that day as a "triple blow":
"Stronger economic data, supply pressures pushing 5-year yields to levels not seen in years, and the judgment of global inflation stickiness."
03
The essence of the selloff: Real interest rate repricing, not just inflation panic
It is worth noting that the driving logic of this bond market selloff is not simply rising inflation expectations.
According to Bloomberg analysis, roughly 80% to 85% of the magnitude of this selloff comes from the rise in real interest rates: the nominal 10-year yield rose by about 15 basis points, the 10-year Treasury Inflation-Protected Securities (TIPS) yield rose by about 12.5 basis points, and the break-even inflation rate only rose by about 2 basis points.
This means bond investors are repricing for some combination of the following factors: a Fed path of keeping interest rates high for longer, stronger real growth expectations, higher neutral interest rates, higher real term premium or duration compensation, as well as greater supply pressure and tighter global financial conditions.
Rich Privorotsky from Goldman Sachs tends to interpret this trend from a growth perspective:
"In my view, this is increasingly a reflection of the strong growth assumption (a 6% fiscal deficit plus $1.5 trillion in spending means a huge amount of bond supply and a huge amount of nominal growth). This is a fairly clear macro risk for the stock market — not runaway inflation, but persistently high real cost of capital."
The Atlanta Fed's GDPNow model forecasts that the U.S. economy will grow at an annualized rate of 5.1% in the third quarter, which would be the fastest pace since the post-pandemic recovery if realized. Economists at JPMorgan Chase pointed out after last week's Fed meeting that Fed officials "may be seeing rising demand-driven overheating risks that policy may need to address."
Jason Granet, Chief Investment Officer and Head of Credit Services at BNY, raised a key question: "The Fed has already started raising interest rates. The question now is... will it stay on this path for quite a long time?"
04
The effect of the buyback program is in doubt, the Treasury faces pressure
Facing the continuous rise in yields, Treasury Secretary Bessent has tried to suppress yields by expanding the scale of long-term Treasury repurchases, but the effect is limited.
On Wednesday, the Treasury announced that it will repurchase up to $6 billion in 20- to 30-year Treasuries on Thursday, the second operation since the expansion of the repurchase program was announced in mid-August. However, this scale disappointed the market. Bob Michele, Chief Investment Officer at JPMorgan Asset Management, said bluntly:
"We thought the Treasury would see that the last $6 billion repurchase was a flop and go closer to $10 billion this time. But they didn't."
After the news was released, 20-year and 30-year yields moved higher, and bond volatility indicators jumped in tandem, showing that the market's confidence in the repurchase program is seriously insufficient.
Christopher Sullivan, Chief Investment Officer at United Nations Federal Credit Union, summed up the current predicament of the bond market: "From the unresolved conflict in Iran to the seemingly unshakable U.S. economy, holding bonds right now just 'doesn't make sense' for many people."
05
The stock market is relatively resilient, but interest rate risks cannot be ignored
Although the bond market suffered heavy losses, the decline in U.S. stocks was relatively limited. Scott Kimball, Chief Investment Officer of Fixed Income at Loop Capital Asset Management, said, "Risk markets are coping quite well. This really looks like an interest rate market problem."
However, the continuous rise in yields has triggered a chain reaction in the real economy — from mortgage rates, credit card rates, to the willingness of private equity firms to conduct leveraged buyouts, all have been affected. The 30-year mortgage rate has exceeded 7%, putting direct pressure on the real estate market.
Christophe Boucher, Chief Investment Officer at ABN AMRO Investment Solutions, warned that "the short-end yield curve is building up pressure", and today's economic data will allow the Fed to "double down" on its hawkish stance.
Brook, a strategist at RBC Capital Markets, admitted that the market has fallen into a frustrating cycle:
"You can look at these yield levels and say, this is really attractive. But we've been playing this game for the past six months, and every time we try to draw a line somewhere, it just keeps breaking through."
This article is from the WeChat official account "Wall Street News Max", author: Dong Jing, authorized for release by 36Kr.