Insurance companies have begun to cover all the costs incurred by the huge capital burn in the innovative drug sector.
At the start of this year, the author once participated in a closed-door seminar that discussed biomedical innovation and technology finance. During the meeting, when the guest speaker talked about the core pain points restricting the innovation of local pharmaceutical enterprises, he changed the topic and put forward a brand new track that is rarely mentioned in China — innovative drug R&D insurance.
In August, a piece of news was released. Led by PICC Property and Casualty Beijing Branch, jointly with China Taiping Property and Casualty Beijing Branch and Sunshine Property and Casualty Beijing Branch, the first life science R&D insurance policy in Beijing was successfully launched, issuing an exclusive policy for a new drug under research by a biomedical enterprise that treats adult fever. The landing of new drug R&D insurance in China has aroused industry attention.
Can innovative drug R&D also be insured? We break it down from three core clues: the ecosystem of overseas markets, the breakthrough of domestic pilots, as well as the core bottlenecks faced by the industry and its future trend.
01
R&D failure insurance is still a cutting-edge product overseas
To understand innovative drug R&D insurance, we need to clarify two concepts:
Clinical liability insurance covers the compensation liability of pharmaceutical enterprises to third parties. The policyholder is the pharmaceutical enterprise, and the beneficiary is the trial subject.
The leader in this field is Chubb — the world's leading human clinical trial insurance company, with business covering 54 countries and regions, and more than 30 years of experience in underwriting clinical trial insurance.
R&D loss insurance covers the loss of investment of pharmaceutical enterprises themselves. If the clinical trial fails to achieve the predetermined goal and the project is terminated, the insurance company will compensate the R&D expenses that the pharmaceutical enterprise has spent in accordance with the agreement. The policyholder is the pharmaceutical enterprise, and the beneficiary is also the pharmaceutical enterprise.
The core concern of new drug R&D enterprises: if the clinical trial fails and hundreds of millions of investments are wasted, is there any insurance that can compensate?
Clinical Trial Funding Insurance (CTFI), as a type of R&D loss insurance in overseas markets, can meet this demand.
The logic of CTFI is completely different from traditional liability insurance. Its compensation trigger condition is: If the clinical trial fails to meet the success criteria agreed in the policy (usually aligned with the primary endpoint of the trial protocol), the insurance company will compensate the trial costs that the pharmaceutical enterprise has already spent.
The premium is prepaid in one lump sum, and the risk is transferred from the pharmaceutical enterprise to the insurer. The covered expenses include CRO fees, clinical protocol design and consultation fees, hospital and investigator costs, monitoring and data collection and analysis fees, etc.
At present, the most focused player in this field is MCI (Medical & Commercial International), a professional underwriting institution that has been deeply engaged in life science and clinical trial risks since 2015. The team has talents with industrial and academic backgrounds, and focuses on clinical trial financing insurance.
MCI's underwriting scope is very clear: Phase I, Phase II and some small Phase III trials, with trial budgets usually ranging from 3 million to 35 million US dollars, and the trial cycle is 24 months, which can be extended to 48 months.
The insurable asset types include small molecules, peptides, antibodies and some biological products, but gene therapy, opioids and projects with a budget exceeding 45 million US dollars are not covered at present. The policyholders are limited to biotechnology companies in the United States, the United Kingdom, Europe and Canada, and the trial sites can be distributed globally.
A landmark landing case is the CTFI policy obtained by French biopharmaceutical company AB Science in April 2026.
This policy is underwritten by MCI through Lloyd's Syndicate 1902, with the broker being Acrisure Re. It provides a maximum protection of 25 million euros for its Phase III clinical trial for ALS (amyotrophic lateral sclerosis), which can potentially be extended to 39 million euros with zero deductible. The policy takes effect from the date of enrollment of the first patient, and covers the agreed financial costs of clinical trial failure within the limit of the sum insured.
Here we need to introduce the participants of this policy: MCI operates through Lloyd's Syndicate 1966 and 1902. Syndicate 1966 is the underwriting vehicle specially established by MCI for CTFI, which was approved in 2024; Syndicate 1902 is MCI's core underwriting platform, which undertakes conventional business and also participates in some CTFI arrangements.
The fact that this AB Science policy is underwritten by Syndicate 1902 shows that the underwriting vehicle for CTFI is not unique.
The relationship between the three can be understood as follows: MCI is responsible for underwriting pricing and product design, and is the operator; Syndicate 1966 and 1902 are the actual underwriting vehicles, which are underwriting tools; Lloyd's provides market rules, A+ credit rating and the final backstop of the central fund, which is the platform. The three cooperate closely.
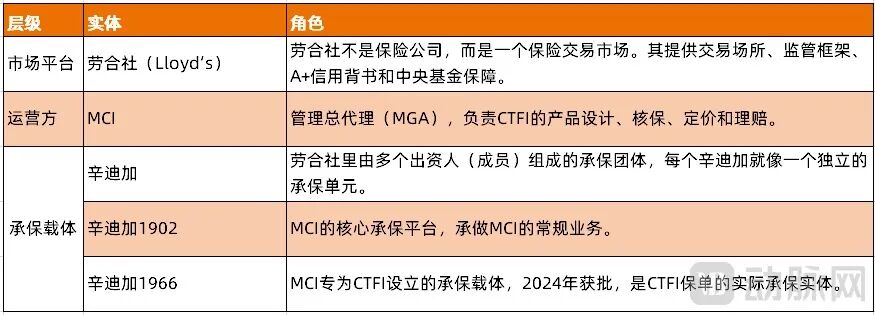
Lloyd's CTFI product business model (sorted by VBeta)
Alain Moussy, CEO of AB Science, said that ALS is regarded as one of the most difficult indications in the industry, and this insurance itself is a "confidence endorsement" for the success probability of their project. James Banks, co-founder of MCI, put it more directly: "Promote loans through insurance, help enterprises raise capital, reduce equity dilution through downside protection, and allow innovators to retain more control and ownership."
But CTFI also has its limitations. At present, the market size is still relatively small, the underwriting scope is concentrated in Phase I and Phase II, and Phase III only does "selected small trials". The most cutting-edge directions such as gene therapy and cell therapy are not insurable at present.
Moreover, the underwriting of CTFI relies on in-depth due diligence: reviewing historical clinical data, real-world data, trial design, and conducting computer simulation modeling. This means that the underwriting cost of each policy is very high, and it is difficult to scale up in the short term.
Innovatrix Capital is also a British professional insurance platform headquartered in London, founded in 2021, focusing on providing risk transfer solutions for clinical trial failure in the life science field, helping pharmaceutical enterprises and investors hedge the loss of R&D investment. In addition, large insurance groups such as Chubb have also begun to penetrate into the field of R&D insurance.
At present, overseas R&D insurance has long jumped out of the single logic of "simple claim settlement" and is deeply integrated into the industry and capital ecosystem.
For overseas Biotechs, this policy is not only a risk backstop, but also a credit endorsement for financing and transactions. In the process of key pipeline advancement nodes, new round of financing, mergers and acquisitions, BD transactions, and asset securitization, perfect R&D risk protection can greatly stabilize investor expectations and reduce pipeline valuation fluctuations.
At the same time, a model of collaborative risk control by insurance institutions, professional CROs and scientific research institutions has been formed overseas, with a reasonable enterprise retention risk and premium adjustment mechanism to minimize the pressure of innovation trial and error for pharmaceutical enterprises.
It is understood that there are clear rate ranges for pipelines in different clinical stages: the pre-clinical and IND stages have the highest risk, with rates up to 15%–30%; in the core Phase II clinical underwriting stage, the rate remains at 8%–18%; when entering the mature stage of Phase III and NDA application, the rate drops to 4%–10%.
Of course, this type of R&D loss insurance never fully covers the R&D investment, and generally sets a high enterprise deductible, while strictly excluding risks such as human decision-making errors, voluntary strategic termination, and data fraud, and only covers pure technical R&D failures. High-risk first-in-class new mechanism pipelines still face the problems of high premiums and high underwriting thresholds, which is a common problem in the industry.
Therefore, the accurate conclusion of the overseas part is: liability insurance has long been conventional; R&D insurance is still a cutting-edge product, which has been applied overseas, but it is far from being "inclusive".
02
Domestic pilot: From "only covering liability" to "daring to cover failure"
Domestic medical insurance products have been extremely single for a long time. The relevant insurance types available on the market basically only cover the liability risks of clinical trials — that is, the personal safety of trial subjects and the compensation for medical disputes. The loss of expenses caused by the R&D failure of pharmaceutical enterprises themselves is completely uninsured. Once the project is terminated, all the hundreds of millions or even billions of upfront investments are completely sunk.
Until 2026, the situation began to change. Beijing has recently launched a landing pilot for R&D loss insurance.
The policy launched in Beijing this time accurately covers the expense losses caused by R&D failures in the key stages of R&D breakthrough and achievement transformation, filling the gap in the protection of innovative drug R&D failure losses in Beijing, and also sharing the cost of scientific and technological innovation trial and error for enterprises.
On September 9, the first policy of Beijing Biomedical Insurance Co-insurance Body was officially launched, and the policyholder is the ECMO consumable R&D project of Changzheng Medical. The policy is underwritten by PICC Property and Casualty Beijing Branch as the lead underwriter, jointly with Ping An Property and Casualty, China Pacific Property Insurance, China Life Property and Casualty, and China Taiping Property and Casualty, and Beijing Zhongwei Insurance Brokerage Co., Ltd. provides the whole-process insurance brokerage service.
These two first policies are not contradictory, but verify two things respectively: The former verifies that "R&D failure losses can be insured", and the latter verifies "how multiple companies can jointly underwrite". The co-insurance body is an organizational mechanism, and R&D expense loss insurance is the product direction.
The core innovation of this scheme lies in segmented underwriting — splitting long-cycle, high-risk R&D projects into evaluable and insurable units according to pre-clinical, Phase I, Phase II, Phase III, NDA and other stages. After the R&D fails, the R&D investment corresponding to that stage will be compensated.
This move solves a long-standing problem plaguing the industry: insurance companies dare not underwrite long-cycle projects because they cannot assess the overall risk; enterprises feel that the premium is too expensive because the sum insured cannot match the stage. After splitting, insurance companies can price in segments, and enterprises can underwrite by stage.
The core value of the co-insurance body model lies in solving the problem that a single insurer "cannot afford to take it": multiple companies jointly underwrite according to the agreed proportion, and the premium and compensation liability are shared simultaneously, forming a two-layer risk diversification structure of "direct insurance + reinsurance". At the same time, the co-insurance body unifies the underwriting terms, rates and risk control access, aggregating the underwriting experience and actuarial capabilities of multiple institutions into a set of standards.
For low-frequency and high-loss risks such as R&D failure, the co-insurance body turns "one company cannot carry it" into "multiple companies share the burden", and puts the originally uninsurable risk on enough shoulders.
As the leading force behind it, Beijing Municipal Science and Technology Commission and Zhongguancun Administrative Committee have included R&D expense loss insurance into the key work of the city's pharmaceutical and health industry, and since January 2026, together with the Beijing Financial Regulatory Bureau, they have organized multiple rounds of special seminars and demonstrations, built a supply-demand docking platform, and promoted nearly 30 innovative drug and device enterprises to conduct in-depth docking with insurance institutions.
But there is a very important restriction. The Beijing pilot initially mainly provides protection for projects funded by the Beijing Municipal Science and Technology Commission. To put it bluntly, this is an exclusive project within the system of Beijing Municipal Science and Technology Commission, which is not open to the market and has not been commercially promoted. Enterprises cannot apply for insurance whenever they want, they must first enter the funding list of the Municipal Science and Technology Commission or the "project-based" key service catalog.
This model is a normal state in the pilot period. Any new insurance type from zero to one needs to run through the process, accumulate data and verify the model in a controllable range first.
Beijing's logic of choosing to start with projects within the system of the Municipal Science and Technology Commission is clear: the R&D progress of these projects is tracked by the government, the data is collected, and the risk is relatively assessable, which is suitable as the first batch of underwriting objects. But this also means that at this stage, this product is still out of reach for ordinary Biotechs in the market.
The next plan of the co-insurance body is to focus on key tracks such as innovative drugs and devices, cell and gene, brain-computer interface, and provide full-cycle insurance for innovative drugs and devices.
The general judgment of industry observers is: the co-insurance body is a transitional mechanism in the start-up period, not the end point. A single insurance company does not dare to underwrite alone, so multiple companies join forces to share. When the data is accumulated enough and the actuarial model is mature, it will gradually transition to market-oriented underwriting by a single insurance company.
03
Stuck point: It is not that they dare not insure, but that they cannot calculate clearly
So can this thing be done successfully?
The direction is correct, but there are several hard nuts to crack.
The data hurdle cannot be bypassed. Innovative drug R&D faces brand new targets and brand new mechanisms, and there is no historical claim data. Insurance actuarial relies on the law of large numbers, but where does the "large number" come from? At present, the industry is trying to use industrial data instead of historical data to build models. In July 2026, China Life Property & Casualty Insurance released an "innovative drug full life cycle risk protection model", trying to break the barrier between industrial data and financial risk control.
Damage assessment is another hurdle. The reasons for R&D failure are too complicated: it may be that the scientific hypothesis itself is not valid, there may be defects in the clinical protocol design, it may be difficult to enroll patients due to changes in the external environment, or the regulatory requirements have changed. How to attribute? How to judge that "this failure should be compensated by insurance"? Beijing's segmented underwriting model alleviates this problem to a certain extent, because the goal of each segment is relatively clear, but a lot of professional judgment is still required in actual operation.
Moral hazard is also unavoidable. After pharmaceutical enterprises buy insurance, will they reduce the prudence of R&D decisions? Will they selectively underwrite high-risk pipelines? How to design the deductible? How to determine the co-insurance ratio? All these need to be explored in practice. CTFI of MCI sets a "zero deductible", which is actually a strong signal — it shows that the underwriter has enough confidence in the success probability of the project to dare to do zero deductible.
Cost is another practical threshold. The rate of early-stage projects may exceed the affordability of small and medium-sized Biotechs. Under the current domestic co-insurance body model, the premium sharing mechanism is still being adjusted. Moreover, the Beijing pilot currently has the special fund support of the Municipal Science and Technology Commission. Once it enters the stage of market-oriented promotion, how to set the premium and whether enterprises are willing to pay for it is another problem.
The first policy in Beijing has just been launched, and many enterprises are signing contracts next, and the rhythm is accelerating.
The next thing to watch is: whether the Beijing pilot can expand from the exclusive projects of the Municipal Science and Technology Commission to a wider range of market entities, whether data accumulation can keep up, whether the actuarial model can be mature, and whether insurance institutions can truly understand the biomedical industry.
The "language gap" between insurance and pharmaceutical enterprises does exist. Insurance focuses on the probability distribution of economic losses, while pharmaceutical enterprises focus on the success probability of technical routes. How to translate and align these two sets of languages is the key to determining whether R&D insurance can grow from a "policy bonsai" to a "normal tool".