The Fresh Vitality of New World, Shanghai K11 to Issue Commercial Real Estate REITs
A new player has joined the commercial real estate REITs queue this time, namely New World Development, with the underlying asset being Hong Kong New World Tower in Shanghai.
On September 19, the official website of the Shanghai Stock Exchange showed that the GF New World Closed-end Commercial Real Estate Securities Investment Fund (hereinafter referred to as "GF New World Commercial Real Estate REIT") was updated to the "Accepted" status.
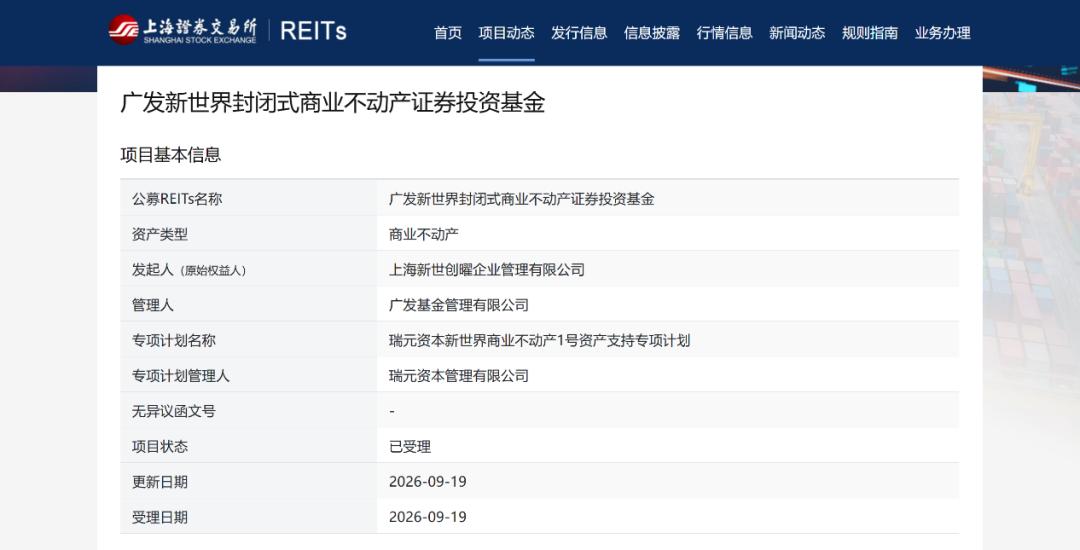
Source: Official website of Shanghai Stock Exchange, captured by Business Observer
According to the disclosure in the prospectus (draft), the REIT is expected to raise 3.818 billion yuan. The original equity holder is Shanghai Xinshi Chuangyao Enterprise Management Co., Ltd., the manager is GF Fund, and the underlying asset is Hong Kong New World Tower in Shanghai, which consists of Shanghai K11 Art Mall and the office section Shanghai K11 ATELIER New World Tower.
Interestingly, this asset was previously caught in sale rumors. In July 2025, there were reports that New World Development would list some office units of Shanghai K11 for sale at a price of 2.85 billion yuan, but New World Development immediately refuted the rumor.
In comparison, the fundraising size of 3.818 billion yuan involved in this REITs issuance is nearly one billion yuan higher than the rumored selling price of only the office part of 2.85 billion yuan, and the valuation advantage of the REITs path is self-evident.
The reason for such rumors is mainly closely related to the "Seven-pronged Full Debt Reduction Plan" implemented by New World Development in the past two years, which includes actively selling development projects, actively selling non-core assets, unlocking the value of agricultural land, increasing rental returns, streamlining costs, suspending dividend distribution, and active financial management.
Now, by issuing commercial real estate REITs, New World Development can not only retain the control of this benchmark commercial project in Chinese Mainland, but also raise a considerable amount of funds, which is a more cost-effective business no matter how you look at it.
The prospectus shows that the underlying asset valuation of this REITs reaches 4.568 billion yuan, the predicted annual compound growth rate of cash flow is 1.41%, and the discount rate is 5%; the predicted distributable amount from April to December 2026 is 138 million yuan; that for 2027 is 181 million yuan.
01
Asset Background
New World Development mainly conducts business in Chinese Mainland through New World China, whose core projects are spread across South China, East China, Central China, North China and Northeast China.
Hong Kong New World Tower in Shanghai is located in the central business district of Middle Huaihai Road, with a total land area of more than 9,900 square meters and a total construction area of over 130,000 square meters. With a height of 265 meters, it has become a landmark high-rise building on Middle Huaihai Road.
The project was first completed and passed completion inspection and acceptance in 2002. In the more than ten years after its completion, it was mainly a pure-lease Grade A office building, mainly targeting tenants in the finance, professional service industries and foreign enterprises.
In 2013, New World Group invested more than 400 million yuan to completely renovate the commercial podium of the building, building the first K11 Art Mall in Chinese Mainland. Its special feature lies in pioneering the "Art + Museum Retail" model, which deeply integrates art exhibitions, natural landscapes and commercial consumption.
Since then, Hong Kong New World Tower in Shanghai has become a comprehensive project with a view of the Huangpu River, integrating Grade A office buildings, K11 Art Mall and K11 Club, the first senior executive club in an office building in Shanghai.
In terms of the volume of each business format, the commercial part covers 3 underground floors to 5 above-ground floors, with a leasable area of about 16,900 square meters; the office building is from the 11th to the 57th floor above ground, with a leasable area of 80,500 square meters, and there are other areas such as parking lots on the 6th to 9th floors above ground.
In addition to the location advantage, the investment promotion level of K11 Art Mall speaks for itself in Shanghai's commercial landscape, for example, in terms of the number of first stores.
Up to now, K11 Art Mall has a total of 25 operating first stores, including 18 national first stores such as Casetify, and 7 Shanghai first stores such as Yohji Yamamoto, Wang Fanxing Noodle House, Atlas Farmer, etc.
K11 ATELIER is positioned as a landmark Grade A office building on Middle Huaihai Road, focusing on high-end business offices. Its target customer groups are mainly financial services, professional services (law firms, consulting), high-end retail, regional headquarters of luxury brands, and digital new economy enterprises, most of which are regional headquarters and high-quality medium and large enterprises.
In terms of operation performance, according to the disclosure of the prospectus, in the past three years, the occupancy rates of K11 Art Mall in the shopping mall part were 90.21%, 95.92% and 92.04% respectively, and the contract rent unit prices were 20.94 yuan/sqm/day, 17.67 yuan/sqm/day and 15.44 yuan/sqm/day respectively;
The occupancy rates of K11 ATELIER in the office building part were 92.21%, 90.13% and 90.15% respectively, and the contract rent unit prices were 7.98 yuan/sqm/day, 7.63 yuan/sqm/day and 7.20 yuan/sqm/day respectively.
In the first quarter of 2026, the performance of both K11 Art Mall and K11 ATELIER improved to varying degrees compared with the past. The occupancy rate of K11 Art Mall rose to 96.98%, the occupancy rate of K11 ATELIER slightly rose to 90.52%, and the rent unit prices were 16.84 yuan/sqm/day and 7.01 yuan/sqm/day respectively.
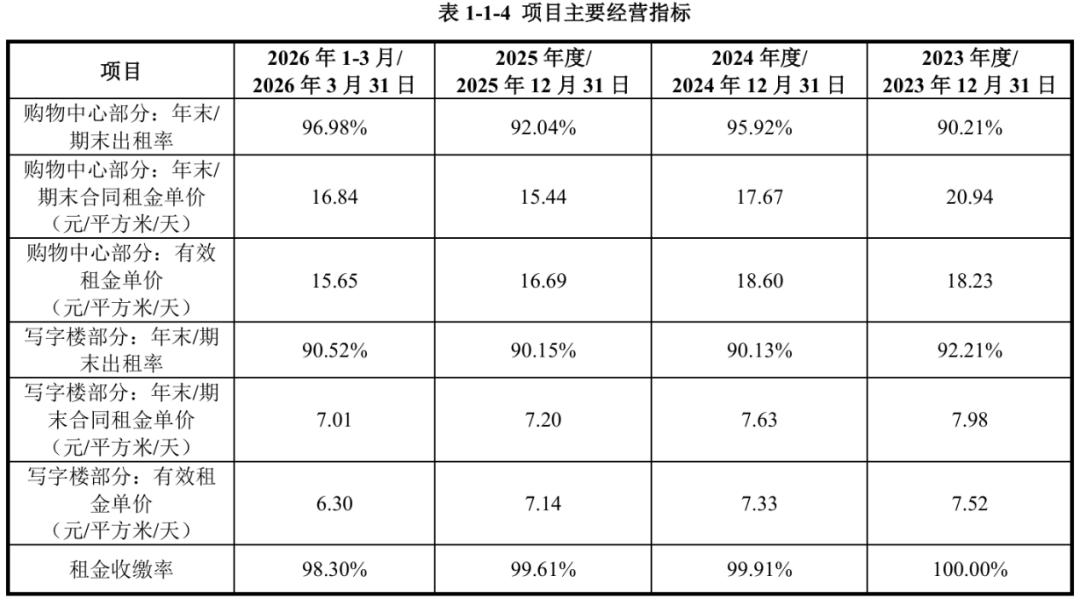
Data source: Prospectus, captured by Business Observer
02
Behind the Spin-off Listing
Putting Shanghai K11 into REIT for spin-off listing is not so much a conventional asset securitization as a key move for New World Development to push its debt reduction strategy to a deeper level.
To sort out why this REIT was launched at this time, why Shanghai K11 was chosen, and why REITs was chosen instead of direct sale, we need to go back to New World Development's current financial situation for analysis.
According to the 2025/2026 interim report of New World Development, by the end of 2025, the company's total debt was about HK$144.3 billion, net debt was about HK$122.7 billion, and the net debt ratio was 59.7%.
To cope with the debt pressure, New World Development has adopted a variety of measures to reduce its heavy debt burden, including bank loan refinancing, debt replacement, and the "Seven-pronged Debt Reduction" strategy implemented by CEO Huang Shaomei. It is reported that since 2025, New World Development has promoted HK$88.2 billion of bank refinancing and about HK$20 billion of debt exchange.
However, refinancing and debt replacement can only delay the pressure, and real debt reduction still relies on asset realization to provide cash flow. Selling assets is indeed the simplest and most straightforward way, so rumors such as "New World Development sells the office part of Shanghai K11 for 2.85 billion yuan" come out from time to time in the market.
However, under the current office market environment in Shanghai, it is difficult to obtain the ideal valuation by directly selling office assets. The buyer has large bargaining space, and the seller is in a passive position.
Until the outbreak period of commercial real estate REITs arrives, New World Development has found a healthier and more decent financing path.
By packaging and listing Shanghai K11 Art Mall and K11 ATELIER, New World Development, as the sponsor, still retains the operation and control right of the assets, recovers about 3.818 billion yuan in one go, and the REITs platform can provide a continuous exit channel for other subsequent assets, rather than a one-off deal.
In general, the success or failure of this REIT is not only related to the fundraising result of 3.818 billion yuan, but also related to whether New World Development can prove to the market that its high-quality mainland commercial assets have the possibility of continuous realization through the REITs platform.
For New World Development, the long-term value of this channel may be more important than the amount of a single fundraising itself.
This article is from "iNews", written by Business Observer, authorized for release by 36Kr.