The 40-year mortgage policy has been officially implemented: the monthly payment for a 1 million-yuan mortgage is reduced by 636 yuan.
More than half a month after the introduction of the new 40-year mortgage policy, a number of banks have accelerated the implementation of detailed rules, further clarified the application process for extending mortgage terms, and stepped up promotion of individual housing loan businesses.
On September 17, Bank of Nanjing Hangzhou Branch stated on its official WeChat platform that the maximum term of its individual housing loans can reach 40 years. The bank will conduct comprehensive examination and approval based on the borrower's age and income status, helping borrowers reasonably extend the loan term, reduce monthly payments and ease repayment pressure. Bank of Nanjing noted that borrowers can apply online, with the fastest pre-approval in 3 minutes and full approval within 24 hours.
Not only Bank of Nanjing, since September 10, a number of mainstream banks including large state-owned banks and local urban and rural commercial banks have actively responded to the new mortgage policy, clearly stating that applications for 40-year mortgages can be accepted, and the specific term will be determined through negotiation between home buyers and the bank.
However, Time Finance recently learned from a number of banks that 40-year mortgages are not available to everyone. Due to differences across regions and banks, no unified standard has been formed for the implementation rules among all institutions. Banks will conduct comprehensive and prudent examination and approval based on individual qualifications such as the borrower's age, employer, income and credit record.
Judging from market feedback, the willingness of home buyers to actively apply for 40-year mortgages is not strong at present, and the demand for extending existing mortgages is more urgent than that for new mortgages. Through multiple interviews, Time Finance found that up to now, some banks have clearly stated that the new policy also applies to existing businesses, and the issued housing loans can apply for extension to 40 years; according to feedback from many home buyers, some large banks have launched application entrances on their mobile banking apps, and the original individual housing loan contract can apply for a maximum extension of 480 months.
Not Everyone Qualifies for the Loan, Examination and Approval Still Depends on Age, Income and Credit Record
On August 28, the People's Bank of China and the National Administration of Financial Regulation jointly issued new credit regulations, officially extending the maximum term of individual housing loans from the original 30 years to up to 40 years. According to incomplete statistics from Time Finance, as of September 18, Bank of Nanjing, Bank of Changsha, Postal Savings Bank of China, Hankou Bank, and some small and medium-sized rural commercial banks in Yunnan Province have released notices on the implementation of the new mortgage policy on their official platforms.
The recent announcement released by Postal Savings Bank of China Jiangsu Branch shows that the maximum term of its individual housing loans can reach 40 years, and it supports online submission of application materials, with the fastest pre-approval taking only 15 minutes.
According to the repayment calculation reference provided by the bank, for a mortgage of 1 million yuan with an annual interest rate of 3%, repaid through equal principal and interest method, the monthly payment for a 40-year term is about 3,580 yuan. Compared with the monthly payment of 4,216 yuan for a 30-year term, the monthly repayment can be reduced by about 636 yuan, a decrease of about 15.1%. However, the interest cost of a 40-year mortgage has also increased significantly, with the total cumulative repayment amount of the borrower being about 1.71 million yuan, which is about 200,000 yuan more in interest than the 1.51 million yuan of a 30-year mortgage.
Bank of Changsha also recently released an announcement on its official WeChat platform, stating that it has fully implemented the new policy of a maximum 40-year term for individual housing mortgage loans, providing one-stop services from consultation, examination and approval to loan disbursement; Hankou Bank stated that the maximum term of its individual housing loans can reach 40 years, and the maximum loan-to-value ratio can be up to 85%.
Some large state-owned banks are also promoting the implementation of the new mortgage policy in Guangzhou, but there are still hidden thresholds in practice, and young groups with rigid housing demand have become the main beneficiaries of the new policy. Taking a sub-branch of the Industrial and Commercial Bank of China as an example, if you want to get the full 40-year term, the borrower's age must not exceed 45 years old. On September 17, Time Finance called a sub-branch of the Industrial and Commercial Bank of China in Tianhe District, Guangzhou, and the staff of the bank said, "We just received the implementation rules issued by the head office today, and we can now accept applications for extending the mortgage term to 40 years, but there are requirements for the borrower's age, and the sum of the borrower's age and the loan term must not exceed 85 years."
In terms of existing businesses, the actions of various institutions are more obviously differentiated. Li Lin (pseudonym), a borrower from Anhui, told Time Finance that he found the "Extend Receipt Term" entrance on his mortgage contract page in the ICBC app, and after selecting the application reason, the maximum extension term of this loan can be selected as 480 months.
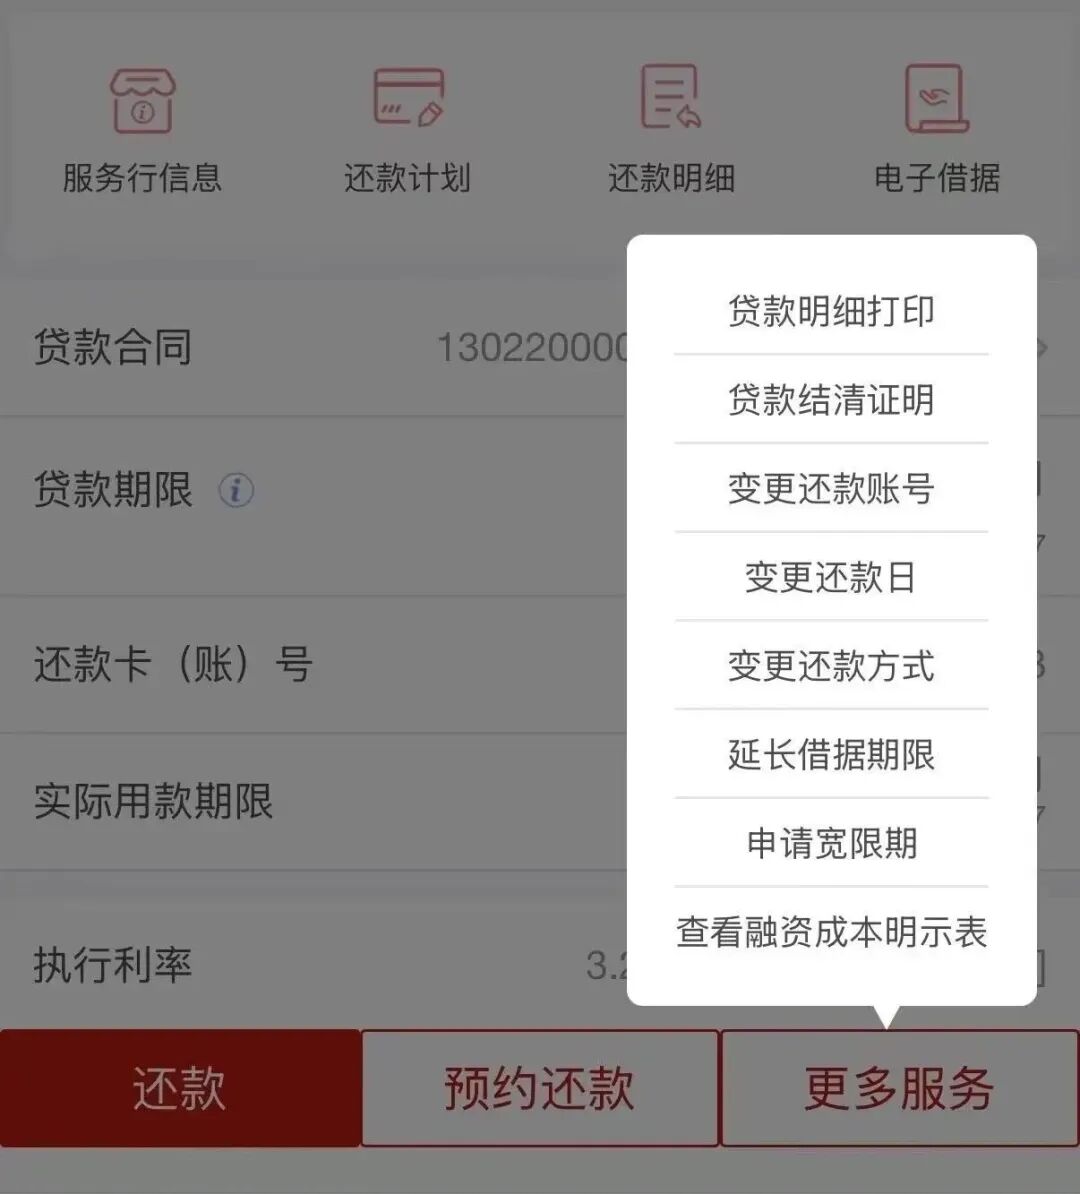
Source: Provided by the interviewee
However, according to the aforementioned staff of the ICBC sub-branch in Tianhe District, Guangzhou, the online application of ICBC is only for reference, and existing mortgages cannot be automatically extended. Offline application and manual examination and approval are required. "Borrowers need to carry materials such as income certificates, real estate certificates, and house registration inquiry records to the branch to fill in the application form, and submit a statement explaining the situation of applying for extension. After the approval, the bank will issue a contract change agreement, and the borrower needs to re-sign the agreement and re-handle the mortgage registration."
ICBC also stipulates that the extension term cannot exceed half of the original loan term, which means that if the borrower's original mortgage has a short term, it is very difficult to extend it directly to 40 years.
Some banks have also clearly stated that existing mortgages are not included in the scope of this round of new policies. The recent announcement released by Gengma County Rural Credit Union in Yunnan shows that after the official implementation of the new mortgage regulations, the bank's newly accepted individual housing loan businesses will be implemented in accordance with the new measures; the existing issued housing loans will not be affected by this policy adjustment and will continue to be implemented in accordance with the original loan contract.
Some Want to Reduce Monthly Payments, Others Worry About Paying More Interest
Although all banks are stepping up efforts to promote the implementation of the new policy, not many customers have actually submitted applications for 40-year mortgages. The aforementioned staff of the ICBC sub-branch in Tianhe District, Guangzhou also admitted to Time Finance, "No one in our bank has handled it yet. After all, the total interest will increase, and many customers will consider the cost issue."
Tian Lihui, Dean of the Institute of Financial Development of Nankai University, pointed out to Time Finance that for home buyers, although the monthly payment is reduced by about 15%, the total interest increases by about 200,000 yuan, and the credit risk cycle is extended. They still need to repay the loan after retirement, and home buyers will face risks such as long-term income uncertainty, housing value depreciation and thinner family financial safety cushion.
"Extending the loan term to 40 years is essentially a demand-side support tool that 'exchanges time for space', rather than a universal welfare. Its core logic is to spread the repayment pressure over a longer life cycle, activate rigid and improved housing demand by lowering the monthly payment threshold, and stabilize the scale of bank mortgage assets at the same time," Tian Lihui further stated.
Time Finance found in interviews that compared with new mortgages, the demand for extending the term of issued existing mortgages is more intense, but the real motivation of some potential applicants is to "reduce monthly payments and choose an appropriate time to make early repayment". Li Lin, 29 years old this year, is one of them. He took out a 1.09 million yuan loan to purchase a commercial housing property in Hefei in early 2024, with the original loan contract term of 30 years. After the new policy was released, he has applied to the lending bank to extend his mortgage from 30 years to 40 years, and is waiting for the subsequent approval result.
"I failed in investment some time ago, and all the savings in my family were gone. If I followed the previous consumption level, every month would definitely be very tight. So when I saw this policy, I wanted to reduce the monthly payment, so that I can leave more cash for living every month, save money faster, and then make early repayment later," Li Lin told Time Finance.
This method of "long-term loan with short repayment period" reflects the current residents' prudent attitude towards long-term liabilities. Yan Yuejin, Vice President of the Shanghai E-House Real Estate Research Institute, also said that the 40-year term is not a mandatory repayment term. After home buyers' income increases in the future, they can still optimize their debts through methods such as early repayment, which has full flexibility in practice.
Driven by residents' strong willingness to deleverage, the individual housing loan business of banks has continued to shrink in recent years, the popularity of early repayment has not decreased, and a large number of existing mortgages have been cleared. According to the "Statistical Report on Loan Distribution of Financial Institutions in the Second Quarter of 2026" recently released by the People's Bank of China, as of the end of the second quarter of this year, the balance of national individual housing loans was 36.29 trillion yuan, a year-on-year decrease of 3.8%; from the perspective of listed banks, as of the end of June 2026, the total mortgage balance of the six major state-owned banks was about 24.63 trillion yuan, a decrease of more than 500 billion yuan from the end of 2025.
In fact, due to its long term, relatively stable interest rate and low non-performing rate, individual housing loans were once regarded as one of the highest-quality assets of banks. According to industry insiders, the implementation of this round of new policy is expected to boost the mortgage business of banks to a certain extent.
Tian Lihui pointed out to Time Finance that for banks, after the extension of the mortgage term, the interest income per customer will increase significantly, which can slow down the decline rate of mortgage balance, reduce the early repayment rate and default risk in the short term; but there are also coexisting risks. Short-term deposits corresponding to super-long-term loans will exacerbate the maturity mismatch of banks' assets and liabilities, and the exposure to interest rate risk and credit risk will expand simultaneously.
However, he further emphasized that the boost of this round of new policy to the bank mortgage business is more reflected in risk support rather than scale expansion. "Before residents' income expectations and housing purchase confidence are fundamentally restored, it is difficult to reverse the overall negative growth trend of mortgages," Tian Lihui said.
This article is from the WeChat official account "Time Finance APP" (ID: tf-app), author: Zhang Xinying, published with authorization from 36Kr.