The unheralded runner-up in the automotive industry has opened for subscription, and its founder used to be a primary school teacher at a township school in Zhejiang Province.
On September 16, Anda Co., Ltd. opened for subscription on the Beijing Stock Exchange, with an issue price of RMB 7.55 per share, an issue P/E ratio of 13.50 times, a maximum subscription limit of 1.19 million shares for a single account, and a required market value of RMB 8.9845 million for full-position subscription. The company is mainly engaged in precision aluminum alloy die castings for automobiles, and its attributable net profit to shareholders in 2025 was RMB 69.5421 million.
The initial public offering totals 28 million shares, with 19.6 million shares offered online. Caitong Securities is authorized for over-allotment of 4.2 million shares, expanding the online offering size to 23.8 million shares; 8.4 million shares are for strategic placement, accounting for 30% of the total offering volume, and the total share capital after issuance is 112 million shares. The total estimated raised funds amount to RMB 211 million, and if the over-allotment option is fully exercised, the total raised funds can reach RMB 243 million.
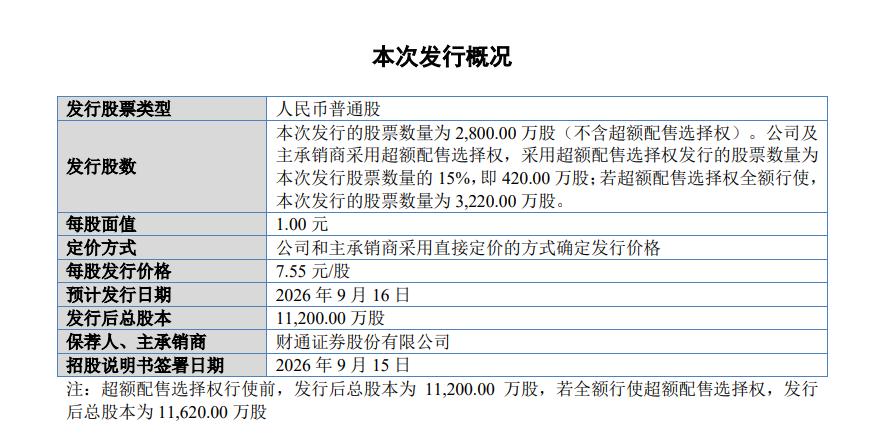
The issue price of RMB 7.55 corresponds to a P/E ratio of 13.50 times, which is lower than the average static P/E ratio of 22.75 times of the same industry in the latest month. Calculated based on the total share capital after issuance, the total market value of the company is about RMB 846 million, the circulating market value on the first day of listing is about RMB 180 million, and there is no old share transfer in this issuance.
Anda Co., Ltd. is a national-level specialized, refined, differential and innovative "little giant" enterprise and a single champion of the manufacturing industry in Zhejiang Province.
The company was established in August 2005, initiated and founded by Modern Agricultural Equipment Huzhou Combine Harvester Co., Ltd. with the equipment and cash of its auto parts factory together with 23 shareholders, and the establishment process was recognized as the restructuring of a state-owned enterprise.
In 2023, it was transformed into a joint-stock company as a whole, listed on the NEEQ Innovation Layer in 2024, and obtained the registration approval from the China Securities Regulatory Commission in August this year. The controlling shareholder is Huzhou Industrial Investment, with a total shareholding of 61.35%, and the actual controller is the State-owned Assets Supervision and Administration Commission of Huzhou Municipality.
Guan Huibin, Chairman and General Manager, was born in November 1973. He taught at the Central Primary School of Hengshan Township, Changxing County for 5 years in his early years, and then served in relevant positions in multiple townships of Changxing County and the county party committee. He once served as Chairman and General Manager of Warm Energy Environment and President of the Chain Innovation Platform Division of Tianneng Battery, and took over Anda Co., Ltd. in March 2022.
In essence, its business is the invisible runner-up in the segmented track.
The core products of the company are powertrain system components, mainly surrounding engine housings such as oil pans and cylinder head covers, which are compatible with fuel vehicles and hybrid models; new energy three-electric system components include inverter housings and motor housings, and it also produces suspension parts such as mounting brackets. According to sales volume statistics, in 2023, the domestic market share of the company's aluminum alloy die castings for passenger car engine oil pans and covers reached 15.5%, ranking second in China.
However, high customer concentration is an unavoidable weakness.
Its customers cover Volkswagen Group, SAIC Motor, SAIC General Motors, SAIC Volkswagen, Hyundai Transys, Valeo, Fute Technology and other enterprises, its products are supplied to brands including Volkswagen, Audi, Buick and Toyota, and indirectly support Li Auto, Xpeng Motors and GAC Aion. In the first half of 2026, the total revenue of the top five customers accounted for 84.45%, of which Volkswagen Group alone accounted for 38.19%.
The sales proportion of the top five customers from 2023 to 2025 was 87.35%, 88.66% and 81.77% respectively, which continued to be higher than the average of comparable companies. To enter the supply chain of Hyundai Motor, the company once supplied goods through the intermediate trader Shandong Altai. During the reporting period, the gross profit margin of this channel was only 7.13%, 8.68% and 11.80%; in the same period, the gross profit margin for direct large customers such as Volkswagen and SAIC remained above 12%.
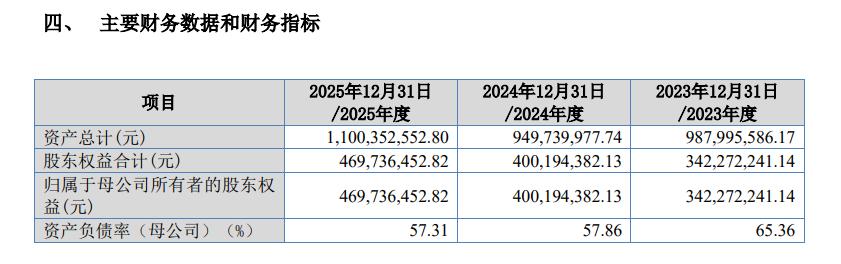
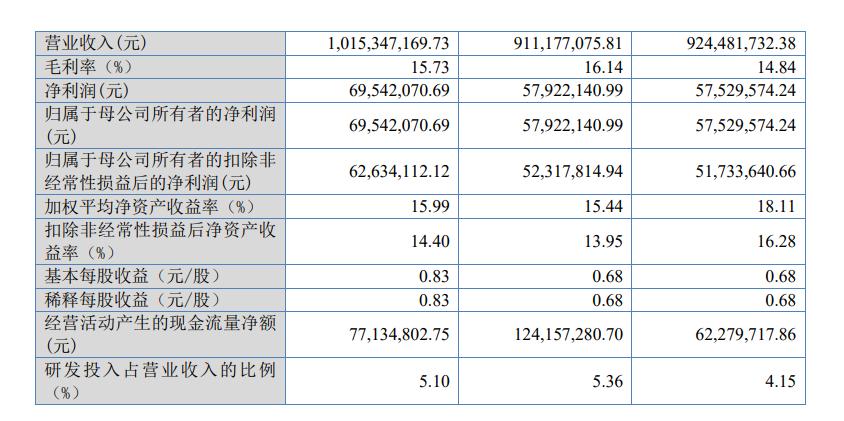
Data from the prospectus shows that the operating revenue increased from RMB 924 million in 2023 to RMB 1.015 billion in 2025, of which the revenue in 2024 decreased slightly by 1.44% and rebounded by 11.43% in 2025. The attributable net profit to shareholders was RMB 57.5296 million, RMB 57.9221 million and RMB 69.5421 million respectively; the net profit in 2024 increased by only 0.68% year on year, and grew by 20.06% in 2025.
In the first half of 2026, the company's operating revenue was RMB 551 million, a year-on-year increase of 15.29%; the attributable net profit to shareholders was RMB 40.1474 million, a slight year-on-year decrease of 0.59%. The company estimates that the operating revenue in the first three quarters will be between RMB 810 million and RMB 868 million, with a year-on-year increase of 8.94% to 16.72%; the attributable net profit to shareholders will be between RMB 56.2 million and RMB 60.54 million, with a year-on-year change range of -5.23% to 2.09%, showing a trend of revenue growth and profit pressure.
The comprehensive gross profit margin from 2023 to 2025 was 14.84%, 16.14% and 15.73% respectively. Excluding Joyson Auto, the average gross profit margin of comparable peer companies was 20.6% and 19.09%, and the company's gross profit margin was about 4 percentage points lower than the industry average. The company explained that the difference comes from the small scale of the enterprise and the weak bargaining power for downstream customers.
In terms of R&D expenses, the figures from 2023 to 2025 were RMB 38.3929 million, RMB 48.8148 million and RMB 51.7884 million respectively. Up to now, the company has only 11 invention patents, which is less than that of peer enterprises such as Aikedi and Jintuo Co., Ltd.
By the end of 2025, the company's monetary funds were RMB 31.6065 million, and its short-term loans were RMB 151 million. The scale of monetary funds is not sufficient to cover short-term loans. The consolidated asset-liability ratio from 2023 to 2025 was 65.36%, 57.86% and 57.31% respectively, which continued to be higher than the level of comparable companies; the current ratio was 1.05 times, and the quick ratio was 0.77 times.
Powertrain components for fuel vehicles are still the basic revenue base, accounting for 79.98% of the main business revenue in 2025; the revenue proportion of new energy three-electric business increased from 6.22% in 2023 to 15.21% in 2025, and this business once suffered losses in the early stage.
After the raised fund investment projects are put into operation, the annual depreciation and amortization will increase by RMB 22.4479 million. The 13.5 times issue P/E ratio has a discount compared with the industry. Whether it can support the valuation depends on the increase of the proportion of new energy business and the progress of profit recovery.