Judgments and Strategies of Top 10 Real Estate Developers in the Second Half of the Year
The 2026 interim performance reports of listed real estate enterprises have been released one after another.
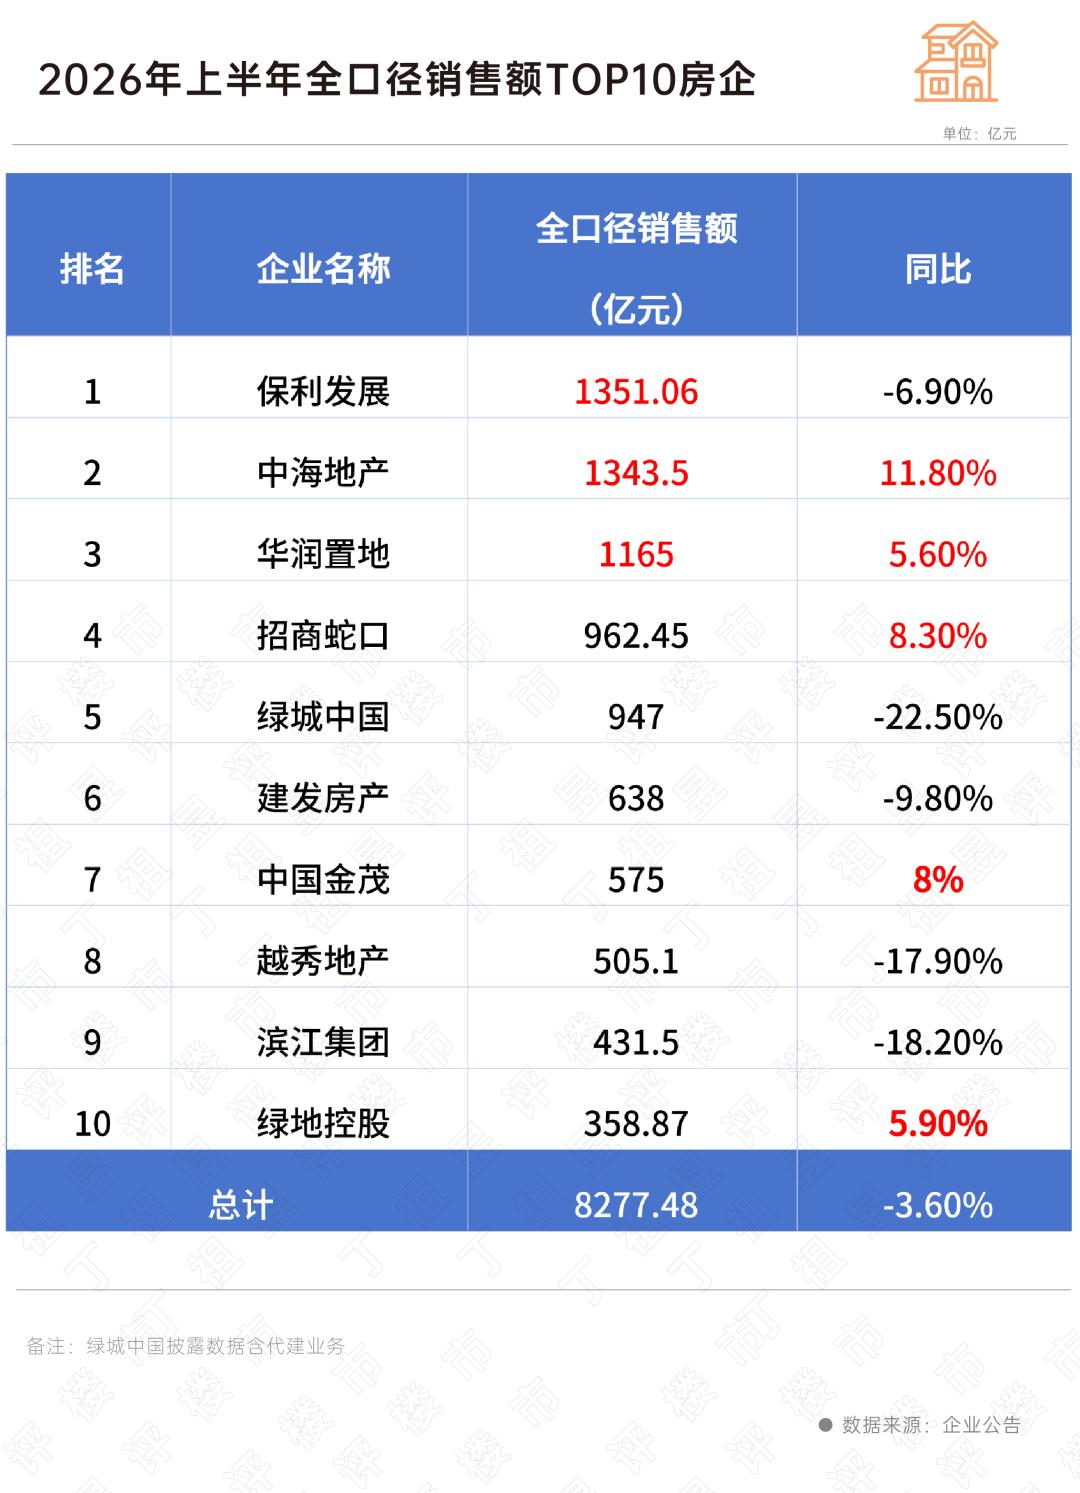
Focusing on leading real estate enterprises, taking the top 10 real estate enterprises by full-caliber sales from January to June selected by Pury Digital Intelligence Research Center as samples, the total full-caliber sales amount of the top 10 leading real estate enterprises in the first half of 2026 reached 8.27748 trillion yuan, a year-on-year decrease of 3.6%.
The market share is accelerating to concentrate on leading real estate enterprises, and the sales revenue of the top 10 real estate enterprises in the first half of the year accounted for 55.4% of the total sales revenue of the top 100 real estate enterprises (1.49492 trillion yuan).
In terms of revenue indicators, the year-on-year decline in the overall revenue and attributable net profit of the top 10 real estate enterprises is around 17%.
On the whole, the sales scale of the top 10 leading enterprises has basically stabilized, but the profitability has not been restored synchronously.
01
From the sales performance of the top 10 real estate enterprises, there are three enterprises with sales exceeding 100 billion yuan, namely Poly Development, China Overseas Land & Investment, and China Resources Land.
Among them, Poly Development ranks first steadily with 135.106 billion yuan, but the gap with China Overseas Land & Investment has narrowed significantly, with the difference between the two being only about 760 million yuan. Further looking at the sales revenue from January to August, Poly Development fell 8.9% year-on-year to 165 billion yuan, and has been overtaken by China Overseas Land & Investment.
In terms of growth rate, among the top 10 real estate enterprises, 5 of them have achieved year-on-year sales growth compared with the same period last year, and the top three enterprises in terms of growth rate are China Overseas Land & Investment, China Merchants Shekou, and China Jinmao.
Among them, the sales revenue of China Overseas Land & Investment increased by 11.8% year-on-year, which is the only double-digit growth among the top 10 real estate enterprises. By August, China Overseas Land & Investment has surpassed Poly Development and ranked first in the full-caliber sales list.
The main reason why China Overseas Land & Investment gradually overtook Poly Development in sales is that its total investment and the proportion of investment in first-tier cities are higher than those of Poly Development. From 2024 to 2025, the land acquisition amount of China Overseas Land & Investment (including China Overseas Grand Oceans) was 85.8 billion yuan and 130.4 billion yuan respectively, far exceeding Poly's 68.3 billion yuan and 79.1 billion yuan. Meanwhile, the proportion of China Overseas Land & Investment's land acquisition in first-tier cities remained stable above 72%, while Poly's proportion in first-tier cities dropped sharply to 48% in 2025.
In the first half of the year, focusing investment on high-energy-level cities and core regions has become the consensus of leading real estate enterprises.
Poly Development: The proportion of plot ratio-floor area of newly added land reserves in first-tier and second-tier cities during the period reached 80.4%, of which the proportion in first-tier cities jumped to 28.8%.
China Overseas Land & Investment: From the beginning of 2026 to mid-August, a total of 18 plots were newly added, with the proportion of first-tier and strong second-tier cities reaching 95%.
China Resources Land: Among the 16 plots acquired in the first half of the year, 99% of the funds were invested in first-tier and second-tier cities calculated by equity investment amount, and the proportion of first-tier cities reached 48%.
China Merchants Shekou: 9 plots were acquired in the first half of the year, the proportion of the 10 core cities is close to 100%, and the total proportion of first-tier cities Shanghai and Beijing accounts for 37%.
Greentown China: The proportion of floor area of land acquired in second-tier cities in the first half of the year reached 73%, and that of first-tier cities accounted for 19%. Calculated by total property value, the total proportion of first-tier and second-tier cities reached 94%.
C&D Properties: 16 new plots of land were acquired, with core layout in Shanghai, Beijing, Shenzhen, Hangzhou and other places.
China Jinmao: All 12 plots acquired in the first half of the year are located in first-tier and second-tier cities.
Yuexiu Property: 96.8% of the equity investment is concentrated in 6 core cities, and all 6 plots of land acquired during the period are located in first-tier and second-tier cities.
Binjiang Group: Investment focuses on Hangzhou. 12 plots were acquired in the first half of the year, 11 of which are located in Hangzhou.
02
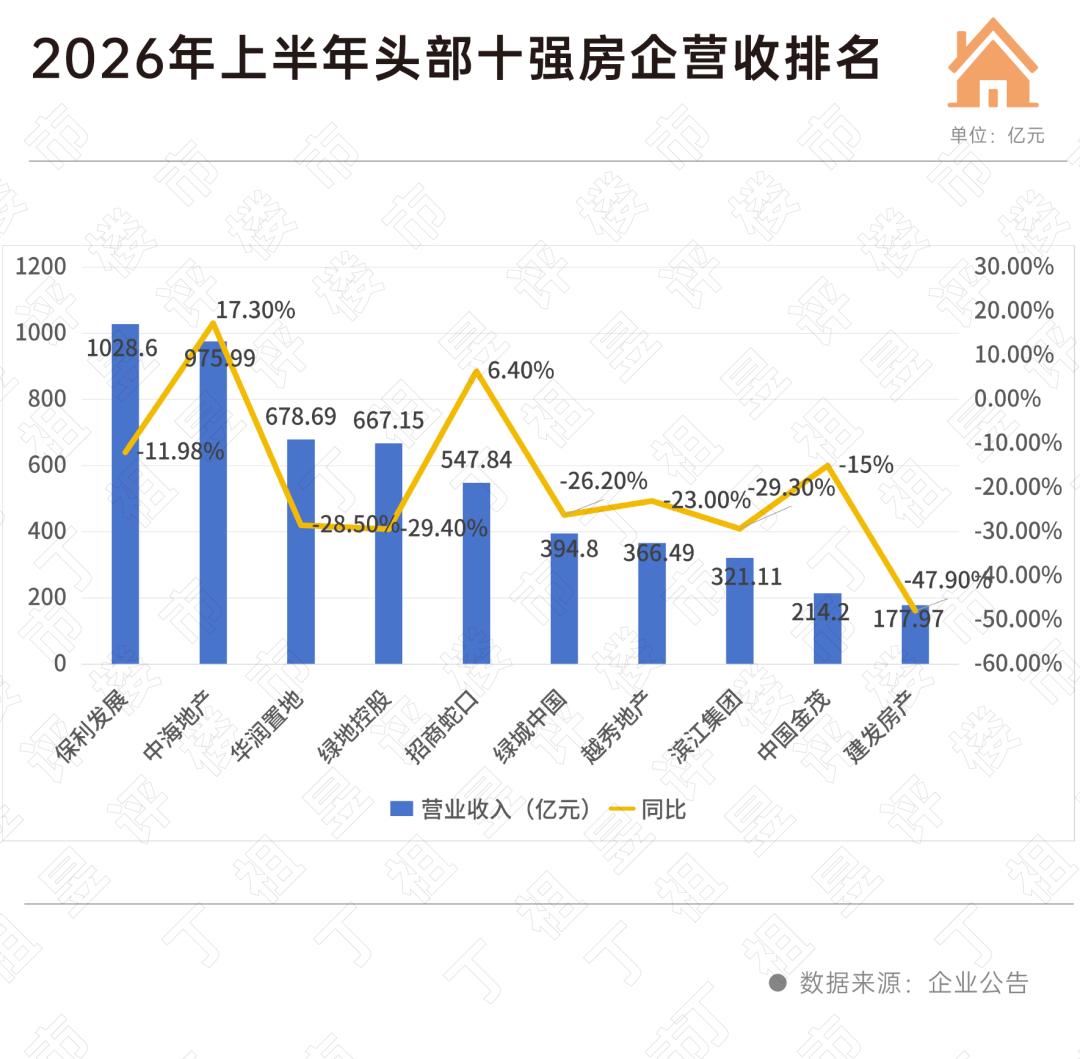
In terms of revenue, the total revenue of the top 10 leading real estate enterprises reached 5.27284 trillion yuan, a year-on-year decrease of 17%.
Poly Development is the only real estate enterprise with revenue exceeding 100 billion yuan, achieving an operating revenue of 102.9 billion yuan in the first half of the year, a year-on-year decrease of 11.98%.
Among the top 10 leading real estate enterprises, only China Overseas Land & Investment and China Merchants Shekou achieved positive revenue growth. Among them, China Overseas Land & Investment ranks second in the industry with revenue of 97.6 billion yuan, up 17.28% year-on-year; China Merchants Shekou has a revenue of 54.78 billion yuan, up 6.41% year-on-year.
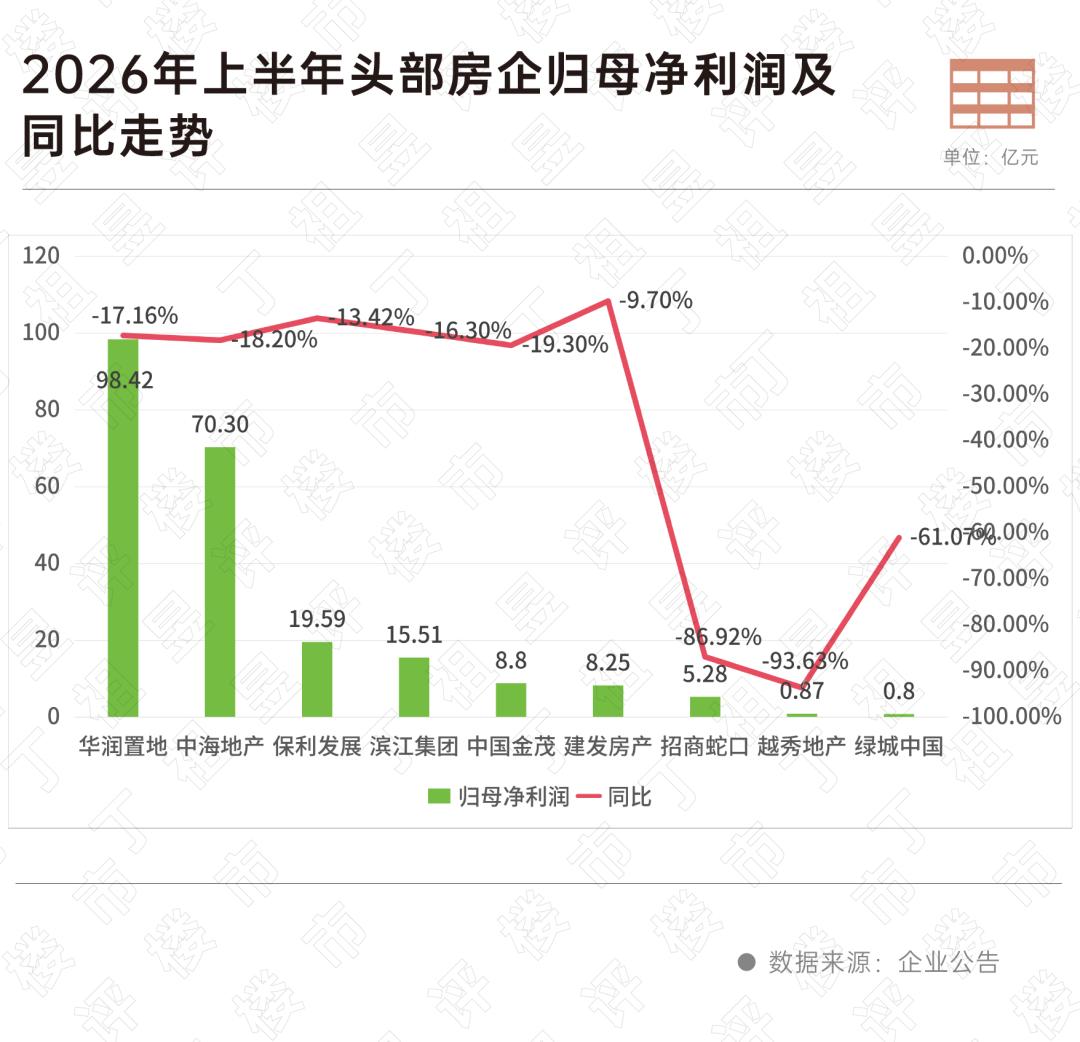
In terms of profit level, the top 10 leading enterprises all declined compared with last year.
China Resources Land still firmly holds the title of "Profit King", with the highest attributable net profit of 9.842 billion yuan in the first half of the year, but down 17.16% compared with the same period last year.
It is worth noting that the profit structure of China Resources Land has been significantly different from that of traditional development-oriented real estate enterprises. In the first half of the year, the company achieved a core net profit of 10.16 billion yuan, of which recurring business contributed 6.65 billion yuan, and the proportion rose to 65.5%. That is to say, more than 60% of China Resources Land's core profit has been contributed by the second and third growth curves, which effectively hedged the impact of the decline of development business on overall profitability.
China Overseas Land & Investment ranks second in terms of attributable net profit, with an attributable net profit of 7.03 billion yuan, down 18.2% year-on-year. In terms of profit margin, China Overseas Land & Investment's gross profit margin fell 1.3 percentage points year-on-year to 16.1%, but it has improved compared with the whole year of 2025, and the rate of return has been restored.
Among the top 10 real estate enterprises, 3 of them have a sharp decline in attributable net profit, with a decline of more than 50%. Among them, Yuexiu Property saw a decline of 94%, earning only 87 million yuan in the first half of the year. In addition, Greentown China's attributable net profit is also less than 100 million yuan, only 80 million yuan.
In terms of debt situation, the overall financial safety cushion of the top 10 leading real estate enterprises is relatively thick, and the financing cost is at a low level in the industry. It is worth noting that Binjiang Group, the only private enterprise among the top 10 real estate enterprises, has a net debt ratio of -0.76%, and its cash can cover all interest-bearing debts.
03
Sales and profit data have outlined the fundamental situation of the industry. The share of leading real estate enterprises continues to rise, but profit pressure is widespread.
Facing the intensification of market differentiation and the restructuring of the industry model brought by the August 28 existing home sales new policy, leading real estate enterprises also released their judgment on the future market and their business strategies for the second half of the year at the performance meeting.
I. On market judgment, "bottoming out", "recovery", "stabilization" and "differentiation" are still the key words
China Overseas Land & Investment: With the active implementation of policies and the further improvement of the supply-demand relationship, the foundation of market stabilization is constantly being strengthened. At present, the market presents three major differentiation characteristics: 1. K-shaped differentiation, differentiation between cities and between the central area and peripheral areas within a city. 2. Demand-side differentiation, the demand is transforming from "whether you have it or not" to "whether it is good or not". 3. Enterprise differentiation, market opportunities are mainly concentrated in first-tier and second-tier cities. Overall judgment, during the 15th Five-Year Plan period, the market will achieve phased stabilization amid differentiation.
Greentown China: The property market in the second half of the year will continue to increase transaction volume and bottom out, with severe city differentiation and transaction volume rebounding.
C&D Properties: The market needs to be observed step by step, and the next one or two years will still be a process of slow recovery.
China Jinmao: In the first half of 2026, the market is still in the process of continuous bottoming out, showing the characteristics of "weak recovery and strong differentiation". The market is gradually shifting from full competition to oligopoly competition, and it is expected that a competitive pattern where 10-15 national large-scale real estate enterprises coexist with a number of regionally deeply cultivated real estate enterprises will be formed. For excellent real estate enterprises that can cross the cycle, there will be more opportunities than challenges in the future, and the industry will usher in a new growth process after reshuffling.
Yuexiu Property: The market performance this year is low at the beginning and high at the end. A small boom appeared since March, and the strengthened policies have supported market confidence, and the supply-demand relationship is also recovering. Enterprises will strengthen research on cities, and teams in each city need to understand the city and customers. Enterprises also attach importance to cooperation with leading enterprises, strengthen pre-land negotiation with local governments, and adhere to acquiring high-energy-level plots to build improved-type housing.
II. Views on the August 28 existing home sales policy: The industry development logic will be accelerated to restructure
China Resources Land: The August 28 new real estate policy is an important measure to accelerate the construction of a new development model for the real estate industry, and it will also become the main policy keynote of the real estate industry for a long period in the future.
Its impact on the industry is mainly reflected in four aspects: First, it is conducive to continuously improving and restoring the supply-demand relationship of the primary housing market and price expectations, and high-energy-level second-tier cities will benefit earlier and more; Second, it is conducive to effectively protecting the legitimate rights and interests of home buyers and boosting the confidence of housing consumption; Third, the industry is shifting from scale priority to quality victory, and the whole chain operation mode of real estate industry including investment, production, sales and operation will usher in systematic restructuring; Fourth, it will bring certain pressure to the cash flow management of development enterprises in the short and medium term, but it is conducive to building a long-term, healthy, sustainable and high-quality development model for enterprises.
C&D Properties: Existing home sales will have a great impact on the industry in the short term. It is not only a change of node, but more importantly, the restructuring of development logic, the cycle of capital occupation is extended, and the financial cost increases. The market judgment two or three years later is also very important, and whether the land market can maintain orderly and transparency is crucial. The implementation of the existing home sales model also requires the synchronous support of supporting financial policies.
III. Land acquisition and investment strategy for the second half of the year: Prudent investment, certainty first
China Overseas Land & Investment: The annual land purchase amount is 80-100 billion yuan. While focusing on first-tier and strong second-tier cities, we will actively grasp some structural opportunities in second-tier cities, adhere to prudent investment, and consolidate the industry's scale and profitability. Aiming at improving investment certainty and return level, we will broaden land acquisition channels and seize opportunities such as mergers and acquisitions, and urban renewal.
Greentown China: The investment strategy will remain steady, adhere to the principle of "deliver every project we start", and still focus on high-end improved housing and luxury housing. It is expected that the annual land supply will maintain a shrinking trend, the competition for land in core sections of core cities will be fierce. We will adjust dynamically in combination with the overall capital situation of the company and market changes, and adhere to the annual 100-billion-yuan target.
C&D Properties: Increase the proportion of investment in first-tier and second-tier cities, adhere to diversified investment, and increase the intensity of urban renewal.
China Jinmao: In the second half of the year, we will closely follow the strategic orientation of "invest well and invest sufficiently", focus on core cities for steady layout, give consideration to both scale and efficiency, and steadily achieve the 30-billion-yuan investment target. In the third and fourth quarters, we will continue to maintain the principle of "active but not radical", seize the city window period to acquire high-quality plots at low premium. In terms of management, we will adhere to the keynote of low risk, high turnover and reasonable return, stick to the bottom line thinking, and avoid impulsive bidding at high price. In terms of urban layout, we will continue to focus on deep cultivation, no longer expand