An official approval has pushed the low-orbit satellite Internet of Things into the stage of large-scale development.
Over the past decade, China's commercial aerospace industry has launched hundreds of satellites into space. But the truly challenging part is not this step.
After satellites are in orbit, the real problem facing all participants is how to enable them to generate continuous paid usage. Globally, there are very few companies that have achieved large-scale commercial implementation of low-orbit satellite Internet of Things (IoT) services, and you can count them on one hand.
In the commercial aerospace circle, most people may still take it for granted that the next inflection point will come from a technological breakthrough, such as cheaper launches brought by reusable rockets, and larger constellations brought by mass manufacturing. However, as low-orbit satellites gradually complete constellation deployment, the industry has begun to realize that what truly determines the competitive landscape in the second half of commercial aerospace is not just technology, but who can take the lead in completing the leap from "building a constellation" to "operating a network".
This year, this inflection point has seen an important milestone.
Recently, the Ministry of Industry and Information Technology has approved the commercial trial license for satellite IoT services, with a trial period of two years. Geespace has become the first private enterprise in China to obtain this approval. This means that the private enterprise satellite IoT operation business has been officially included in the national telecommunications regulatory system for pilot operations. Relying on its own constellation, Geespace can provide global users with wide-coverage, low-power, highly reliable connection services, and simultaneously carry out IoT NTN technology tests to promote the R&D and commercial application of key 6G satellite communication technologies.
In the low-orbit satellite field, the weight of this approval is far more than adding a business qualification to private companies. More importantly, it means that China's satellite IoT has officially entered a new stage from "building a network" to "operating a network".
In 2026, the satellite Internet was written into the government work report as a separate item for the first time, and then included in 109 major projects of the "15th Five-Year Plan"; in April, the China National Space Administration and the State Administration for Market Regulation jointly released the "Commercial Aerospace Standard System (Version 1.0)". From the government work report to the "15th Five-Year Plan", and then to the construction of the industry standard system, the signal released at the national level is very clear: commercial aerospace is fully entering the window period of industrial implementation from the technology verification stage.
The approval was launched right at this critical juncture.
It can be said that this approval is not only an institutional confirmation of the industry's capability accumulation over the past decade, but also an important starting point for China's satellite IoT to move towards large-scale commercial operation. The signal it releases is very clear: future industry competition will no longer only compete on the number of satellites, but on who can build a stable, safe and continuously operating satellite communication network that truly serves industries and users.
Judging from the capabilities demonstrated by the approved enterprises this time, the answer is gradually becoming clear: the real competition in commercial aerospace is moving from "manufacturing satellites and forming constellations" to "operating networks", and from "capability building" to "value realization".
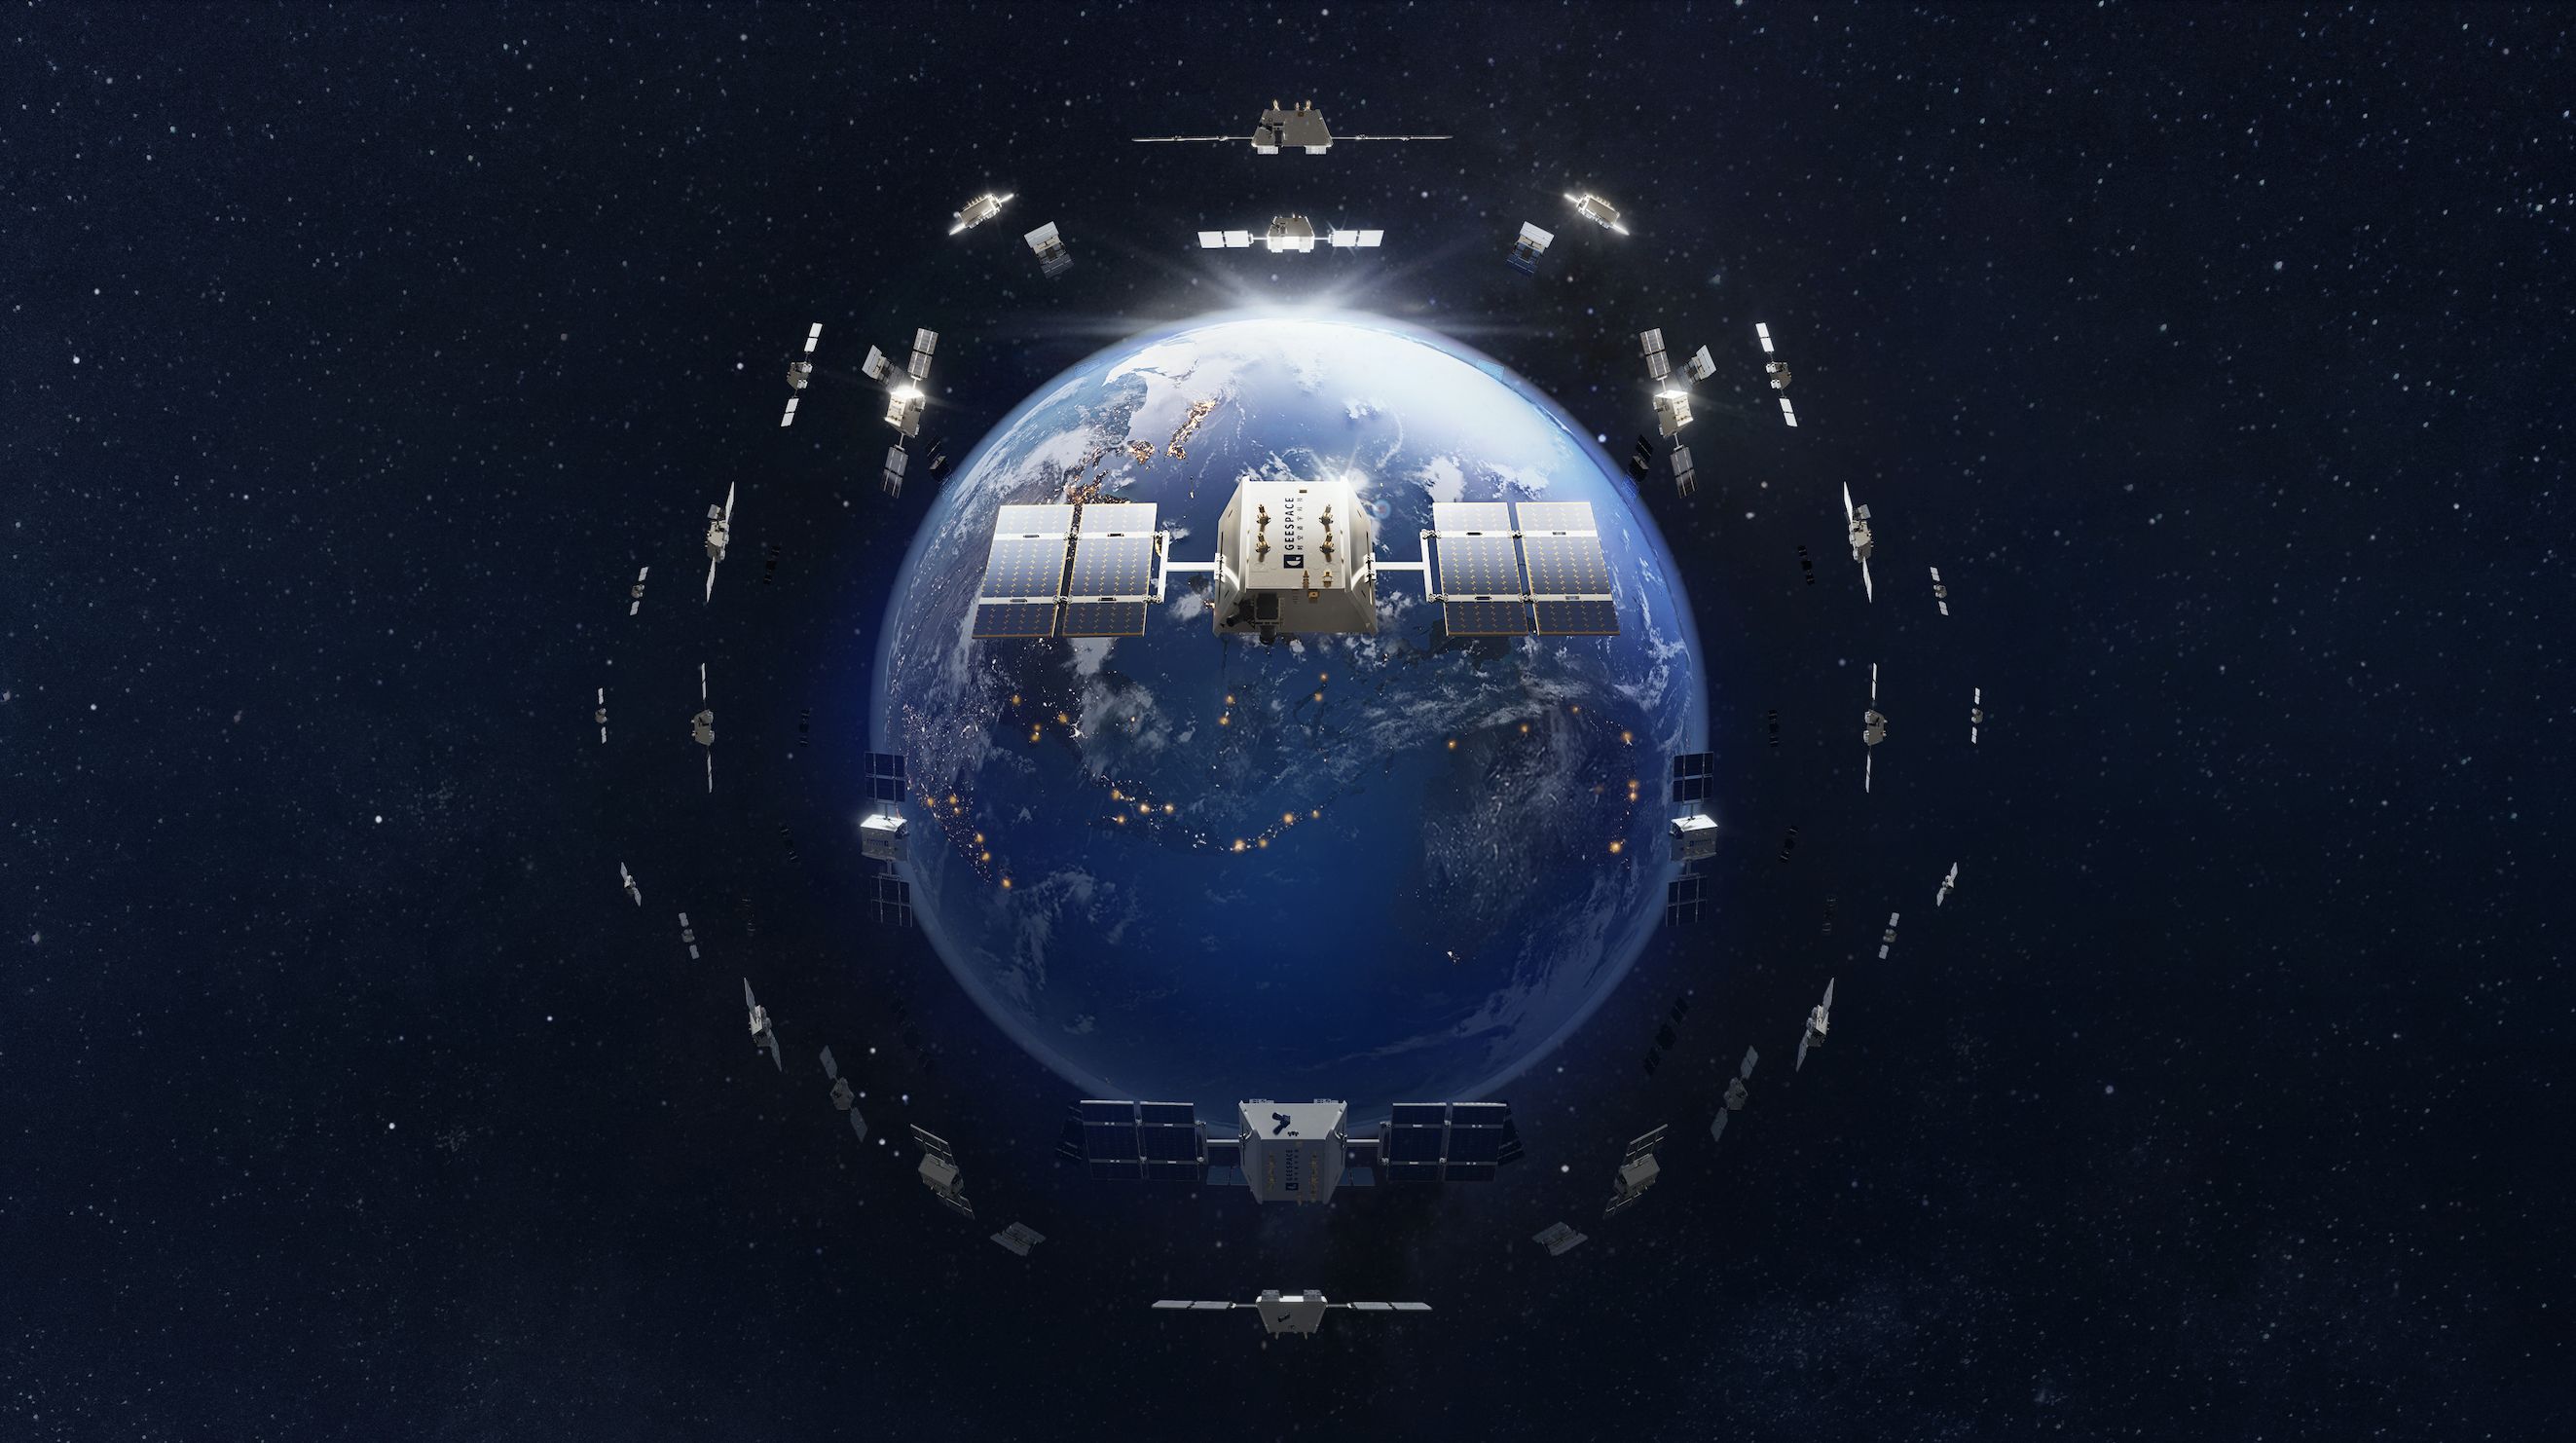
Geespace Constellation
01. Rules are more scarce than technology
Why is a commercial trial approval regarded as an industry inflection point?
Wang Yang, CEO of Geespace, has a judgment: when a new infrastructure industry truly matures, it is not that technology becomes more complex, but that rules become clearer.
All infrastructure industries have to go through three stages: technology maturity, rule maturity, and market maturity.
Today's low-orbit satellite IoT is at a critical point of evolution from the second stage to the third stage. The technology can already support large-scale applications, and constellation capabilities, terminal products and industry applications are all moving towards maturity. However, whether terminal manufacturers, industry customers and operators are willing to invest money and resources in the long term depends on whether the rules can provide deterministic expectations.
Without definite rules, participants in the industry can only stay in project-based and phased cooperation. No one dares to make long-term investments in R&D, products and markets, and the industry cannot form real economies of scale.
This is exactly the industrial significance of obtaining the approval: operating under long-term rules will become the new normal of the industry, delivering a determinable bet to the upstream and downstream of the industrial chain.
In addition, to understand why this approval is scarce, we must first see how difficult the low-orbit satellite IoT business itself is.
The low-orbit satellite IoT constellation is essentially an infrastructure built in space. To become a chain-leading enterprise in this field, a company must simultaneously master the full-chain capabilities including constellation system design, satellite R&D, mass production AIT, constellation TT&C operation and control, as well as R&D, mass production and application of core chips, modules and terminals. None of these links can be missing.
As long as one link relies on external resources, large-scale services will face huge challenges.
This is very different from the consumer-grade satellite Internet. The latter competes for bandwidth and speed, and can quickly make up for shortcomings by outsourcing some links; while the IoT constellation competes for coverage, reliability and long-term stability, any weak link will be infinitely amplified.
More critically, this is a business with heavy assets, long cycles and slow returns. The investment payback period is long, and value can only be realized through long-term cooperation with operators and vertical industry customers, which naturally excludes enterprises that pursue short-term returns and are eager to tell capital stories.
With such a high threshold, there are very few commercial aerospace enterprises that have achieved large-scale implementation worldwide, and most players are still stuck in the first two stages of capability building and scale construction.
A mature market, that is, large-scale commercial implementation, is a huge gap across the entire industry. The combination of technical thresholds and commercial gaps determines that approvals will not be issued universally, and the marked inflection point is scarce and weighty enough.
It is precisely for this reason that the domestic enterprises that can take the lead in obtaining this approval must be the most well-prepared players.
Wang Yang's three-stage theory of "capability building, scale construction, and value realization" is an important cognitive anchor for the industry. Its underlying implication is that once the barrier from capability to scale is broken through, which is catalyzed by clear rules, the industrial expansion speed will accelerate significantly.
All participants can obtain long-term expectations, dare to invest resources in real terms, and value can be realized.
In 2018, when Wang Yang founded Geespace, the entire commercial aerospace industry was still solving the problem of "whether it can be done". The industry was generally chasing the high-speed broadband consumer track, but he chose the satellite IoT path that few people took.
At that time, this track did not have an independent industrial classification, but he saw the underlying logic behind it: higher user concentration, stronger payment capacity, more stable demand, and the revenue is closer to the long-term service income of infrastructure-type businesses, rather than the traffic monetization model of consumer Internet.
Nowadays, while peers are still competing on technology, he has already started preparing for large-scale operations after the rules mature.
As a result, under the rule dividend of approved operation, Geespace has seized a unique ecological niche.
02. Why Geespace?
Mature rules bring more opportunities. So, apart from starting earlier, why can Geespace become one of the few private enterprises that take the lead in obtaining approval?
The answer lies in the access threshold for approval: the application conditions for commercial trial approval are far stricter than the outside world imagines.
According to the "Notice on Organizing and Carrying out Commercial Trials of Satellite IoT Services" issued by the Ministry of Industry and Information Technology, the applying enterprise must simultaneously meet five core requirements: it has obtained the satellite mobile frequency use license and space radio station license; the constellation construction project has been approved by the National Development and Reform Commission; it has an on-orbit serviceable satellite system and supporting ground operation and control support system; it has complete capabilities in network security, data security and emergency support; it can provide long-term and stable services across the country.
This means that the approved enterprise must not only own satellites, but also have a complete capability system covering the space segment, ground segment, operation services and security guarantee, and can truly undertake the operation and service of satellite IoT across the country and even globally.
The combination of the five conditions requires the approved party to hold five tickets at the same time: frequency and orbit resources, project approval, on-orbit system, security capability, and long-term service capability.
This is also where most players are "stuck out". The constellation networking is not completed, so there is no industry service to speak of; relying on external technology, there is no security compliance to speak of; without passing commercial verification, there is no long-term stable service to speak of.
Looking at each condition separately, many enterprises have crossed the threshold, but very few enterprises can hold all five at the same time. Geespace has crossed the threshold in every item, becoming one of the few domestic enterprises that can meet all five requirements simultaneously.
The confidence to cross the five conditions comes from a complete industrial chain.
Different from other commercial aerospace enterprises, Geespace's capability chain extends from constellation system design and satellite R&D and manufacturing to chips, modules, terminals and industry applications, and it independently develops everything from "the network in the sky" to "the terminals on the ground".
From the perspective of business attributes, this company is forming dual capabilities similar to "China Mobile + Huawei": network operation and user connection are the strengths of operators, while communication technology R&D and terminal industrial chain are the fields of equipment vendors. These two things usually belong to two types of companies, but Geespace has integrated them into one system.
The specific capabilities of this company can be viewed from three dimensions.
Network capability is the foundation, and also the physical premise for obtaining the approval. Most players are still in the networking stage, but Geespace has 64 satellites in orbit with 100% reliability, which can process about 340 million communication requests per day, serve 20 million users, and achieve global communication coverage except for the North and South Poles.
What is more difficult to replicate is the self-developed security base. Full-stack self-development plus self-developed communication system and private protocol make Geespace irreplaceable in scenarios with extremely high security requirements such as intelligent connected vehicles, energy and transportation.
Such scenarios have far higher requirements for data security and link anti-interference than ordinary commercial services, and the cost of interruption or leakage is huge, while compliance and security boundaries are the most valued parts of approved operations.
Differentiated positioning opens the ceiling of large-scale development. Geespace focuses on the UHF/VHF frequency band, pursues "always on", and accurately occupies the ecological niche of the ultimate backup network. Combined with miniaturized, low-power terminals, it fully explains why this company can take the lead in realizing large-scale development during the approval window period.
Behind the capabilities is long-term strategic determination. Starting early, venturing into no-man's land, and choosing the long-term infrastructure subscription business, it has built today's barriers.
In China, Geespace has completed commercial verification tests in cooperation with more than 20 leading enterprises such as China Unicom, PetroChina, Geely Auto, and CaoCao Mobility; during the just-concluded MWC (Mobile World Congress) Shanghai exhibition this year, it has accumulated cooperation intentions with more than 200 ecological partners, the signed orders exceeded 100 million yuan, and its business territory covers ten core real economy tracks including intelligent connected vehicles, marine fisheries, smart agriculture, construction machinery, energy, low-altitude economy, and emergency communication.
The order number is a very positive signal, proving that Geespace, which has entered the era of licensed operation, will no longer stay in the dimension of demonstrative and project-based cooperation, and it is entering a truly repurchasable and scalable commercial stage.
03. From networking competition to value realization
Barriers have been built, and they will eventually be converted into commercial value.
After obtaining approval, where is the new valuation logic for satellite IoT, and how to quantify its market value?
Overseas markets have already given references. SpaceX's total revenue in the first half of 2026 was 12.506 billion US dollars, a year-on-year increase of 53.7%. Starlink contributed the largest share of revenue, with an operating profit of 2.844 billion US dollars, making it the company's strongest profit engine. What supports SpaceX's high valuation has shifted from rocket launch capabilities to the continuous profitability of Starlink as the world's largest low-orbit satellite communication operation network.
In the domestic market, at least from the perspective of Geespace, the approval has also pushed the company's growth logic from project-based delivery to a continuous service revenue model, which will become an important basis for the future value revaluation of the entire industry.
The leap of commercial logic is most intuitively reflected in globalization. Geespace has established cooperation with telecom operators in more than 20 countries in Asia, Africa, Latin America and other regions, and has obtained orders from many markets in the Middle East and South America. It will promote the delivery of these orders in 2026. With the expansion of overseas business, the revenue structure is shifting from one-time projects to long-term service subscriptions.
For the capital market, the switch from selling projects to selling services also means predictable cash flow and higher valuation multipliers.
Open source for the industry is another path worthy of attention. During MWC Shanghai this year, Geespace released the world's first full-stack open source ecology for low-orbit communication constellations, opening capability interfaces to operators, chip manufacturers and system integrators to lower the industry entry threshold.
The maturity of an infrastructure industry is never completed by a single company alone, but by growing a complete ecosystem around it. In essence, open source is Geespace transforming its proven capabilities into reusable underlying assets for the industry, thereby promoting the market to mature faster.
After the completion of the first phase of networking, Geespace's next step is to accelerate the construction of the second phase of the constellation and continue to improve the service capability of the constellation system. Looking further ahead, it is betting on 6G:
Ground networks are constrained by geographical conditions. Oceans, deserts, plateaus and low altitudes have long been communication blind spots. The core proposition of 6G is to deeply integrate satellite networks with ground cellular networks to realize integrated space-ground global communication.
In the 3GPP system, this path is divided into two technical directions: IoT NTN is oriented to massive low-power IoT terminals, focusing on wide coverage and low power consumption, adapting to industry scenarios such as construction machinery, marine fisheries, energy and water conservancy, and is the most easily implemented commercial track at present; NR NTN is based on the 5G NR framework, oriented to direct satellite connection for mobile phones, supporting voice and low-speed data transmission, and is the ultimate form of 6G NTN.
The relationship between the two is complementary and evolutionary. First use IoT NTN to complete industry verification and accumulate on-orbit data, then evolve to NR NTN, opening up the B-end and C-end markets successively.
The current consensus is that 6G will bring a window of opportunity for China's commercial aerospace. The existing low-orbit constellations in the United States do not natively support the 6G NTN protocol. When 6G is deployed on a large scale, the existing satellites of Starlink will face the pressure of expiring service life and overall replacement, and for the first time, everyone is standing on a nearly equal starting line.
Geespace has skipped the iteration of the old generation of technology, and simultaneously laid out two routes of IoT NTN and NR