Pop Mart is going to distribute all the profits it earned last year.
Author | Xie Yunzi
Editor | Zhang Fan
After the market closed on August 20, Pop Mart released its 2026 interim results.
Looking at the financial report, the mixed performance is very obvious: the revenue in the first half of the year reached 17.17 billion yuan, a year-on-year increase of 23.8%; the adjusted net profit was 5.16 billion yuan, a year-on-year increase of 9.5%. Revenue is still growing, but the net profit growth rate has dropped to single digits; the gross profit margin is 69.7%, a slight decrease of 0.6 percentage points compared with the same period last year.
The capital market responded to this result with a decline.
The day after the financial report was released, Pop Mart's stock price fell by more than 3%, and its total market value fell back to HK$198.4 billion. This is far from the grand occasion when LABUBU became popular all over the world and its market value exceeded HK$435.9 billion.
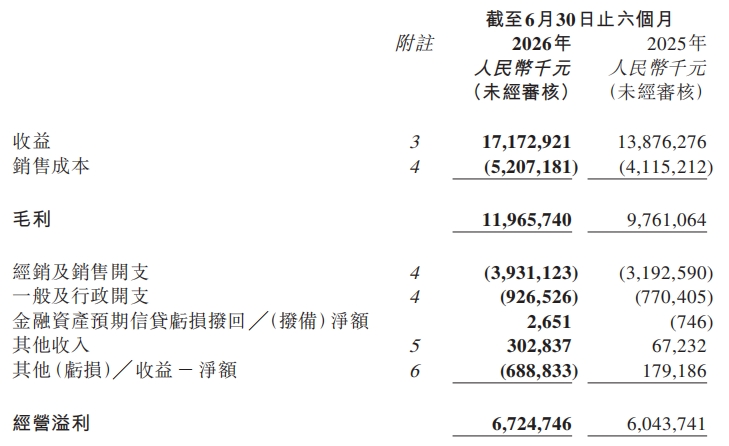
Screenshot from 36Kr, sourced from the financial report
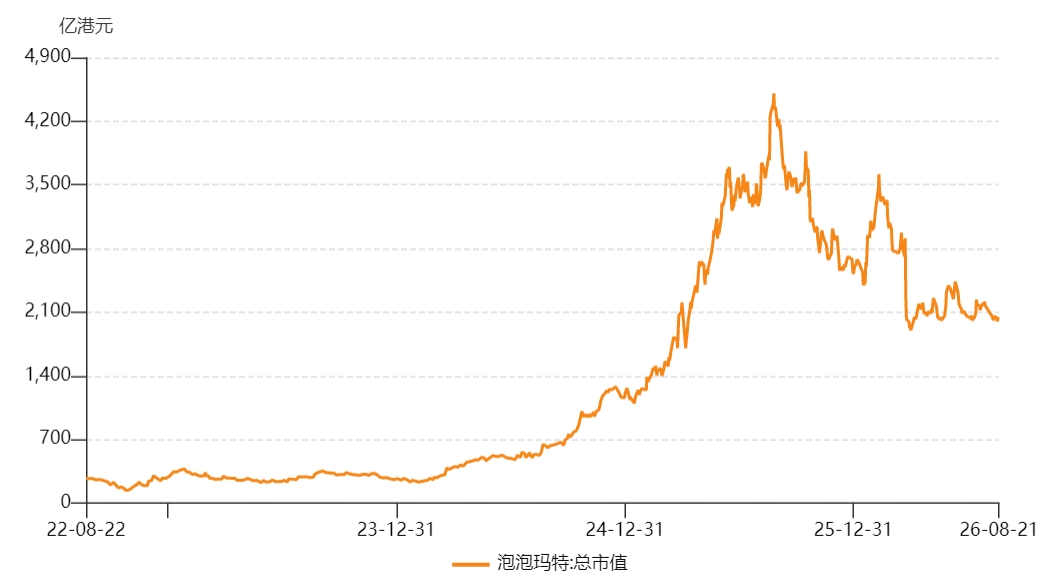
Screenshot from Wind
If we pull up the timeline, Pop Mart was still in a period of rapid growth in 2025 —— its full-year revenue reached 37.12 billion yuan, a year-on-year increase of 184.7%. At that time, Wang Ning, the founder of the company, said, "I feel that hitting 30 billion yuan this year is very easy."
The cost of this rapid growth emerged intensively in 2026.
At the half-year results meeting, Wang Ning said frankly that this year is the "operation adjustment year". The pressure in the first half of the year is greater than expected, and the pressure in the second half will only be greater. "It is very likely that the 20% growth target set at the beginning of the year will not be achieved."
This prediction of "failing to meet the target" is consistent with the quarterly data.
In the first quarter of this year, Pop Mart's revenue increased by 75%-80% year-on-year, and the Chinese market even doubled; but in the second quarter, the growth slowed down significantly. Referring to the overall growth rate in the first half of the year, the growth rate in the second quarter may drop to single digits.
Along with this, the overseas market has hit an "emergency brake".
In 2025, overseas business was still the strongest growth engine for Pop Mart: full-year overseas revenue was 16.268 billion yuan, a year-on-year increase of 292%, and the revenue proportion rose from 31.8% to 43.8%, with the growth rate in the Americas region once reaching as high as 748%.
However, in the first half of 2026, the revenue of overseas business was 4.972 billion yuan, a year-on-year decline of 11%. Revenue in the Asia-Pacific region was 2.58 billion yuan, down 9.7%; the Americas plummeted 16.5% to 1.89 billion yuan; only Europe achieved a 5.9% growth, with revenue of 510 million yuan. The proportion of overseas revenue also dropped sharply from 43.8% for the whole of last year to about 29%.
The reasons behind this are multiple.
Si De, Chief Operating Officer of Pop Mart, said that the high overseas growth last year was largely driven by LABUBU, and a large number of new users lacked awareness of trendy toy culture and were not familiar with other IPs of the brand; most of the overseas team were new hires last year, whose "professional accumulation is even less than that of ordinary users".
A more realistic pain point lies in the supply chain. The management mentioned at the results meeting that in the US market, "the quantity that can be shipped there is very small, and the cost that may eventually be required for air freight is very high".
The decline in sales and transportation difficulties are directly reflected in the inventory. As of the first half of 2026, Pop Mart's inventory turnover days have risen from 123 days at the end of 2025 to 201 days. The inventory balance increased from 5.47 billion yuan to 6.1 billion yuan. The extensive growth of overseas expansion is returning to refined operation.
The change in IP structure is another hidden line of the half-year report.
The THE MONSTERS family, to which LABUBU belongs, generated 4.45 billion yuan in revenue in the first half of the year, still ranking first, but its revenue proportion has dropped from 38.1% in 2025 to 26%, a year-on-year decrease of 7.5%. This super IP, which once supported Pop Mart's global popularity on its own, is experiencing a natural life cycle adjustment.
The one taking over is Starry.
In the first half of the year, Pop Mart had 6 IPs with revenue exceeding 1 billion yuan and 11 IPs with revenue exceeding 100 million yuan, and the diversification of the IP matrix has indeed made progress. Among them, the revenue brought by Starry reached 2.65 billion yuan, a year-on-year surge of 580.6%, and the revenue proportion jumped from 2.8% to 15.4%, becoming the group's second largest IP.
In addition, mainstream IPs such as CRYBABY, DIMOO, SKULLPANDA and Hirono all maintained double-digit growth. Si De specifically said that SKULLPANDA, Hirono, and even Nyota and Peach Riot have achieved good performance in the European and American markets.
Since 2026, Pop Mart has successively launched the "Nyota Tiny Moments" vinyl figure series and the "Nyota × Chibi Maruko-chan" co-branded series, which also demonstrates the company's continuous investment in "mid-tier IPs".
Divided by product category, plush toys achieved revenue of 9.83 billion yuan, a year-on-year increase of 60%, contributing 57.2% of the group's revenue. The figure category remained relatively stable, with sales revenue of 5.19 billion yuan in the first half of the year.
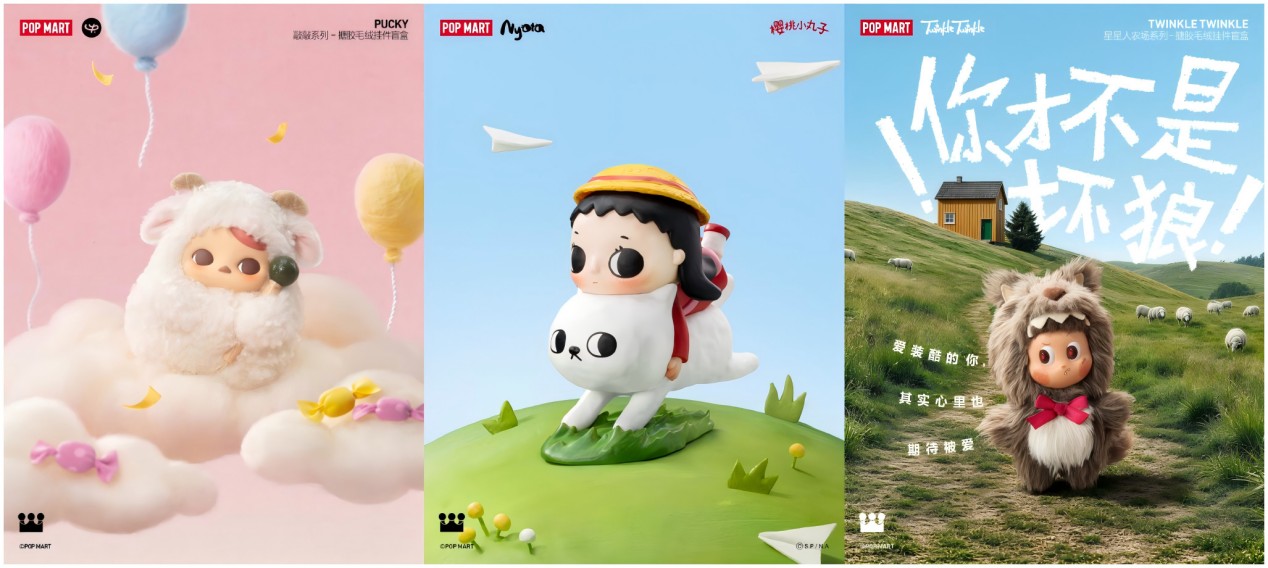
New products of Pop Mart in the first half of the year; screenshot from the official Weibo account
However, hidden worries also exist.
In the first half of this year, MOLLY's revenue was 900 million yuan, a year-on-year plunge of 33.6%. This is also the first time that MOLLY, the "veteran IP", has dropped out of the 1-billion-yuan camp since 2023.
Si De said that MOLLY will launch a major breakthrough product at the end of this year or in the first half of next year. "We hope to help MOLLY show people some more eye-catching and different product forms beyond the traditional product line."
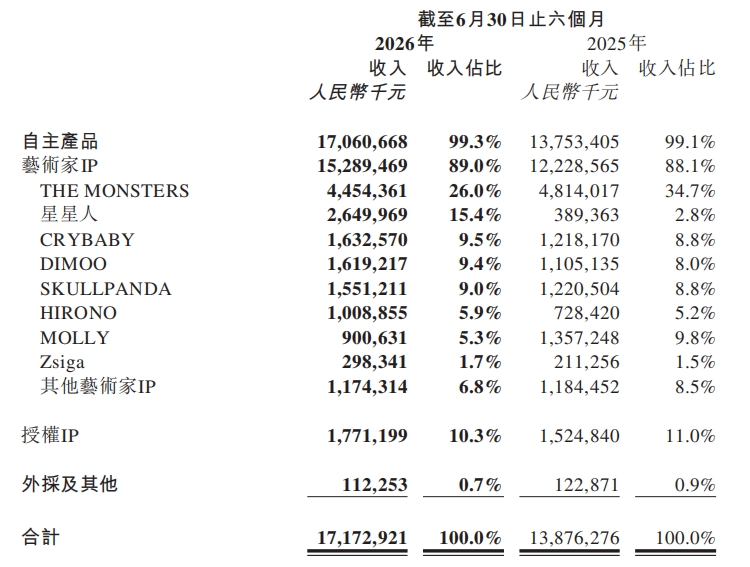
Screenshot from 36Kr, sourced from the financial report
While the market is waiting and seeing, Pop Mart also needs to "defend profits".
During the reporting period, the company's gross profit margin was 69.7%, down 0.6 percentage points from the same period of the previous year, mainly due to the decline in the proportion of overseas revenue and the rise in raw material costs affected by unstable factors in the international situation.
In terms of various expenses, the sales and management expenses in the first half of the year increased by 895 million yuan compared with the same period last year. The reason is that 105 new offline stores were added globally during the reporting period. Even after adjustment, Pop Mart's net profit margin remains at the level of 30%.
In the second half of this year, Pop Mart still plans to open more new stores in overseas markets. For the Chinese market, continuous upgrading and renewal will also be carried out. But Wang Ning emphasized —— this year the company will not pursue a particularly aggressive growth mode that increases revenue without increasing profits.
This means that Pop Mart has put profit growth above scale expansion.
In addition, in response to the anxiety of the capital market, the company will launch a share repurchase plan of 2 billion to 5 billion yuan in the next 6 months.
This is not a random decision. After the release of the performance in March this year, Pop Mart's stock price fell, and the company repurchased nearly HK$1.4 billion in 6 consecutive trading days. Since the beginning of the year, Pop Mart has cumulatively repurchased about HK$1.74 billion.
It is worth noting that roughly calculated, superimposing the 3.2 billion yuan of dividend distribution implemented in the first half of the year, Pop Mart's total expenditure on "dividends plus repurchases" this year is between 6.7 billion yuan and 9.6 billion yuan. The company's net profit last year was 12.78 billion yuan, and its operating cash flow was 10.8 billion yuan.
In other words, Pop Mart is going to "distribute all the money it earned last year". This company is using "extremely high shareholder returns" to stabilize the trust of investors and hedge against the uncertainty of future performance.
Overall, Pop Mart in the mid-2026 period reflects the complex status of the company in the transition period from rapid growth. In the future, whether Starry can withstand the pressure, whether the overseas market can recover, whether the LABUBU feature film can continue to be promoted, and whether Pop Mart can truly become an IP platform, will be revealed in the second half of the year and even longer time.
Follow for more information