Earning 15,000 times the return, why did Zhang Yiming's angel investor decide to exit?
The angel investor behind Zhang Yiming is retreating from China's VC market.
According to related reports, Susquehanna International Group (SIG), a US financial conglomerate, is gradually scaling down its China-focused venture capital team, namely SIG Asia Investments.
Gong Ting, the managing director who has overseen China's operations for nearly two decades, is expected to step down to launch a new fund with a fundraising target of at least $100 million, and SIG may even become a limited partner of this new fund. Going forward, SIG Asia Investments will only retain a small number of employees to manage legacy projects that have not yet been exited.
The most significant investment in SIG Asia Investments' portfolio is undoubtedly ByteDance.
In 2012, when Zhang Yiming was preparing to found ByteDance, SIG Asia Investments was one of the earliest institutional investors to place a bet on him. Its initial investment was merely $80,000; later, it continued to inject additional capital and participated in ByteDance's $5 million financing round in the very year of the company's establishment. As of 2024, SIG Asia Investments was reported to still hold approximately a 15% stake in ByteDance, making it one of the company's most important external shareholders.
This is arguably the most profitable early-stage investment in the history of China's venture capital market: based on the latest valuation, the book value of SIG Asia Investments' holdings exceeds $90 billion, delivering a return of 15,000 times.
Yet now, SIG Asia Investments, which holds this valuable asset, has decided to stop searching for the next Zhang Yiming.
01
More Than a Successful Bet on ByteDance
SIG Asia Investments has always stood out as somewhat of an outlier in China's investment landscape.
SIG, the entity behind it, whose full name is Susquehanna International Group, is headquartered in Bala Cynwyd, a suburb outside Philadelphia, Pennsylvania, United States. SIG's core business is not venture capital, but quantitative trading, options market making, and securities trading.
In 1987, Jeff Yass and several of his university classmates who shared a passion for mathematics and poker co-founded SIG. To this day, the company still regards poker as a vital tool for training its traders. New employees spend a significant amount of time playing cards during their training period, learning to assess probabilities, manage positions, and accept that their judgments may be wrong when faced with incomplete information.

Susquehanna International Group has a deep-rooted poker culture
This mindset has also been integrated into SIG Asia Investments' operations.
Traditional VC firms typically raise capital first from pension funds, university endowments, sovereign wealth funds, and family offices, then invest and exit investments over a fund cycle of about 10 years. Fund managers earn management fees and performance carry, while being required to regularly report their performance to external LPs.
In contrast, SIG Asia Investments has long primarily used capital from SIG's own partners.
This means it faces far less pressure to raise funds, and does not need to rush to sell a growing company simply because a fund is approaching its maturity date. As long as a project is sufficiently promising, it can hold the stake for the long term; when the industry experiences fluctuations, it can also continue to place new bets. The full significance of this capital structure became apparent only after ByteDance grew into one of the world's most valuable unlisted technology companies.
To a certain extent, SIG Asia Investments is more like a long-term trading account opened by SIG in China, rather than a standardized venture capital fund.
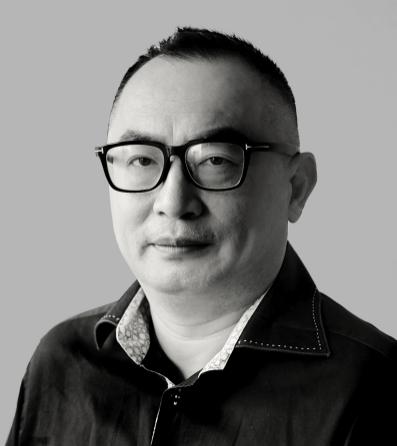
Gong Ting has served as the Managing Director of SIG Asia Investments since January 2006.
Gong Ting is not a typical star investor either.
He earned his bachelor's degree in Applied Physics from Shanghai Jiao Tong University (class of 1984), then obtained a doctorate in Electronic Engineering from Princeton University. He once worked as an assistant professor and researcher at the University of Rochester, and also engaged in real estate investment, corporate management, and angel investment. He founded the unified communications company Hotvoice, but his entrepreneurial endeavor ultimately did not succeed.
In January 2006, Gong Ting joined SIG Asia Investments and has since long overseen its China business. Prior to that, he had already worked as an entrepreneur, professor, consultant, and investor. Compared with young investors who transition directly from investment banks or consulting firms to the VC industry, he has a deeper understanding of how startups fail.
In his early years, Gong Ting rarely set strict industry boundaries for SIG Asia Investments. He explicitly stated that SIG Asia Investments dislikes following industry trends and competing for popular deals. As long as an investment can capture the growth of the Chinese market, sectors such as catering, car rental, medical services, and the internet are all viable investment targets. Instead of betting heavily on a single specific track, SIG Asia Investments focuses more on companies that have not yet been fully recognized by capital, entrepreneurs who are worthy of long-term trust, and the possibility of continuing to invest capital and hold stakes for the long term once the business model is proven successful.
Up to now, SIG Asia Investments has invested in more than 350 companies, with a total cumulative investment of over $3.5 billion. Its publicly disclosed portfolio includes ByteDance, Home Inns, Country Style Cooking, Bona Film Group, Damai.cn, Ximalaya, Agora, Mobvoi, FlashEx, Crystal Tech, and Musical.ly, among others.
SIG Asia Investments even managed to invest in Musical.ly. In 2017, ByteDance acquired Musical.ly and later integrated it with TikTok. This means SIG not only successfully bet on the information distribution platform that later swept across China, but also secured a crucial piece of the puzzle for TikTok's global expansion in advance.
02
Admitting the Limits of One's Knowledge
The most iconic object associated with the ByteDance investment story is a napkin.
In 2007, SIG Asia Investments invested in Quxiu.com, and Managing Director Wang Qiong was dispatched to the company as the investor representative. At that time, 24-year-old Zhang Yiming was the chairman of Quxiu's technical committee. After that, Wang Qiong continued to follow Zhang Yiming's developments. In 2009, SIG Asia Investments invested in 99fang, a company spun off from Quxiu's real estate search business, and supported Zhang Yiming to lead this project.
Although 99fang did not grow into a large company, Zhang Yiming established a solid track record of credibility.
After the Spring Festival in 2012, Zhang Yiming arranged to meet Wang Qiong at a café near Zhichun Road in Beijing. Instead of preparing a complete business plan, he drew a product prototype on a napkin: a system that continuously recommends personalized content based on users' interests.
That was the core logic behind what later became Toutiao.
Public reports have different accounts of the size of SIG Asia Investments' early-stage investment. Some reports state that the initial investment was $80,000, followed by an additional $2 million a few months later; others claim that the total early-stage investment amounted to between $5 million and $6 million. The consistent part across all accounts is that SIG Asia Investments was ByteDance's earliest large-scale institutional supporter, and Gong Ting and Wang Qiong were the main driving forces behind this transaction.
However, the napkin is just a story that is easy to spread.
The real challenge of this investment was not understanding the recommendation algorithm over a coffee at a café, but having a large financial group willing to trust the non-standard information accumulated over a long period of time by its local team.
Zhang Yiming did not have a glamorous, polished resume, nor a carefully crafted business plan. In the early days, Toutiao was not an easy business to explain either. News content involved copyright issues, the advertising model had not been validated, the mobile internet was just in its infancy, and companies including Baidu, Tencent, and Sina had already controlled a large number of traffic entry points.
The reason they could make the investment was that Wang Qiong had observed Zhang Yiming for years. She knew how he managed products and how he faced the failure of 99fang. Gong Ting, as the head of China's business, was willing to provide organizational support for this judgment.
In other words, SIG Asia Investments' advantage did not lie in its headquarters having a better understanding of China's internet sector than others.
On the contrary, its advantage was that its headquarters acknowledged its lack of local knowledge, and thus delegated sufficient decision-making authority to the team members who lived, worked, and built connections in China.
Gong Ting's role in this process was not to personally identify every single project.
His more important capability was to establish a mechanism that allowed frontline investors to make non-consensus judgments. The core of a top-tier investment institution is not that every transaction is personally approved by the most famous partner, but that those who truly master the relevant information have the right to place their bets.
In exchanges between Pencil News and several investors, those who are familiar with Gong Ting describe him as a "good big brother" who takes care of young people like a senior mentor.
Gong Ting himself has long maintained a low profile.
During the most prosperous era of China's VC industry, many investors turned themselves into public figures through speeches, social media posts, and public debates. Gong Ting rarely appeared in the limelight. He once stated that investors should be "unsung heroes behind the scenes", and he believed that VC is a career more suitable for the later stage of a professional path, because investment requires comprehensive experience accumulated from entrepreneurship, corporate management, and even failures.
This low-profile stance sometimes leads the public to underestimate his contribution.
03
A New Phase for US Dollar-Denominated Investments
SIG winding down its China venture capital team does not mean it is completely exiting the Chinese market.
According to related media reports, SIG will retain a very small team to continue managing its equity assets in companies like ByteDance that have not yet been exited. At the same time, SIG is still expanding its securities trading and market-making businesses in China. What has been shut down is mainly the VC team responsible for sourcing startups, negotiating financing terms, and making new equity investments.
In 2026, China's venture capital market is actually in a recovery phase.
Relevant industry data shows that in the first five months of 2026, the total amount of VC and PE investment in China reached 620 billion yuan, representing a year-on-year increase of nearly 60%; during the same period, the scale of newly registered venture capital funds reached 154 billion yuan, exceeding the total amount for the whole of 2025. Sectors such as artificial intelligence, robotics, quantum technology, low-altitude economy, and advanced manufacturing are attracting massive amounts of capital.
The issue is that the capital flowing into the market today is no longer the same type of capital that entered China when SIG first arrived.
Around 2005, the classic model for US dollar-denominated VC firms was very clear: raise US dollar capital from LPs in the US or across the globe, identify internet startups in China, set up offshore structures, and eventually list the companies in New York or Hong Kong, China. China provided entrepreneurs, engineers, and the market, while the US provided capital and exit channels.
Every link in this chain has become far more complex today.
In 2024, the total VC investment in China reached $40.2 billion, a year-on-year decline of 36.7%. By 2025 and early 2026, technology investment from the US continued to decline, while the RMB-denominated market has become increasingly reliant on state-owned capital, government-guided funds, and industrial capital.
The regulatory landscape has also undergone changes.
The US Department of the Treasury's foreign investment security rules came into effect in January 2025, imposing prohibitions or filing requirements on US entities that invest in certain semiconductor, quantum information, and artificial intelligence projects in China.
The most popular entrepreneurial directions in China right now are precisely AI, chips, robotics, and advanced manufacturing — sectors that also carry the highest compliance costs for US investment institutions.
Furthermore, the cross-border VC structure of the past, where a US headquarters centrally manages the brand, US dollar capital, and global returns, while the China team sources local projects, is being dismantled. HSG, GGV, and other firms have all completed the separation between their old and new brands.
This may well be a microcosm of the next phase of China's US dollar-denominated VC market: large multinational institutions are gradually scaling back their direct operations, while local investors, leveraging the brands, relationships, and track records they have built over the years, are going independent to raise smaller, more flexible, and more diversified funds.
This article is from the WeChat official account "Pencil News" (ID: pencilnews), written by Huang Xiaogui, edited by Zou Wei, and authorized for release by 36Kr.