From TVB to Huayi Brothers, has Li Ruigang pieced together the "Oriental Hollywood"?
Text by / Financial Gossip Girl Author: Novak
Huayi Brothers has finally found its white knight.
Recently, Huayi Brothers announced and confirmed that China Media Capital has officially become the restructuring industrial investor of the company's pre-restructuring case, and the two sides have signed an agreement. If the restructuring goes smoothly subsequently, China Media Capital will acquire approximately 17% of Huayi Brothers' equity for 836 million yuan and become the controlling shareholder, while the "media tycoon" Li Ruigang will become the new actual controller of this former "No.1 film and television stock".
The capital market reacted coldly to this news. On September 17, ST Huayi once plunged 11% during intraday trading, and closed lower in the following days. After all, the acquisition price is only "50% of the original value", which made retail investors feel very upset.
However, for Li Ruigang, the significance is completely different. He already holds two Hong Kong-listed enterprises, TVB Group (the former owner of TVB) and Shaw Brothers, and has also built a complete industrial chain with Noon Sunshine, Oriental DreamWorks, CMC Pictures, and UME Cinemas.
Now that he has taken over Huayi Brothers, Li Ruigang's years-long dream of "Oriental Hollywood" is gradually turning from a concept into reality step by step.
1. Acquiring the No.1 private film and television company stock with 836 million yuan, Li Ruigang becomes the head of the "new Huayi Brothers"
Let's first look at the specific plan of this restructuring.
Huayi Brothers has a total of approximately 2.775 billion shares. According to the restructuring plan, 9 more shares are transferred for every 10 original shares, adding approximately 2.497 billion new shares. After this capital increase, the total number of shares of the company has expanded to 5.272 billion.
Here is the key point. The 2.497 billion newly added shares will not be allocated to the old shareholders at all. The new shares are processed in three parts:
1. China Media Capital will pay 836 million yuan to acquire approximately 896 million shares.
2. Other financial investors will acquire 1.128 billion shares at a price no lower than 65% of the market reference price at the time of signing the agreement.
3. The remaining 473 million shares, worth about 440 million yuan at the same price, will not be sold to investors, but will be directly used to pay off the debts owed in the bankruptcy restructuring.
Since the total number of shares has nearly doubled, the acquisition price is naturally discounted by 50%. As of September 16, the 20 trading days before the signing of the restructuring agreement, the average trading price of ST Huayi was 1.8666 yuan per share, so Li Ruigang took over the shares of Huayi Brothers at the transfer price of 0.9333 yuan per share.
From a paper perspective, the most affected group in this operation is Huayi Brothers' investors, who passively bear the "equity dilution" and the situation that the stock price is also discounted.
Netizens have been discussing this a lot:
"Isn't this bottom-picking by taking advantage of someone's misfortune? We originally thought the share capitalization was giving out bonus shares, but it turned out to be printing shares for outsiders. The share capital has directly doubled, and the shares in our hands have depreciated in disguise."
"I have held the shares for so long, thought there would be a miracle, but ended up waiting for a huge disappointment, and I don't know when I can get my capital back."
Of course, some investors who understand the rules of bankruptcy restructuring put forward different views:
"Having someone take over should be the best outcome for Huayi. After all, if the restructuring fails and leads to delisting, the shares in hand may really be worthless."
"Not distributing the capitalized shares to old shareholders is a conventional operation in A-share bankruptcy restructuring, not unique to Huayi. Now that it has entered the pre-restructuring stage, the primary goal is to save the enterprise."
"Don't just look at the low price of 0.93 yuan. The 836 million yuan from China Media Capital is real cash. This sum of money is used to save the company and solve problems for creditors, not to speculate in the secondary market. We should look to the future."
In any case, if the restructuring is implemented smoothly, China Media Capital will become the controlling shareholder of Huayi Brothers with a shareholding ratio of about 17%, and Li Ruigang will become the new actual controller. After the restructuring, the board of directors will have 9 seats, and China Media Capital can nominate 7 directors to have absolute say.
According to the contract between the two parties, the investment fund of China Media Capital shall be paid in four installments, and all parties will strive to complete the execution of the restructuring plan before December 31, 2026.
Huayi Brothers, the former No.1 private film and television stock, has come to this point, which is really lamentable.
Since 2018, Huayi Brothers has suffered losses for 8 consecutive years. From 2018 to 2025, the company's accumulated attributable net profit loss exceeded 8.5 billion yuan. As of the end of June 2026, the net assets attributable to shareholders of the listed company were -58.5646 million yuan, and the asset-liability ratio rose to 100.28%, which was already in a state of insolvency.
Therefore, in April 2026, the creditor Beijing Ruifeike Company filed an application for restructuring to the court on the grounds that Huayi Brothers was unable to pay off an advertising debt of 11.4 million yuan, and the court subsequently launched the pre-restructuring procedure. Huayi Brothers recruited for half a year before confirming China Media Capital as the restructuring investor.
In 2015, Huayi Brothers' stock price once rose to 32 yuan per share, with a market value exceeding 90 billion yuan. The news of cooperation with China Media Capital was announced on September 16. The next day, ST Huayi plunged 11% during intraday trading. As of the close on September 23, the stock had closed lower for 5 consecutive days, with a market value of only about 4.8 billion yuan, shrinking by more than 90% compared with its peak period.
Here comes the question, why is Huayi Brothers with such poor financial status favored by Li Ruigang?
2. The animated film made a net profit of 700 million yuan, and Huayi was acquired. Is the puzzle of "Oriental Hollywood" complete?
This summer's film schedule saw a dark horse Eight Immortals!. Surrounded by Kung Fu Women's Football and Spider-Man, and without early promotion, Eight Immortals! achieved a box office of 1.95 billion yuan and a Douban score of 8.2, which can be said to have achieved both good box office and public praise.
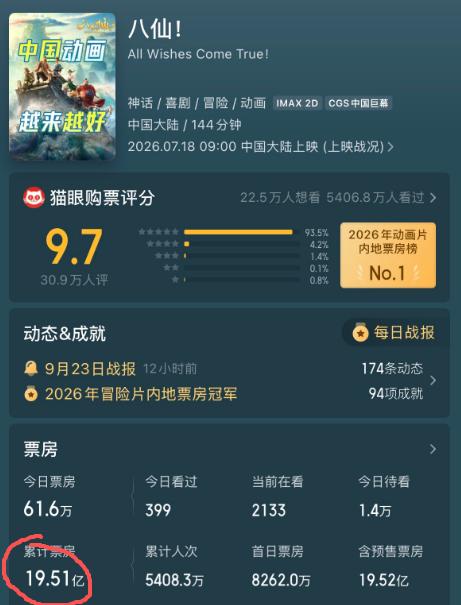
According to the revenue-sharing rules of the film and television industry, the revenue of Eight Immortals! for the producers can reach about 800 million yuan. Excluding the 100 million yuan production cost and distribution and promotion expenses, the net profit is at least 700 million yuan. Don't forget, this is only the box office in cinemas. There will be subsequent revenue from online copyrights, peripheral derivatives, overseas releases and other channels, so the profit will be even higher.
The core producer of Eight Immortals! is Chengdu Huameng Chengzhen Film and Television Media Co., Ltd., also known as "Southwest Headquarters of Oriental DreamWorks". And Oriental DreamWorks was 100% owned by China Media Capital in 2018. So, because of this film, the behind-the-scenes big shot Li Ruigang has made huge profits.
Making money from movies is never Li Ruigang's dream. In the media's description, he has always had a concept of "Oriental Hollywood". With the acquisition of Huayi Brothers, this dream has basically come true.
China Media Capital Group was founded in 2015, with a registered capital of over 6.387 billion yuan. Its business covers film and television content production, media operation, cinema lines, performance, games, IP development and many other sectors. It includes a series of leading companies in the industry such as Hong Kong TVB, Noon Sunshine, Caixin Media, CMC Pictures, Oriental DreamWorks, UME Cinemas, and CMC Live.
From the perspective of the Chinese mainland, Li Ruigang has built a matrix of "film and television content production + distribution + cinema response + media publicity", which has basically formed a closed loop of the entire industrial chain from content production to terminal screening.
Is there anything missing?
What is missing is a listed company in the Chinese mainland to meet the capital market's expectations for them.
China Media Capital has long been eager to go public, but its assets are complexly intertwined, and several attempts for direct IPO have failed.
So Li Ruigang took a smarter path: backdoor listing. At the beginning of 2026, Li Ruigang tried to inject core assets such as Noon Sunshine and CMC Pictures into Hong Kong-listed Shaw Brothers at a consideration of about 4.577 billion yuan, but this "snake swallows elephant" type of transaction encountered many difficulties due to problems such as triggering the mandatory full offer obligation and the difficulty of getting the approval of the cleaning exemption.
In this context, taking control of Huayi Brothers seems very necessary.
After the restructuring, Huayi Brothers will be a "clean shell", and it is also an A-share cultural and entertainment listed enterprise, which fully matches the business of China Media Capital. It can fully incorporate all the content under the group.
Another very important point is that as the former "No.1 private film and television stock", Huayi Brothers' core value also includes the 31-year accumulated film production capacity, distribution license and leading production team, which will be very convenient for making films in the future.
In addition, although Huayi Brothers has suffered losses for years, it holds a number of scarce IP assets that are undervalued by the market. The company has accumulated a library of hundreds of film and television IPs including The Eight Hundred, Youth, A World Without Thieves, the If You Are the One series, the Detective Dee series and so on.
Therefore, Li Ruigang took over the listed company that once had a market value of nearly 90 billion yuan with a cost of only 836 million yuan. At the same time, he solved three strategic problems of "film short board", "IP monetization" and "A-share platform", and thus built the framework of "Oriental Hollywood". This is a strategic investment with extremely low cost.
3. Transforming TVB and taking over Shaw Brothers, Li Ruigang has completed the layout in Hong Kong
Li Ruigang's "Oriental Hollywood" never only focuses on the mainland market. The Hong Kong market is an inseparable and important part of the entire strategy. He has spent several years completing drastic transformations of TVB and Shaw Brothers.
Speaking of TVB, almost all Chinese people are familiar with it. It is the cradle of Hong Kong dramas that has accompanied several generations. In 2015, China Media Capital took shares in TVB and became its largest single shareholder with a 25.02% shareholding. Li Ruigang served as the vice chairman of the board of directors, officially taking control of this old television company.
However, after the acquisition was completed, this deal was gradually viewed negatively. In 2016, TVB's annual revenue was 4.2 billion Hong Kong dollars, and its net profit was 500 million Hong Kong dollars, which was still fairly well-off. But after the mobile Internet wave hit, the crisis broke out rapidly. Young people left the traditional TV screens, short video and long video platforms competed for users' time, while TVB stuck to its traditional TV business and the pace of transformation was slow.
Since 2018, TVB has suffered losses for 7 consecutive years. In 2024, its revenue was only 3.258 billion Hong Kong dollars, with a loss of 491 million Hong Kong dollars. The old giant was struggling.
However, in 2025, the hit drama The Queen of News became a big hit, driving a sharp rise in advertising revenue. Combined with in-depth cooperation with Youku, the mainland copyright and business resources exploded. TVB achieved revenue of 3.192 billion Hong Kong dollars that year, with an attributable net profit of 59.29 million Hong Kong dollars, ending the 7-year-long loss.
But one hit drama can't support the business forever, Li Ruigang still insists on reform.
On July 24 this year, under the leadership of Li Ruigang, the 59-year-old "Television Broadcasts Limited (TVB)" was officially renamed TVB Group Limited, and the stock abbreviation was changed at the same time. This is the first time the company has changed its name since it was listed in 1988.
This name change is not just a simple change of signboard. Li Ruigang has given it a complete set of upgraded capital narratives behind it.
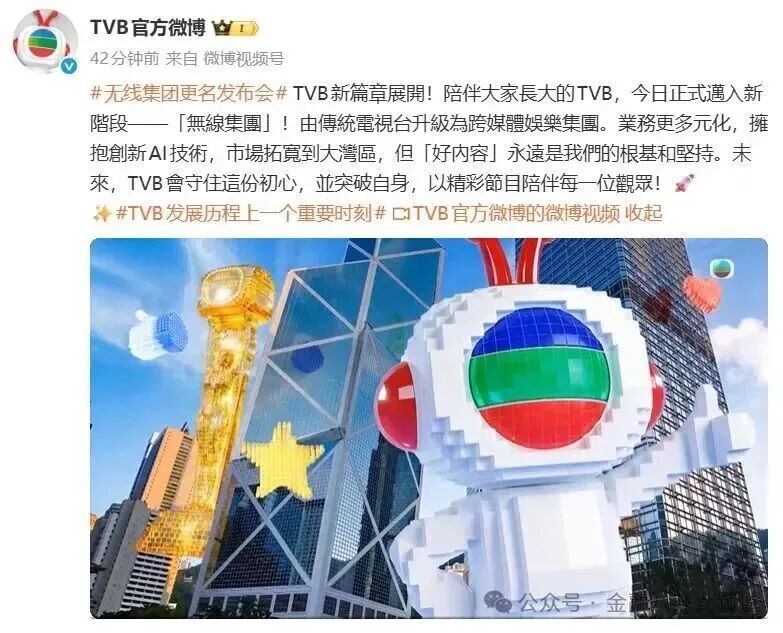
The group tore off the label of traditional TV station, transformed into a comprehensive entertainment IP group, and raised the ceiling of capital market valuation. The company's core assets are no longer TV channels, but the massive Hong Kong drama IP library, artist reserves and content production capabilities accumulated over decades.
At the same time, it embraces AI technology. TVB Group has set up its headquarters in Qianhai, Shenzhen, and reached a strategic cooperation with Volcano Engine. With the help of AI large models, it produces short dramas and short videos in batches, tests AI film and television projects, and makes up for the shortcomings of new media. Moreover, the group's strategic focus has fully shifted to the Guangdong-Hong Kong-Macao Greater Bay Area, targeting the huge consumer market in the mainland.
After the name change, TVB Group is no longer just a local Hong Kong TV station. It has become a comprehensive entertainment group spanning Hong Kong dramas, short video live streaming, e-commerce, and cultural tourism, and has become an important position in Li Ruigang's territory for Hong Kong drama content production, artist incubation, and business expansion in the Greater Bay Area.
In addition to TVB Group, another Hong Kong pawn in Li Ruigang's hand is the old film brand Shaw Brothers.
Shaw Brothers carries the memory of the golden age of old Hong Kong films, and classic martial arts films such as One-Armed Swordsman have influenced a generation. In 2016, Li Ruigang took control of Meike International through acquisition, renamed the company Shaw Brothers, and personally served as the chairman of the board of directors, obtaining this gold-lettered signboard.
In this way, China Media Capital has a solid foundation in the Hong Kong film industry, and has completed the layout of the Hong Kong entertainment industry.
Up to now, Li Ruigang's "Oriental Hollywood" territory is very clear:
Dramas: Noon Sunshine (high-quality mainland dramas) + TV