GPU enterprises are vying to develop robot chips, so why do complete machine manufacturers still want to produce such chips on their own?
Domestic GPU manufacturers are searching for new markets beyond data centers, and the robotics sector is one of the key directions. Recently, Shanghai Anxin Technology Co., Ltd. (hereinafter referred to as "Anxin Technology") has added Zhuhai Biren Integrated Circuit Co., Ltd. as a new shareholder.
In the same period, UBTECH also disclosed that Xixuan Chuangzhi, a joint venture initiated by UBTECH and Muxi Co., Ltd., has completed a 500 million-yuan angel round financing, with its first product targeting end-side computing for robots.
From investing in startups to establishing joint ventures with complete machine manufacturers, GPU manufacturers are approaching the robotics market in various ways. At the same time, robotics enterprises are also getting involved in chip R&D at an earlier stage. The question is, as more and more purchasable products become available, why do they still participate in chip development? What shipment volume is large enough to support such investment?
1. Former Employer Turns into Current Competitor?
Anxin Technology was founded in December 2025, focusing on physical AI scenarios. The company states that it plans to combine its self-developed NPU architecture, end-side inference models and precision motion control technologies, with application scenarios including intelligent manufacturing and autonomous driving.
After this industrial and commercial change, Zhuhai Biren holds approximately 2.81% of the equity of Anxin Technology. TEDA Venture Capital, which once invested in Muxi in its angel round, has also taken shares in Anxin Technology through its underling fund. In addition, Anxin Technology's shareholders also include funds under GL Ventures and iFLYTEK Venture Capital respectively, as well as Yanxin Microelectronics (Suzhou) Co., Ltd.
Sun Erjun, the actual controller of Anxin Technology, holds more than 20% of the shares personally. Before joining Muxi, he worked at the chip business platform under Hisense, Core-A, Vimicro and Montage Technology, and served as product line head and director of product and marketing at Montage.
In September 2020, he co-founded Muxi and served as Vice President of Marketing and Chief Marketing Officer. Muxi focuses on the R&D of general-purpose GPUs and high-performance computing chips. Against the backdrop of surging domestic AI computing power demand, Muxi was listed on the Sci-Tech Innovation Board in December 2025. According to Muxi's prospectus, Sun Erjun left the company in August 2024 and founded Anxin more than a year later.
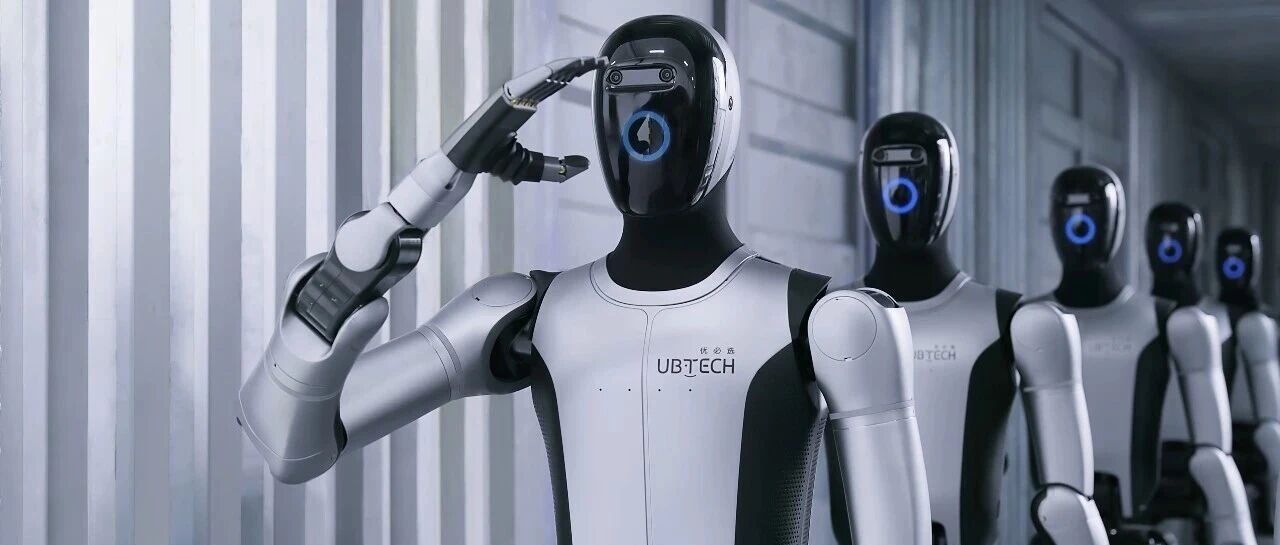
Five months later, Sun Erjun's former employer Muxi entered the same track and became one of the strong competitors in the sector. Xixuan Chuangzhi, co-initiated by Muxi, positions its first self-developed chip as a "brain-cerebellum integrated" SoC for robots, namely a system-on-chip, which benchmarks NVIDIA's Thor chip. It plans to provide a development and verification platform in 2027, and mass-produce the SoC and supporting solutions in 2028. The 500 million-yuan angel round financing announced in November will be used for chip R&D, software toolchain construction and joint customer verification.
Moore Threads and Iluvatar CoreX, two other members of the "Four Little Dragons" of domestic GPUs, have also launched end-side computing power modules for robots. Moore Threads' MTT E300 is equipped with the self-developed "Yangtze" SoC, integrating CPU, GPU and NPU, which can be integrated by complete machine manufacturers for local perception and inference. Iluvatar CoreX has also launched modules such as the Tongyang TY1100, and disclosed its cooperation with Granuo Robot.
For GPU manufacturers, extending from data centers to the robot end-side can reuse part of their accumulated experience in compilers, operator libraries and model optimization. However, robots have different requirements for power consumption, memory, latency and body size, so existing technologies still need to be adapted. In this way, GPU manufacturers can not only provide computing power required for training and simulation for embodied intelligence enterprises, but also sell computing modules and deployment tools to these enterprises.
NVIDIA has already connected the whole workflow. Embodied intelligence enterprises can use the Cosmos world model to generate synthetic training data, tools such as Isaac Sim and Isaac Lab support simulation and robot learning, data center GPUs undertake model training, Jetson is used for robot end-side deployment, and tools such as TensorRT are responsible for inference optimization. For developers, using the same software ecosystem helps reduce migration work; replacing the computing platform usually requires redoing model adaptation, performance tuning and real-machine verification.
The expected growth in robot shipments also gives GPU manufacturers a reason to deploy end-side computing power. According to IDC data in September, the global annual shipment forecast for humanoid robots in 2030 has been raised by about 50% to more than 750,000 units. In the first half of 2026, global humanoid robot shipments were close to 25,000 units, a year-on-year increase of 432.1%. With the growth of shipments, robot bodies are expected to become a new computing power market for GPU manufacturers.
However, the increase in chip products does not mean that each product can perfectly meet the needs of complete machines. For robotics enterprises, purchasing off-the-shelf chips, jointly developing with suppliers, and establishing joint venture chip companies have become different options.
2. Why Do Embodied Intelligence Enterprises Also Increase Investment in Chips?
Cost is one of the reasons why embodied intelligence enterprises increase investment in chips. Zhou Jian, Chairman of UBTECH, once said, "Overseas chips are too expensive, accounting for one third of the cost of hardware procurement materials." Reducing this part of the cost is one of the motivations for UBTECH to jointly develop chips with Muxi. Replacing with domestic chips also brings adaptation costs, and embodied intelligence enterprises need to consider how familiar their teams are with new tools, and how much additional manpower will be invested in migrating algorithms and debugging robots.
For embodied intelligence companies, given that the cost of purchasing chips is not low and there are costs in switching product architectures, participating in R&D to define chips according to product requirements has become a reasonable choice.
Embodied intelligence enterprise Galaxy General signed an agreement with automotive-grade chip manufacturer SemiDrive in November 2025 to jointly develop next-generation robot chips. According to the introduction, Galaxy General will bring the demands of multi-modal models and actual robot applications into chip design, while SemiDrive provides experience in chip R&D, mass production and supply chain.
The cooperation between UBTECH and Muxi also reflects a similar idea. Zhou Jian once stated that he hopes to bring the demands accumulated in robot R&D and applications into chip design at an earlier stage, and verify products through real tasks.
The earlier chips are incorporated into the R&D process, the more room for adjustment before product finalization. Taking Songyan Power and GigaDevice as an example, the two sides started cooperation from the early chip selection of the consumer-grade humanoid robot Bumi, and continued all the way to mass production.
When developing next-generation products, Songyan Power hopes to achieve 21 degrees of freedom in a compact body, and includes GigaDevice's new joint control chip into its evaluation. This chip integrates part of the circuits required to read the motor position and speed, which can reduce peripheral devices on the joint drive board. For the R&D team, the earlier they confirm how small the circuit board can be made, the higher the degree of freedom to adjust the joint structure.
This also explains why the boundary between embodied intelligence enterprises and chip manufacturers is becoming blurred. Embodied intelligence enterprises know best what tasks customers want robots to complete, and they are also responsible for the final operation effect. The earlier they get involved in chip R&D, the more room they have to bring these demands into chip design, and verify whether the chips and robots can meet expectations with real tasks before product finalization.
However, participating in chip R&D also brings a new challenge: is the R&D of self-developed chips worth the investment?
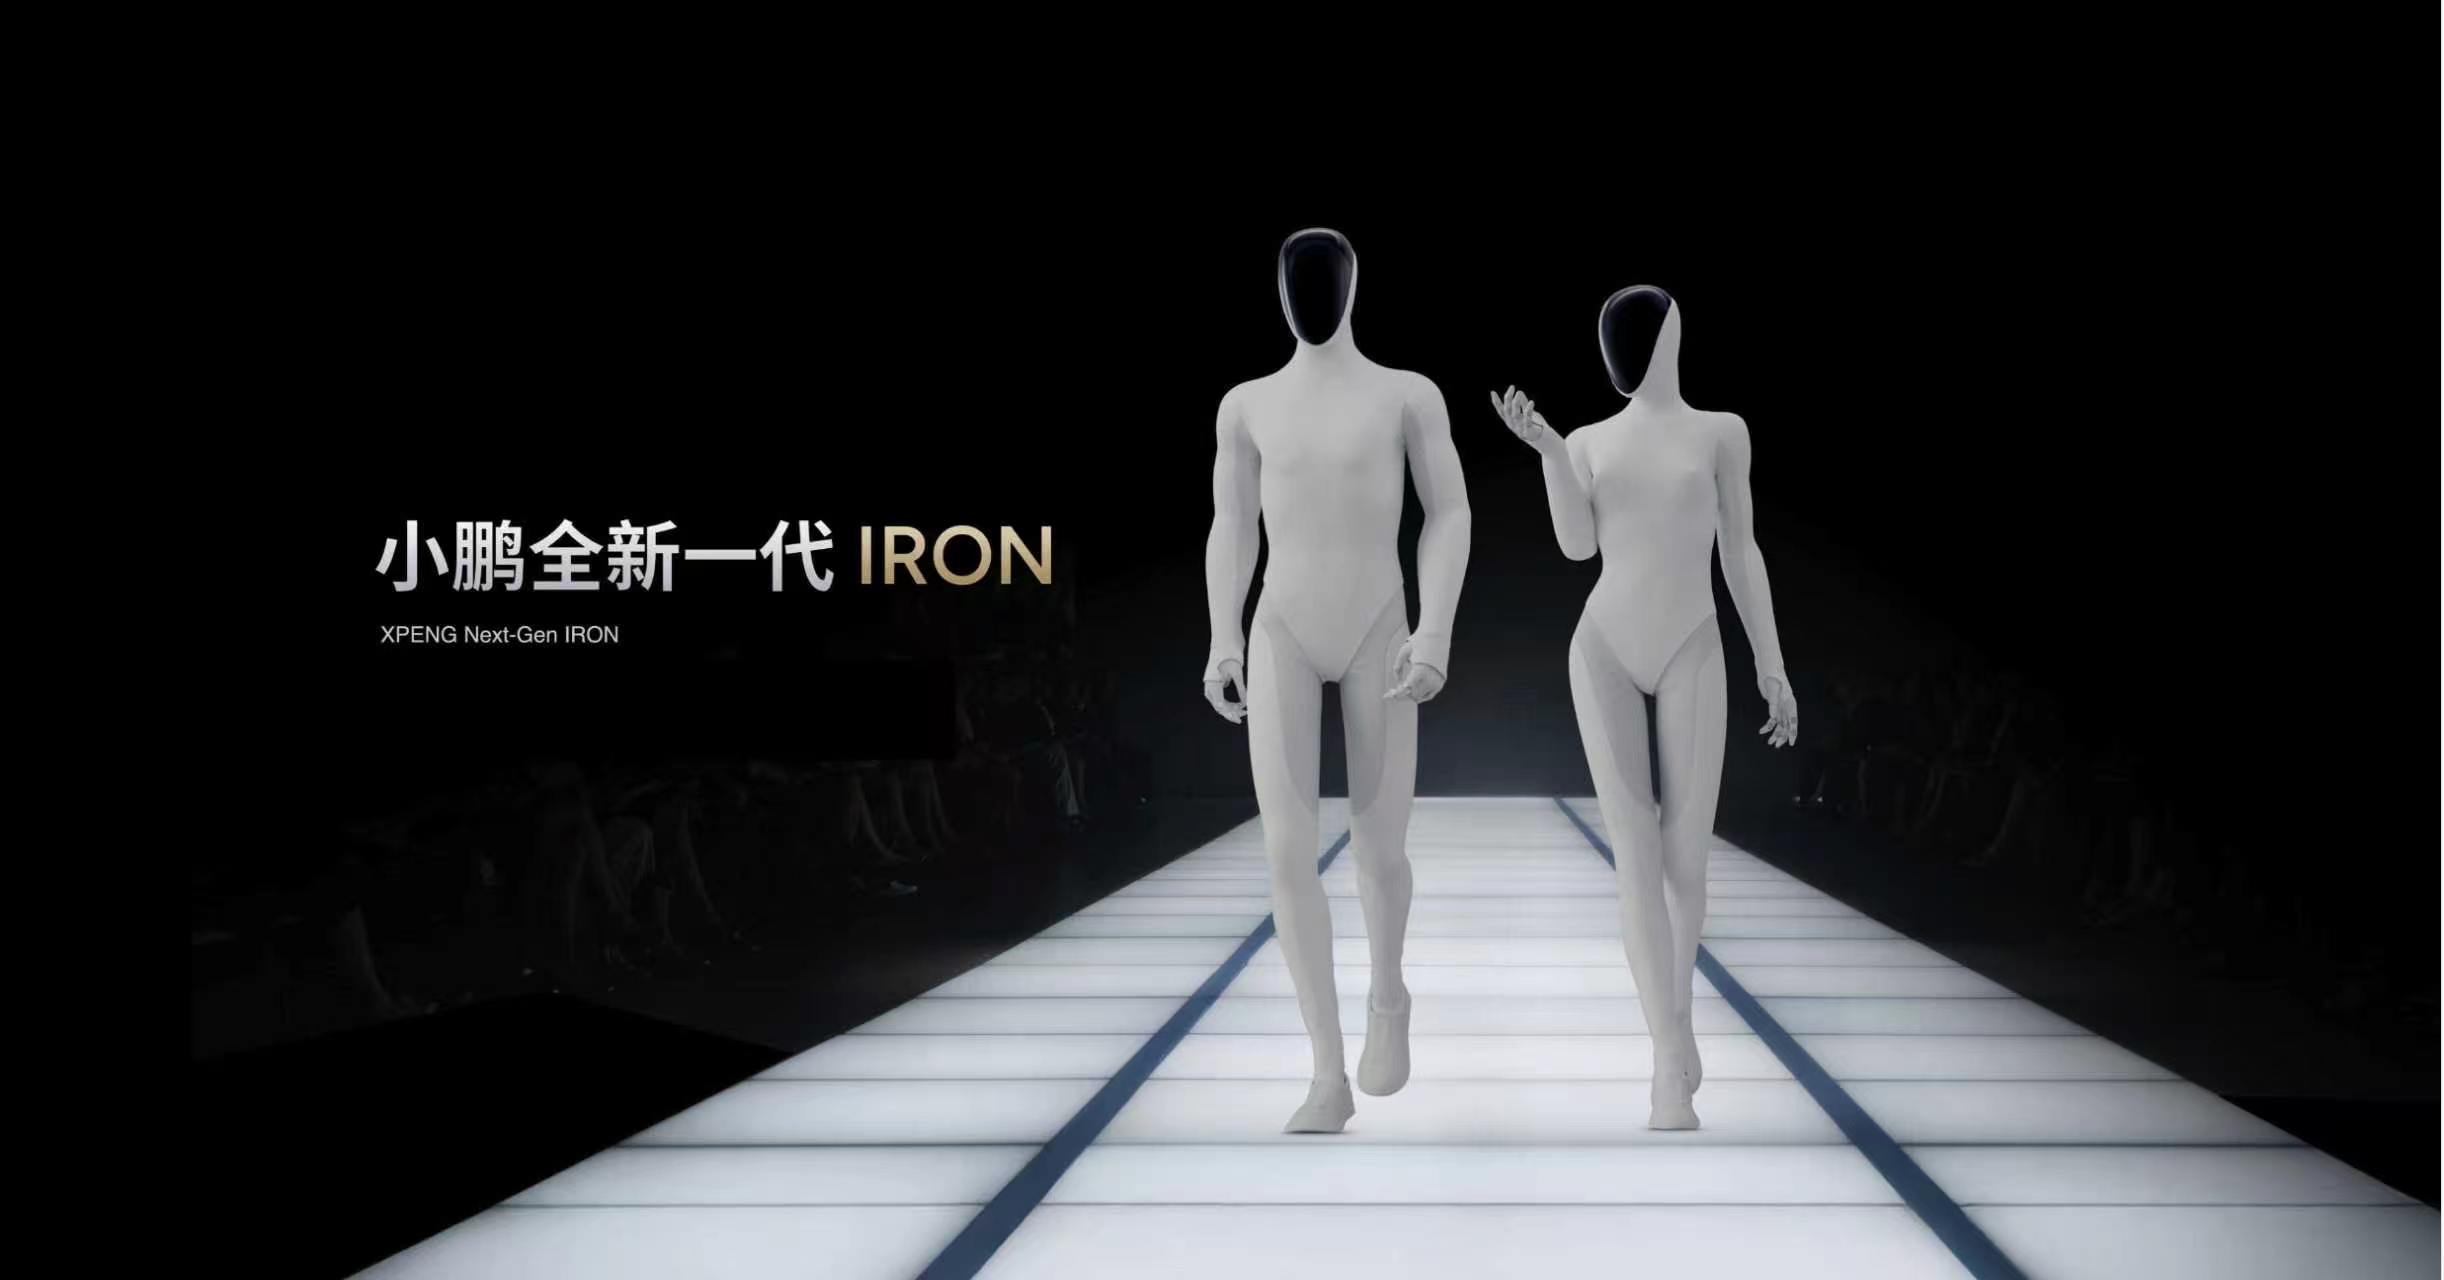
Enterprises that develop both automobiles and robots have the conditions to allocate chip R&D costs to two types of products. Taking XPENG as an example, the Turing chip equipped on IRON robots and XPENG vehicles has the same configuration. The cumulative shipment of Turing chips has exceeded 200,000 units, almost all of which come from the vehicle end, and the R&D investment is mainly allocated by the automotive business. It is reported that the manufacturing cost of a single Turing chip has dropped to 2500 to 3000 yuan.
For embodied intelligence enterprises that mainly rely on robot shipments to share R&D costs, developing chips that meet the needs of complete machines is an engineering problem that can be solved through continuous investment.
The more important question is, can self-development be more cost-effective than purchasing off-the-shelf chips? Only by continuously obtaining orders and expanding delivery scale can enterprises have the opportunity to spread R&D costs over enough robots, so that self-development can have cost advantages. This also puts higher requirements on the commercialization capabilities of enterprises.
This article is from the WeChat Official Account "Fourth Wave", written by Wang Chen and Chen Junyi, and published with authorization from 36Kr.