The Cheng family unveiled a HK$24.9 billion rights issue plan to resolutely defend its control over New World Development.
A substantive progress has finally been made in the capital restructuring around New World Development.
On the evening of November 15, New World Development (00017.HK) announced a rights issue plan, proposing to issue approximately 27.683 billion new shares at a price of HK$0.90 per share on the basis of 11 rights issue shares for every 1 existing share held, with an estimated fundraising of about HK$24.9 billion.
In addition to raising funds, this plan has another implication: Chow Tai Fook Enterprises will remain the single largest shareholder of New World Development, and the Cheng family has not ceded control by introducing capital.
Over the past year, New World Development has been seeking external financial support. According to previous reports, the Cheng family has contacted a number of investment institutions, trying to ease debt pressure by introducing strategic investors. However, some reports pointed out that some potential investment plans involve large-scale equity investment, and investors have different considerations for the company's control arrangements.
Now, Chow Tai Fook Enterprises has chosen to step in directly, not only committing to subscribe for all its entitled rights issue shares, but also participating in additional underwriting. This means that the Cheng family has finally used real money to retain control of New World Development.
From this perspective, this rights issue plan can also be regarded as a phased victory in the Cheng family's battle to defend control. However, for New World Development, which still has a huge debt scale, fundraising is only the first step. How to use this to rebuild financial stability remains a greater test.
At least for now, the capital market reaction is not optimistic. On November 16, New World Development resumed trading, and its share price once fell by more than 45% during the session.
HK$24.9 Billion Rights Issue: Chow Tai Fook Enterprises Puts Up Real Money
The most notable part of this rights issue plan is the extremely high fundraising ratio and the heavily discounted subscription price.
According to the announcement, New World Development plans to conduct the rights issue on the basis of 11 rights issue shares for every 1 existing share held, with a subscription price of HK$0.90 per share and an estimated issuance of about 27.683 billion new shares.
As of the date of the announcement, New World Development has approximately 2.517 billion issued shares. After the completion of the rights issue, the total number of issued shares of the company will expand to approximately 30.1996 billion shares, equivalent to about 12 times of the original share capital.
In terms of price, the subscription price of HK$0.90 per share represents a discount of about 81.5% compared with the closing price of HK$4.87 on the last trading day before the suspension (November 12), and a discount of about 26.9% compared with the theoretical ex-rights price of HK$1.23.
This means that existing shareholders who do not participate in the rights issue will face considerable equity dilution pressure. Calculated according to the announcement, if shareholders do not participate in the rights issue, the theoretical dilution effect will be about 75.3%.
It is worth noting that this rights issue adopts a full underwriting arrangement, and the underwriters include the controlling shareholder Chow Tai Fook Enterprises, HSBC and DBS Bank.
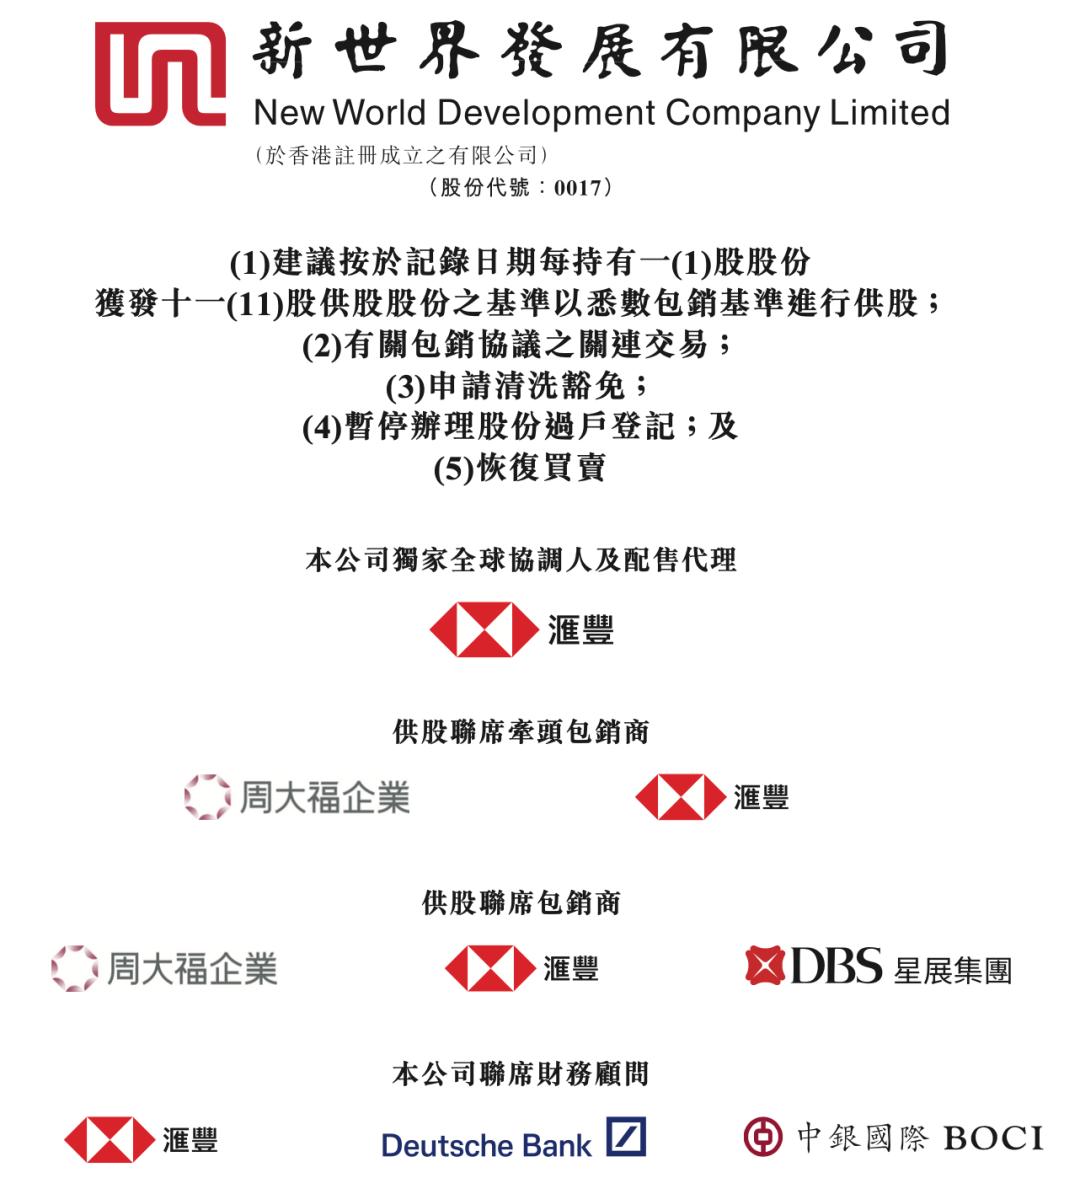
The New World Development rights issue plan was released on the evening of November 15
At present, Chow Tai Fook Enterprises and related members of the controlling shareholder group hold about 1.141 billion shares of New World Development, accounting for about 45.33% of the issued share capital. According to the irrevocable undertaking, Chow Tai Fook Enterprises will fully subscribe for the approximately 12.548 billion rights issue shares tentatively allotted to it, with a corresponding subscription amount of about HK$112.93 billion.
In addition, Chow Tai Fook Enterprises will also assume additional underwriting responsibilities, underwriting up to about 8.214 billion rights issue shares, accounting for about 29.67% of the total number of rights issue shares this time. Calculated based on the maximum underwriting quota, the total capital involved in its subscription and underwriting is about HK$186.8 billion.
Compared with the previous search for capital injection from external investors, Chow Tai Fook Enterprises now chooses a more direct way to provide financial support to New World Development.
According to the announcement, if all eligible shareholders participate in the rights issue proportionally, the shareholding ratio of original shareholders will remain basically unchanged, and Chow Tai Fook Enterprises will still hold about 45.33% of the equity.
However, if all eligible shareholders other than the controlling shareholder do not subscribe for the rights issue shares, and the unsubscribed shares are not allocated to independent investors through placement, the shareholding ratio of Chow Tai Fook Enterprises and its concerted parties may rise to about 72.55%.
This also means that the rights issue can not only supplement capital for New World Development, but also may further increase the Cheng family's shareholding ratio.
The announcement also revealed that the controlling shareholder is still in discussions with potential investors regarding a possible investment in New World Development. The company stated that even if the relevant investment is finally implemented, the shareholding ratio of Chow Tai Fook Enterprises and its concerted parties will still be higher than 30%, and Chow Tai Fook Enterprises will remain the single largest shareholder of New World Development.
In terms of the use of funds, the estimated net proceeds from the rights issue are about HK$24.1 billion. New World Development plans to use about 34% (about HK$8.2 billion) to prepay 10% of the outstanding principal amount under the target financing; about 36% (about HK$8.7 billion) for debt repayment, including senior notes, bank loans and interest payments, and deferred distributions on perpetual securities; about 30% (about HK$7.2 billion) will be used for the group's development project reserve.
Progressing in parallel with the rights issue is a bank loan extension arrangement with a scale of about HK$82 billion.
According to the announcement, New World Development has started negotiations with lenders on relevant overseas bank loans. These loans were originally due from March 2027 to December 2029. After the successful completion of the rights issue, the company will prepay 10% of the principal, and the final maturity date of the remaining 90% of the debt, which is about HK$73.8 billion, will be extended by two years on the original basis.
New World Development Still Needs Time to Recover
The Cheng family is willing to provide funds to support New World Development, behind which is the reality that the company has not yet got out of financial difficulties.
The annual report of New World Development for the 2026 fiscal year (July 1, 2025 to June 30, 2026) shows that during the period, the company achieved revenue of HK$19.992 billion, a year-on-year decrease of 28%; core operating profit was HK$7.702 billion, a year-on-year increase of 28%; but affected by non-cash impairment losses and provisions related to the 11 SKIES project, the company recorded a loss of HK$26.818 billion for the whole year.
If non-cash impairment losses, provisions and other losses are excluded, New World Development's recurring operating net profit is HK$2.228 billion — this is "the first time to turn losses into profits in the past few fiscal years", New World Development pointed out in the financial report.
Debt pressure is a more difficult problem for New World Development to avoid. As of the end of the fiscal year, New World Development's total debt was about HK$143.3 billion, a decrease of about HK$2.7 billion compared with the previous fiscal year; net debt was about HK$126.3 billion, an increase of about HK$6.2 billion instead.
In the same period, the company's available funds were about HK$33 billion, including cash and bank balances of about HK$17 billion, and available bank loans of about HK$16 billion. Although the total financing cost decreased by 15% year-on-year to HK$6.3 billion, the huge debt scale still means that New World Development needs to bear high financing expenses.
Previously, New World Development has alleviated capital pressure through asset sales and debt replacement. This rights issue and loan extension is an important step for it to further adjust its capital structure.
From a business perspective, New World Development still has realizable assets and project reserves. In the 2026 fiscal year, the company's attributable contracted sales from property development projects and asset sales were about HK$29.6 billion, of which the Hong Kong market contributed about HK$22.1 billion, and the Chinese mainland market contributed about RMB 6.8 billion.
Hong Kong is still an important source of income for New World Development. Projects such as The Pavilia Farm III, Upper River, Villa Monticello, The Pavilia Farm III and The Green Atrium have contributed a lot of sales to the company. On the mainland, the company continues to concentrate resources on core cities in the Greater Bay Area and the Yangtze River Delta.
In addition to residential development, New World Development's K11 commercial projects are also its important assets. In the 2026 fiscal year, the company's Hong Kong property investment income was about HK$3.424 billion, and the mainland property investment income was about HK$1.915 billion. The value of this part of the business lies in its ability to continuously generate cash flow through rent and commercial operation.
New World Development revealed that the company has identified a potential sale list, focusing on selling mature assets with limited further appreciation space. While selling assets, New World Development is also working hard to "generate its own blood", among which the Northern Metropolis is regarded as an important development opportunity.
As of June 30, 2026, the company's agricultural land reserve held in the New Territories of Hong Kong involves an attributable total floor area of about 10.6 million square feet at different stages of land use conversion. With the advancement of the construction of the Northern Metropolis, this part of the land reserve is expected to become an important resource for the company's medium and long-term development.
However, the transformation from land reserve to actual sales revenue still needs to go through multiple links such as land use conversion, land premium payment, project development and sales, and it cannot realize cash return in the short term.
New World Development has set a clearer financial target in the rights issue announcement: by the end of 2031, the total proceeds from property development contracted sales and asset sales will reach HK$150 billion to HK$200 billion, and total debt will be reduced by about HK$40 billion to HK$50 billion.
Whether these goals can be achieved depends largely on the recovery degree of the real estate market in Hong Kong and the mainland, as well as on whether the company can sell assets at the expected price, promote the transformation of land reserves, and continuously obtain financing support from banks and the capital market.
For the Cheng family, this rights issue has solved at least two immediate problems: first, it has supplemented considerable equity capital for New World Development, and second, it has retained the family's control over the company in the process of introducing capital.
But for New World Development, the real test has just begun.
This article is from the WeChat Official Account "Times Finance APP" (ID: tf-app), written by Liang Zhengyu, and authorized for release by 36Kr.