The three musketeers of the medical aesthetics industry are under performance pressure.
Tonight, Bloomage Biotech (688363.SH), one of the "Three Musketeers of Medical Aesthetics", released its Q3 performance report, overall, its performance is still under pressure.
Specifically, Bloomage Biotech recorded revenue of RMB 2.596 billion in the first three quarters, down 17.94% year on year; its attributable net profit was RMB 186 million, down 26.27% year on year; its non-recurring profit and loss deducted attributable net profit was RMB 160 million, down 13.47% year on year. Meanwhile, its total profit also decreased by 34.98%.
In terms of cash flow, the net cash flow generated from operating activities of Bloomage Biotech in the first three quarters was RMB 579 million, up 87.65% year on year. In this regard, Bloomage Biotech stated that this is mainly due to the continuous optimization of the company's business structure and resource allocation, the reduction of expense expenditures, and the year-on-year decrease in cash paid for purchasing goods on the procurement side, so the quality of operating cash flow has been significantly improved.
Looking at a single quarter separately, Bloomage Biotech realized revenue of RMB 840 million in the third quarter, down 6.96% year on year and 9.39% quarter on quarter. Its attributable net profit reached RMB 33.301 million, up 5.62% year on year, but dropped sharply by 62.22% quarter on quarter, its non-recurring profit and loss deducted attributable net profit was RMB 30.993 million, surging 165.00% year on year, but decreased by 56.92% quarter on quarter.
In response to the decline in total profit in the first three quarters, Bloomage Biotech explained that it is mainly due to the year-on-year decrease in revenue from the innovation transformation business of dermatological science. The substantial year-on-year growth of non-recurring profit and loss deducted net profit in a single quarter benefits from the continuous optimization of business structure and strict control of expenses.
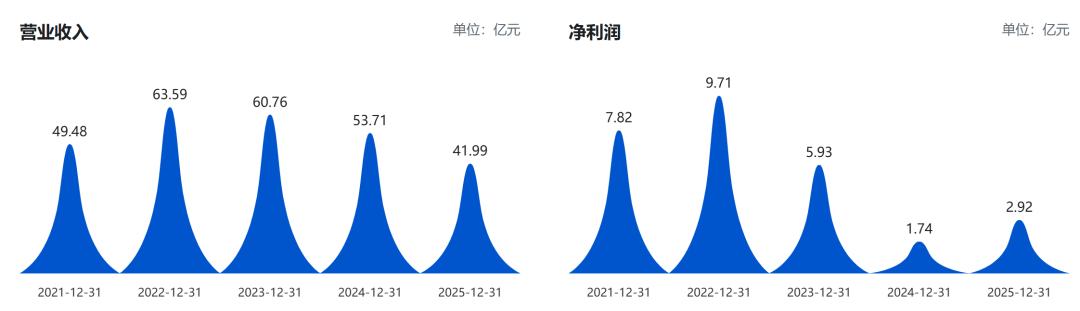
If we extend the time dimension, in recent years, the performance of Bloomage Biotech has been in an adjustment cycle. From 2021 to 2025, its revenue was RMB 4.948 billion, RMB 6.359 billion, RMB 6.076 billion, RMB 5.371 billion and RMB 4.199 billion respectively, and the corresponding attributable net profit in the same period was RMB 782 million, RMB 971 million, RMB 593 million, RMB 174 million and RMB 292 million respectively.
01
At present, as a giant in hyaluronic acid raw materials, Bloomage Biotech positions itself as a synthetic biology-driven biotechnology enterprise, with its business landscape covering four major sectors: raw materials, pharmaceuticals and medical aesthetics, dermatological science, and nutritional science. Its sub-brands include products such as Biohyalux, QuadHA, MedRepair, Hyaestem, Hyadiff and Bloomage Dangkang.
At this stage, the raw material business, pharmaceuticals and medical aesthetics business constitute the two major performance pillars of Bloomage Biotech. The former refers to bioactive product series with hyaluronic acid as the core; the latter focuses on independent R&D and production of hyaluronic acid biomedical material medical terminal products, which are divided into two major sectors: medical aesthetics and pharmaceuticals.
In the first half of this year, the above two businesses achieved revenue of RMB 638 million and RMB 599 million respectively, accounting for 36.38% and 34.15% of the company's main business revenue. Bloomage Biotech stated in its semi-annual report that the two major sectors have generally maintained a steady growth momentum, especially the raw materials have gradually entered the stage of commercial volume expansion, which effectively offsets the impact of the price decline of traditional products.
In addition, although the overall performance volume of the nutritional science innovation transformation business is still small, it has maintained a good growth momentum, achieving revenue of RMB 61 million in the first half of this year, up 59.71% year on year.
In contrast, the dermatological science innovation transformation business presents a completely different picture. The revenue of this sector fell by 42.11% year on year last year, and the gross profit margin also dropped by 5.19 percentage points in the same period. The downward trend continued in the first half of this year, with the year-on-year decline in revenue further expanding to 50.9%, becoming the main sector dragging down Bloomage Biotech's performance.
The products of this sector are more consumer-oriented, covering categories such as one-shot essence, cream, lotion and toner, facial mask, hand mask, eye mask, essential oil, eye cream, etc. It once carried Bloomage Biotech's growth expectations, but judging from the current performance, the performance of this sector has not met the company's expectations.
It is worth mentioning that this month, Guo Xueping, former vice general manager and chief scientist of Bloomage Biotech Group, passed away due to illness at the age of 61.
In the industry, Guo Xueping is recognized as the founder of hyaluronic acid industrialization, who has been deeply engaged in this field for nearly 40 years and presided over a number of national key research projects. It is relying on the fermentation method and enzyme digestion technology led by him for R&D that hyaluronic acid can achieve large-scale, low-cost mass production, which also makes Bloomage Biotech stand at the leading position in the hyaluronic acid raw material industry.
In addition, in September this year, Bloomage Biotech announced that its core technical personnel Zhou Wei had left the company, and at the same time newly recognized two doctors, Wang Hao and Wang Enxu, as core technical personnel.
With the passing of the technical founder and the adjustment of the R&D team, Bloomage Biotech may also face the test of the succession of core R&D forces and the new development cycle.
02
In addition to Bloomage Biotech, Shanghai Haohai Biological Technology Co., Ltd. (688366.SH), another company labeled as one of the "Three Musketeers of Medical Aesthetics", also released its Q3 report, with equally dismal performance.
Statistics show that in the first three quarters of 2026, Haohai Biological Technology achieved operating revenue of RMB 1.71 billion, down 9.93% year on year; its attributable net profit was RMB 163 million, down 46.53% year on year; its non-recurring profit and loss deducted attributable net profit was RMB 116 million, with the decline further expanding to 54.38%. By quarter, the company's total profit in the third quarter decreased by 49.87% year on year, and its attributable net profit decreased by 46.28% year on year, with no obvious sign of narrowing.
Haohai Biological Technology stated that multiple factors have jointly suppressed its performance, including insufficient demand for medical aesthetic consumption, white-hot price competition in hyaluronic acid products, and the end of the exclusive distribution business of Hoya Optical OK lenses. At the same time, the new Songjiang base has been transferred to fixed assets, and the newly added depreciation and amortization has also increased costs.
Aimeike, known as "Kweichow Moutai for Women" in the market, is also in a downward performance channel.
Aimeike achieved revenue of RMB 1.744 billion in the first three quarters, down 6.48% year on year; its attributable net profit was RMB 791 million, and its non-recurring profit and loss deducted attributable net profit was RMB 702 million, down 27.64% and 26.35% respectively year on year. Intensified competition has increased operating pressure, coupled with a 47.57% year-on-year surge in sales expenses and shrinking investment income, which jointly led to weak performance.
This article is from the WeChat official account "Sci-Tech Innovation Board Daily", author: Shi Shiyun, authorized for release by 36Kr.