Coursera: Focus on the "things you can control"
AI raises the barrier to learning, but will not eliminate the demand for learning.
On October 28, US online education company Coursera (NYSE:COUR) released its financial report for the third quarter of 2026. This is the first full quarter after the company completed its merger with Udemy. Both revenue and adjusted EBITDA exceeded market expectations, but the guidance for the next quarter fell short of expectations, leading to a drop in stock price after hours.
Coursera's revenue in the third quarter of 2026 was 376.7 million US dollars, a year-on-year increase of 94%, exceeding market expectations by 2.2%. The substantial revenue growth mainly came from the performance of Udemy, which was incorporated on May 11, 2026; excluding the impact of mergers and acquisitions, the revenue under the organic caliber actually decreased by about 3% year-on-year.
GAAP net loss was 25.6 million US dollars, a significant expansion from the 8.6 million US dollar loss in the same period of the previous year; GAAP loss per share was 0.10 US dollars, compared with 0.05 US dollars in the same period of the previous year. Adjusted earnings per share was 0.21 US dollars, exceeding market expectations by 16.9%.
After the financial report was released, Coursera's stock price fell by about 8% to 4.27 US dollars in after-hours trading. The core of market concern is that although the merger has brought significant revenue growth and margin improvement, the endogenous growth momentum (especially the consumer business) is still weak, and the short-term guidance fails to show sufficient signs of recovery.
Coursera CEO Greg Hart emphasized on the conference call that the merger and integration is progressing faster than originally planned, and it is expected to achieve annualized total cost savings of more than 150 million US dollars by the end of the year, far exceeding the original target of achieving 115 million US dollars in net synergies within 24 months. At the product level, the company revealed the progress of its AI-native adaptive skills platform, which is planned to be widely opened to enterprise customers in the first half of 2027.
In addition, the operating indicators disclosed in the financial report show that the registration rate of generative AI-related courses has increased from 25 times per minute in 2025 to more than 40 times per minute in 2026, and the registration volume of critical thinking courses has increased by more than 100% year-on-year.
01 Coexistence of Financial Improvement and Revenue Pressure
Coursera's Q3 revenue was 377 million US dollars, adjusted EBITDA was nearly 62 million US dollars, with a profit margin of about 16%, expanding by more than 800 basis points year-on-year, doubling.
However, standardized revenue decreased by about 3% year-on-year, and the consumer business was particularly weak.
Greg Hart mentioned at the beginning: "We are strengthening our financial position as promised. The reported adjusted EBITDA margin expanded by more than 800 basis points year-on-year, doubling to about 16%. At the same time, our revenue trajectory, especially in the consumer business, is still below our growth target. We continue to focus on the things we can control, and that starts with integration. Since May, we have streamlined the combined organization, integrated our go-to-market teams, and aligned around a unified product vision and roadmap."
The management clearly focuses on "things that can be controlled" — integration and cost. Greg Hart said: "Integration is the foundation, not the end point. Its purpose is to create operational discipline, focus, and investment capabilities to build the next step. Improving our growth trajectory requires disciplined execution and products that can create significantly more value for customers."
On May 11 this year, the merger between Coursera and Udemy was officially closed. At present, the company is advancing the post-merger ecosystem to achieve annualized total cost savings of over 150 million US dollars by the end of the year, supporting the annualized net synergy target of 115 million US dollars, and the merger process has also been greatly advanced.
Integration actions include: streamlining the merged organization, eliminating overlapping functions and redundancies, integrating go-to-market teams in July, and unifying global customer coverage.
This is the most solid execution result of this quarter. Greg Hart said: "We now expect to achieve annualized total cost savings of more than 150 million US dollars by the end of the year. These savings support the transaction's annualized net synergy target of 115 million US dollars, and we are on track to achieve this target only eight months after the transaction is completed, compared with the original plan of 24 months."
02 Core Strategy: AI-native Skills Platform Project Helix
Greg Hart positions Project Helix as the "number one priority". He said: "Absolutely, Project Helix is the future of the business, and the future of both platforms."
Greg Hart introduced the product logic of Project Helix, including the following functions:
First, Skills Intelligence: Translate business goals expressed in natural language into required skills and development paths;
Second, Personalized Applied Learning: Continuously adapt to learners' roles, goals, progress and organizational context, and integrate learning into the workflow;
Third, Proof: Scored assessments, hands-on practices, and recognized certificates to provide evidence of "what one can do".
"The goal of Project Helix is to prove what a person can do, not just what they have completed." said Greg Hart.
In his view, connecting credible learning, relevant context and credible proof at enterprise scale will be the differentiation of Helix.
In September this year, after the merger of Coursera and Udemy, the company held its annual flagship customer conference FWD Virtual, which was initially mainly in the form of online virtual events, and later extended to hold regional sessions in various places. Project Helix was first previewed to customers at the conference.
The next step will be promoted in phases, co-creating with selected design partners. The goal is to achieve wide enterprise availability in the first half of 2027, followed by consumers.
The company explicitly does not assume substantial revenue contribution from Helix in 2027: "We will not assume Helix-driven growth contributions before there is evidence to support it."
03 Demand-side Logic: AI Raises the Barrier to Learning, But Will Not Eliminate Learning Demand
In Greg Hart's view, AI raises the threshold of learning, rather than eliminating the demand for learning — it makes "getting answers" cheap, but makes "building verifiable capabilities" scarce.
He used two sets of data to construct the argument:
(1) The Gap Between Investment and Talent Readiness, "Goldman Sachs estimates that global AI-related investment will reach about 1 trillion US dollars in 2026... Deloitte found that 43% of business leaders said their organizations are well-prepared in AI technology infrastructure, while only 20% hold the same view on talent, a gap of more than two to one."
(2) Empirical Evidence That Chatbots Harm Learning, "Using a general chat interface improved performance on practice exercises by 48%. But when taking exams without AI, these students performed 17% worse than the control group. The encouraging news is that tutors designed with learning safeguards have largely mitigated this negative impact."
From this he drew the core conclusion: "If the value of online learning is only to access information, AI makes this value easier to replicate. The lasting value lies in credible expertise, effective practice and feedback, and credible proof that people can get the work done."
At the same time, he also cited the 2026 *Global Skills Report* (8th edition, based for the first time on the combined ecosystem data of Coursera + Udemy) and pointed out that quantifiable structural changes are taking place in learners' behavior: learners are not choosing between technical AI skills and human skills, they are building both at the same time.
This is reflected in:
First, GenAI learning demand continues to accelerate. "On our platform, the enrollment rate for GenAI courses has increased from 25 times per minute in 2025 to more than 40 times per minute in 2026."
The registration rate has increased by about 60% within a year, reflecting that the demand for AI skills is still spreading rapidly.
Second, Human Skills Are Heating Up Simultaneously. At the same time, the number of enrollments in critical thinking courses has increased by more than 100% year-on-year. The growth rate is even higher than that of GenAI course enrollments, indicating that learners have not abandoned "soft skills" due to the rise of AI.
In Greg Hart's view, The more powerful AI is, the more "fluency in using AI" and human judgment that can "judge AI output, define problems, and drive change" are needed.
Against this backdrop, Coursera's partner ecosystem continues to expand, with new partners including Harvard Business School Online (leadership and business strategy courses), GitHub (agentic AI and modern software development related courses), covering both "technical AI" and "human skills" segments.
04 Ecosystem: 310 Million Learners, Nearly 12,000 Enterprise Customers, Dual-Instructor System
The merged ecosystem has covered more than 310 million learners, serving over 1.6 million paid subscribers and nearly 12,000 enterprise customers.
But the real moat is not these total numbers, but two complementary instructor systems: Udemy brings a global community of nearly 100,000 instructors, whose value lies in "response speed" — when tools, roles and skills change rapidly, practitioners can quickly turn the latest practices into courses; Coursera, on the other hand, relies on deep relationships with more than 425 universities, leading enterprises and professional institutions to provide credible teaching and recognized certificates.
In Greg's words, after the merger, the two together form a "broader, more responsive foundation". Udemy solves the "speed" problem, Coursera solves the "credibility" problem, and what Helix does is to orchestrate the two around the same learning goal.
The ecosystem expansion in Q3 is evidence that this complementary structure has begun to produce chemical reactions. At the FWD conference, the company announced 16 new university and industry partners and 25 new professional certificates at one go, deliberately spanning a wide range of fields: Harvard Business School Online complements leadership and business strategy, GitHub complements agentic AI and modern software development, and the American Medical Association and Taipei Medical University extend to healthcare and life sciences...
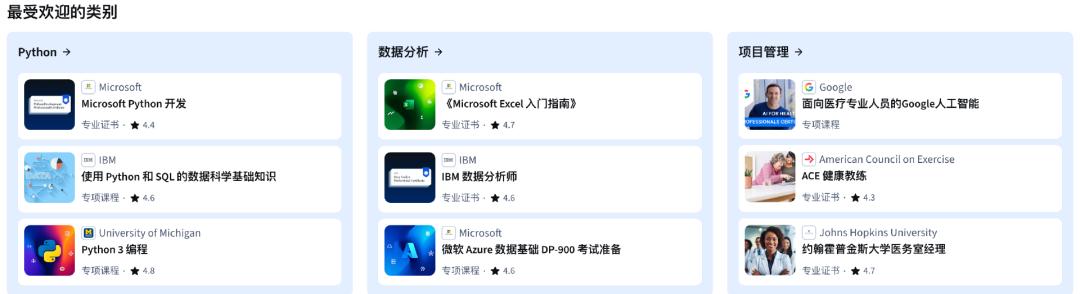
Not betting on a single track is essentially accumulating cross-industry authoritative supply for Helix's skill map.
Anthropic almost doubled its Coursera catalog this quarter, adding 10 new courses and planning monthly updates, turning the "course catalog" into a dynamic asset that updates rollingly as AI evolves.
Two "cross-platform experiments" are even more intriguing. For example, Dr. Ryan Ahmed, a Udemy instructor, adapted a series of Claude courses into Coursera specializations, which became one of the most successful new releases in 2026...
This is also what Helix is doing, that is, leveraging expertise across platforms to integrate content from different experts around the needs of learners.
The supply side itself is also participating in the design. At the first partner and instructor forum in Madrid, more than 80 leaders from universities, industries and the instructor community directly collaborated with the team on the future of AI-native learning, and several have joined the design work.
The logic behind this is that if Helix wants to turn expert knowledge into adaptive learning, practice, assessment and proof, knowledge providers must be involved from the very beginning.
Putting it all together, what the management wants to express is a "compound interest" structure: credible institutional expertise, the responsiveness of practitioners, broad distribution capabilities, plus Helix's increasingly intelligent orchestration capabilities — the combination of the four will make the ecosystem more valuable to every participant over time.
05 Financial Details and Outlook
Key Q3 Figures
Revenue for the quarter was 377 million US dollars, up 94% year-on-year on a reported basis; gross profit was 240 million US dollars, with a gross margin of 64%;
Operating expenses were 186 million US dollars, accounting for 49% of revenue, down 120 basis points year-on-year, reflecting improved sales and marketing efficiency and reduced corporate functional redundancies; net profit was 57 million US dollars, accounting for 15.2% of revenue;
Adjusted EBITDA was nearly 62 million US dollars, with a profit margin of 16.3%, expanding by more than 800 basis points year-on-year, doubling.
It should be noted in particular that the 2026 adjusted EBITDA includes approximately 10 million US dollars of purchase accounting gains per quarter, which will diminish in the coming years. Therefore, the current profit margin has a certain "inflated" component, which will create headwinds when comparing in 2027.
Cash Flow and Balance Sheet
Operating cash flow was 15.5 million US dollars, down 54% year-on-year.
Free cash flow was 4.6 million US dollars, turning positive from -326 million US dollars in the previous quarter, but down 83% year-on-year, mainly affected by merger-related costs.
The company repurchased approximately 18.1 million shares this quarter, spending 102 million US dollars.
Performance by Segment
Enterprise business revenue was 200.9 million US dollars, up 214% year-on-year, making it the fastest growing segment, benefiting from the integration of Udemy's enterprise business and the resilience of multi-year contracts.
Consumer business revenue was 175.8 million US dollars, up 35% year-on-year. Subscription revenue maintained growth, but one-time purchases and transactional products were under pressure, and leading funnel indicators weakened.
Paid subscribers reached 1.687 million, up 30% year-on-year.
Q4 Guidance
The company expects Q4 revenue of 358–366 million US dollars, adjusted EBITDA of 55–59 million US dollars, corresponding to a 16% profit margin, exactly meeting the Q4 target set in June. At the segment level, enterprise growth is expected to be roughly flat, while consumer growth will decelerate further due to weakening leading funnel indicators.
Full Year 2026 Guidance
The full-year revenue guidance is narrowed within the original range to 1.229–1.237 billion US dollars, which is equivalent to 1.503–1.511 billion US dollars on a standardized basis; the full-year adjusted EBITDA margin maintains the target of about 14% (raised last quarter). It should be noted that this reported basis profit margin is higher than the standardized