While the stock prices of humanoid robot concept stocks are skyrocketing, Unitree has first poured a cold shower on the entire industry.
On October 19, the share price of Unitree Robotics surged by 16.15%; on October 20, it rose another 6.07% to close at 526.03 yuan, with the total market value returning above 210 billion yuan. In just a few trading days, market sentiment has warmed up rapidly.
Meanwhile, the company has explicitly stated that its operation is normal, and there is no major information that should be disclosed but has not been disclosed.
On one side is the capital market's enthusiasm for humanoid robots, and on the other side is the company's prudent reminder for the commercialization progress. The two attitudes are not contradictory, but reveal the most noteworthy topic in this industry at the moment: robots are already capable of performing increasingly complex movements, how far are they from becoming a large-scale profitable business?
The risk warning from Unitree Robotics is worthy of careful review by the entire industry.
01
What Exactly Is the Market Betting On?
The share price trend of Unitree Robotics has gone through a drastic shift in expectations.
On August 19, 2026, Unitree Robotics was listed on the Sci-Tech Innovation Board with an issue price of 150.80 yuan per share, and its share price once rushed to 1100 yuan on the first day of listing. After that, the share price continued to fall, and the lowest intraday price hit 404.03 yuan on October 15. By October 19, the share price suddenly surged by 16.15%, and continued to rise on October 20, returning to a market value of over 210 billion yuan.
From the high point of 1100 yuan on the first day of listing to the stage low on October 15, the share price retreated by more than 60%; the cumulative deviation of the increase in the following three trading days exceeded 30%.
This trend reflects two pricing methods of the market for the humanoid robot industry.
The first pricing method focuses on the company's current operating performance. Indicators such as how much revenue has grown, how thick the profit is, who the products are sold to, and whether customers continue to purchase, determine the current operating quality of the enterprise.
The second pricing method focuses on the future industrial space. If humanoid robots can enter factories, warehouses, commercial services and even households, the market size may far exceed the current level. Enterprises with capabilities in motion control, hardware R&D, mass production and cost control have the opportunity to grow from robot manufacturers to general-purpose robot platform companies.
Unitree Robotics obviously has both layers of value at the same time. The company has achieved large-scale sales and profitability, established product and cost advantages in the field of quadruped robots, and its humanoid robot business is also growing rapidly. It is not difficult to understand that the capital market is willing to pay a premium for these capabilities.
The question is, how big is the future market space, and how much time do enterprises need to turn it into revenue and profit?
As of October 20, the rolling P/E ratio of Unitree Robotics is 388.25 times, and the average rolling P/E ratio of the general equipment manufacturing industry in the latest month is 39.51 times. There are differences in the growth stage and business structure between the two, and the reasonableness of the share price cannot be judged solely by the P/E ratio multiple. However, this set of figures at least shows that the current share price has already incorporated quite high growth expectations.
If the humanoid robot market expands rapidly in the next few years, and Unitree Robotics can continuously increase shipment volume, expand customer base and maintain profitability, then today's high valuation will have the opportunity to be gradually digested through performance growth.
Conversely, if the commercialization progress is slower than expected, even if the company still maintains technological leadership, the share price may face pressure before the operating fundamentals.
The market trades for the future, while financial reports test whether the future will arrive on schedule. This is exactly the core of Unitree Robotics' recent risk warning.
02
Who Are the Main Buyers?
When discussing the commercialization of humanoid robots, two issues must be separated first: whether robots have sales volume, and what kind of demand the sales volume comes from.
In terms of revenue scale, Unitree Robotics has gone beyond the stage of simply relying on technology demonstrations.
According to the data disclosed in the company's prospectus, from 2023 to 2025, the company's operating revenue was approximately 159 million yuan, 393 million yuan and 1.699 billion yuan respectively, and the attributable net profit in 2025 was approximately 278 million yuan. The company's revenue scale has expanded rapidly, and it already has a profit base.
Humanoid robots are a business worthy of attention in this round of growth.
From January to September 2025, the revenue of Unitree Robotics' humanoid robots was about 595 million yuan, accounting for 51.53% of the company's total operating revenue in the same period, surpassing quadruped robots for the first time and becoming one of the main sources of revenue.
However, further dismantling the purpose of customers will reveal another picture.
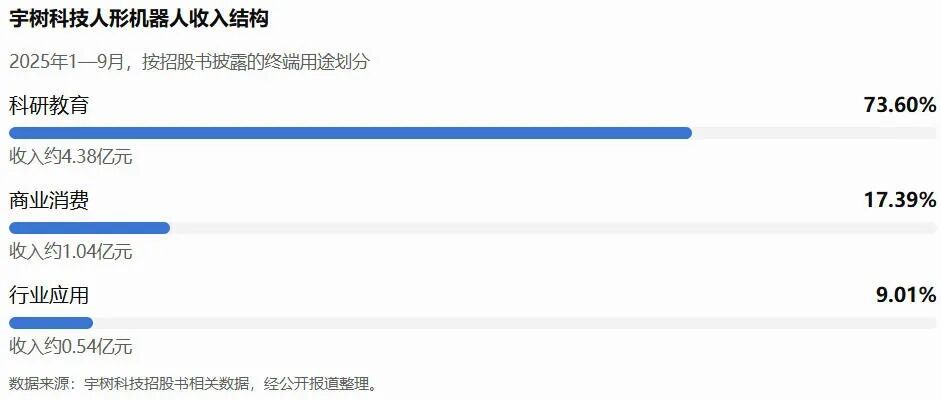
Scientific research and education contributed more than 70% of the humanoid robot revenue. This type of demand is reasonable: universities, scientific research institutions and developers need hardware platforms to carry out motion control, embodied intelligence and algorithm training, and robots that can be delivered quickly and have relatively controllable prices are naturally attractive.
These customers are also promoting industrial progress. After robots enter the laboratory, developers can accumulate motion data, develop applications, and continuously improve control algorithms, laying a foundation for more complex scenarios in the future.
However, scientific research and education procurement and large-scale enterprise deployment follow two sets of commercial logic.
The former values hardware performance, development convenience and experimental value; the latter also needs to examine whether the robot can continuously complete work tasks, whether it can integrate into the existing production process, and whether the input-output ratio is cost-effective.
For example, when a factory purchases robots, it usually calculates the comprehensive costs of equipment procurement, system integration, maintenance, downtime loss, etc., and compares them with the costs of labor or traditional automated equipment. There is still a long distance between a robot completing a demonstration, performing a standardized action, and stably completing production tasks for several consecutive months.
Therefore, the fact that the revenue of Unitree Robotics' humanoid robots accounts for more than half is an important commercial progress; the fact that scientific research and education still occupy the main share also shows that there is considerable room for expansion of industry applications.
What is more noteworthy is whether revenue growth can gradually extend from hardware sales to stable scenario delivery and continuous procurement.
03
Entering Another Round of Competition
There is another easily overlooked problem in the humanoid robot industry: as products become cheaper, it may not only promote market expansion, but also change the profit structure of enterprises.
Data disclosed in Unitree Robotics' prospectus shows that from January to September 2025, the gross profit margin of the company's humanoid robots was 62.91%, lower than the 68.44% in 2024. In the same period, the proportion of the lower-priced G1 model in the company's humanoid robot sales increased significantly.
A decline in gross profit margin does not necessarily mean operating deterioration. More cost-effective products may cover a wider customer group, and the expansion of sales volume will also bring the opportunity to generate scale effects.
However, this set of data reveals a change that requires continuous observation: when robots gradually move from high-priced R&D equipment to larger-scale sales, enterprises need to solve three problems at the same time: cost, performance and profit.
If the price drop mainly comes from the reduction of component costs, the improvement of manufacturing efficiency and large-scale production, enterprises still have the opportunity to maintain good profitability.
If the price reduction speed exceeds the cost reduction speed, or enterprises need to continuously invest R&D and service resources to maintain competitiveness, the growth of sales volume may not bring the same magnitude of profit growth.
Disclosures from other companies in the industry can also help understand the stage of commercialization.
Taking Deep Robotics as an example, the company's updated prospectus shows that in the first half of 2026, it sold a total of 6 humanoid robots, with revenue of 2.79 million yuan, accounting for 1.08% of the operating revenue in the same period. Deep Robotics also stated that its humanoid robot business is still in the initial stage of commercialization, and there is a large gap in shipment volume with enterprises such as Unitree Robotics.
The product positioning and customer structure of Deep Robotics are not exactly the same as those of Unitree Robotics, and the sales volume of this company cannot be used to infer the entire industry. However, this case at least shows that humanoid robots still account for a relatively small proportion in the revenue structure of some enterprises, and there is an obvious time lag between technological R&D and commercialization.
In the broader industry competition, the thresholds that enterprises need to cross also include:
Stability. Whether the robot can work continuously in complex environments, and whether it can recover quickly after a failure.
Task completion rate. In real scenarios, whether the robot can reliably complete the entire work process, rather than a single action.
Comprehensive cost. Whether the sum of equipment, software, deployment, maintenance and downtime losses is better than existing solutions.
Customer repurchase. After the first batch of equipment is delivered, whether customers are willing to expand procurement, and whether enterprises can obtain sustainable orders.
These indicators determine whether robots can move from pilot projects to large-scale deployment, and also determine whether hardware sales can further drive revenue from software, system integration and services.
For Unitree Robotics, its existing product sales volume, manufacturing capabilities and profit base provide competitive advantages. Next, whether the revenue from industry applications can be increased, whether product costs can continue to decline, and whether customer demand can shift from one-time procurement to continuous deployment will better reflect its commercialization progress.
04
The Bubble Is Being Squeezed Out Little by Little by Financial Reports
The recent announcement from Unitree Robotics provides the market with an opportunity to re-examine the investment logic of humanoid robots.
In the past, the industry focused on technological breakthroughs, motion capabilities and product launches. As more and more enterprises enter this field, competition will gradually shift to product delivery, scenario adaptation and operating efficiency.
For investors, there are at least four sets of data worthy of tracking in the next step.
First, revenue structure. In addition to the revenue growth of humanoid robots, it is also necessary to observe the proportion changes of scientific research and education, commercial consumption and industry applications. The continuous increase in industry application revenue can help judge whether products are entering more real business processes.
Second, shipment volume and customer quality. Shipment volume reflects the degree of market acceptance, while customer repurchase, order sustainability and actual usage help to judge the stability of demand.
Third, gross profit margin and cost. If the cost reduction speed can keep up with the price change while the sales volume increases, enterprises will have the opportunity to translate scale advantages into profitability. On the contrary, simply pursuing shipment volume may increase operating pressure.
Fourth, R&D investment and cash flow. Embodied intelligence is still in the stage of rapid iteration, and enterprises need to continuously invest in hardware, algorithms and software. Whether R&D expenditures form product competitiveness and whether operating cash flow can support expansion will affect the quality of long-term development of enterprises.
These indicators can explain the progress of commercialization better than a single demonstration effect or short-term share price performance.
Humanoid robots still have broad imagination for application scenarios. With the decline of hardware costs, the progress of model capabilities and the improvement of development tools, robots are expected to enter more scenarios that were previously difficult to automate. Unitree Robotics has proved that Chinese enterprises can establish competitive advantages in robot hardware R&D, product iteration and large-scale sales.
The next test is to turn this advantage into repeatable and scalable commercial returns.
Unitree Robotics does not deny the industrial prospects of humanoid robots. It reminds the market that technological maturity, demand formation and large-scale commercialization each require their own timetables.
The share price can trade for future growth space in advance, but enterprises still need to prove through every financial report that this growth expectation is becoming a reality.
This article is from the WeChat official account "Alpha Workshop Research Institute", author: Nan Di, published with authorization from 36Kr.