The long-famed "Golden September and Silver October" sales boom has almost vanished, and the auto market has stepped into an era of plain, down-to-earth normal operation with no more obvious seasonal sales spikes.
"For the first time in many years, the 'Golden September and Silver October' phenomenon has basically disappeared, and this situation may become the norm going forward." Gui Shengyue, Vice Chairman and Executive Director of Geely Automobile Holdings Limited, said bluntly at the Geely Auto (0175.HK) Q3 earnings communication conference recently.
Data source: China Passenger Car Association
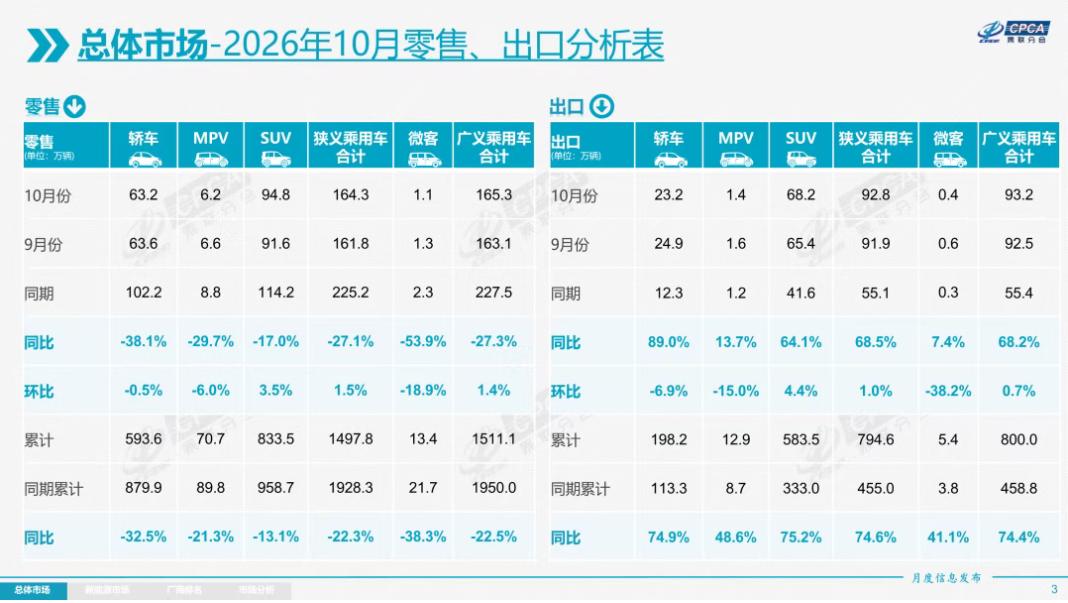
In September 2026, China's retail sales of passenger vehicles reached 1.618 million units, down 28% year-on-year; in October, retail sales of passenger vehicles hit 1.643 million units, down 27.1% year-on-year. From January to October this year, the cumulative retail sales of passenger vehicles reached 14.978 million units, down 22.3% year-on-year. (Note: Data comes from China Passenger Car Association, and the sales volume is the statistical data of narrow-sense passenger vehicles.) The domestic market failed to show the characteristics of the traditional peak season of "Golden September and Silver October" for the second consecutive month, and the decline in October was higher than the cumulative decline in the first ten months, which seemed to pour a basin of cold water on the domestic auto market in the fourth quarter of this year in advance.
On November 9, at the national passenger car market analysis seminar, Cui Dongshu, Secretary-General of China Passenger Car Association, commented on the performance of the passenger car market in September and October 2026: "The traditional concentrated explosive 'Golden September and Silver October' will most likely become a weakened norm. The core reason is that the auto market has entered the era of stock replacement, the scale of first-time car buyers is shrinking, their purchasing power is low, while the high-end group has strong consumption willingness."
On one side are automakers who feel the market changes most directly, and on the other side are research institutions that coordinate macro data. When their conclusions tend to be consistent, it means that the "Golden September and Silver October" peak season concept that has dominated the auto market for more than ten years has truly become a thing of the past.
However, in the view of Node Auto, for today's Chinese automakers, the market is no longer limited to the domestic market. Even if "Golden September and Silver October" no longer exists, the overseas market has become a must-contested area for all players. After years of advocating going global, this autumn of 2026, the overseas market has become a new world for Chinese automobiles.
Uneven Performance of China's Auto Market
Following the sales data, Node Auto finds that the anxiety that has pervaded the auto market in the past few years seems to be fading, replaced by an increasingly clear differentiation state: sales differentiation in vehicle categories, energy types, market structure, and the automaker camps are also accelerating their differentiation.
The most obvious differentiation lies in the retail difference between sedans and SUVs. In October, sedan sales fell 38% year-on-year, MPV sales fell 30%, and SUV sales fell 17%. The decline of sedans is almost twice that of SUVs. Traditional sedans, especially A-class fuel vehicles, once formed an important sales foundation of the auto market. Now, as the mass base of sedans loosens, the proportion of SUVs is getting higher and higher. The popularity of SUV products also shows differentiation, and more incremental sales come from new energy SUVs.
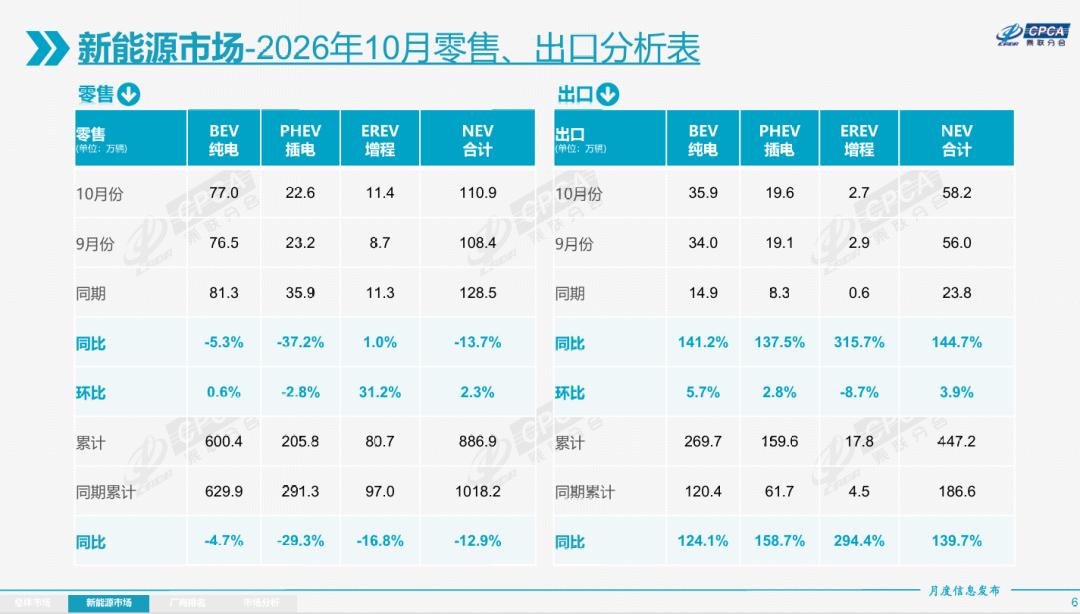
Focus on the new energy vehicle market. In October, domestic retail sales of new energy passenger vehicles reached 1.109 million units, down 13.7% year-on-year, but at the same time, the retail penetration rate of new energy passenger vehicles has reached a record high of 67.5%. China Passenger Car Association pointed out that the rise in the penetration rate of new energy passenger vehicles is mainly due to the faster shrinkage of fuel vehicles, and the retail sales of conventional fuel passenger vehicles fell 45% year-on-year. The differentiation between new energy vehicles and fuel vehicles is also accelerating in these two months. Combined with the rising oil price, more consumers choose to embrace new energy vehicles.
"Against the background of the overall auto market under pressure and retail sales declining year-on-year in October 2026, the strong export performance has become a key variable supporting automakers' sales," said Cui Dongshu. He further analyzed: "The export structure shows obvious characteristics of 'mid-to-low price mainstream models', which directly promotes mainstream independent brands to perform more prominently in the performance differentiation."
In October, passenger vehicle exports reached 928,000 units, up 68.5% year-on-year, accounting for 35% of manufacturers' sales volume, higher than 19% in the same period last year. Among them, new energy passenger vehicle exports reached 582,000 units, up 144.7% year-on-year, accounting for 62.8% of total exports, an increase of about 20 percentage points over the same period last year. Cui Dongshu pointed out that different from the domestic trend where large vehicles attract more attention, the main export force is biased towards mid-to-low price models.
Node Auto believes that as domestic automobile consumption demand enters the stage of stock competition, overseas sales expansion has become an important direction of the auto market. This also means that automakers with the ability to operate both domestic and overseas markets will have more initiative.
Statistics from China Passenger Car Association show that the top three new energy exporters in October are BYD with 165,000 units, Chery with 84,000 units, and Geely with 80,000 units. Focusing on new power brands, we can also find that brands that have already laid out overseas markets have obviously mastered more initiative.
Differentiation of New Power Brand Camp Intensifies
The uneven performance is also particularly obvious on the automakers' sales posters in this "Golden September and Silver October". Leapmotor, XPeng and Xiaomi Auto can still release sales reports easily; while NIO, HarmonyOS Intelligent Mobility and Zeekr, with monthly sales of 30,000 units, have their own joys and sorrows in the current market; Li Auto, known as the "straight-A student", fell below 30,000 units in October, which surprised many people.
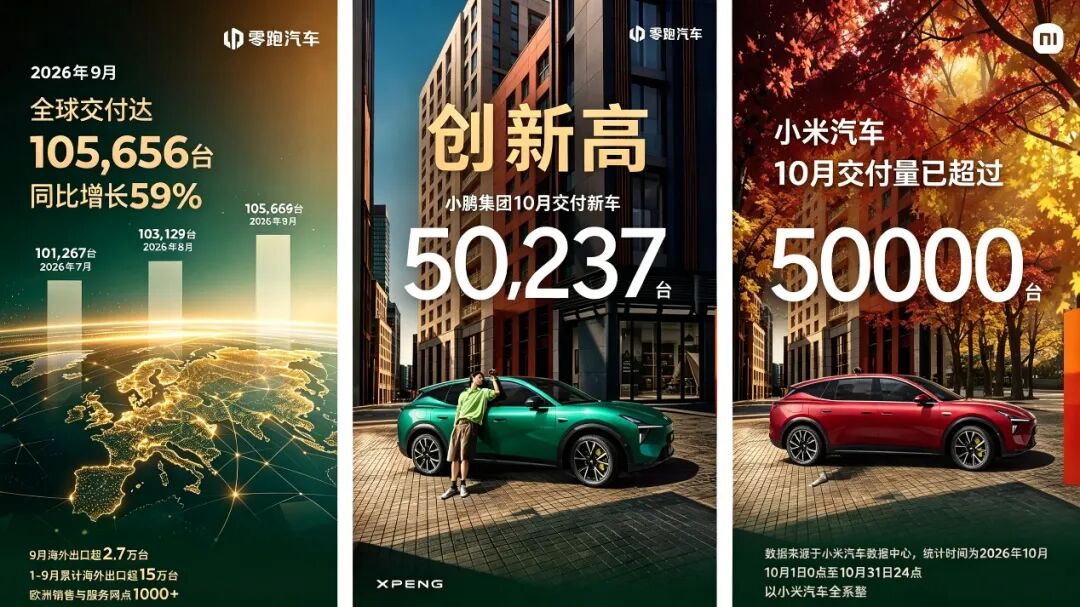
The new power brand camp has become relatively clear. The first echelon dominated by Leapmotor, XPeng and Xiaomi Auto share a common feature: they have turned to system efficiency and overseas markets, and no longer rely on the outbreak of a single model.
Among them, Leapmotor delivered 105,000 units in October, a year-on-year increase of 51%, and has stood at the 100,000-unit level for 4 consecutive months. Node Auto believes that the significance of Leapmotor's consecutive 100,000+ monthly deliveries is not only the good-looking number. Its cooperation with Stellantis overseas has brought Leapmotor dual qualitative changes in scale and brand, which in turn dilutes R&D, procurement and manufacturing costs. In the mainstream price range with the most fierce price competition, Leapmotor has achieved "great results".
Xiaomi Auto delivered more than 50,000 units in October, one step higher than the "more than 40,000 units" in September. The Pengcheng series, which was launched and started delivery in September, expanded Xiaomi Auto's product matrix from pure electric to extended-range electric, and the terminal delivery numbers also increased together. No one will question Xiaomi Auto's marketing capabilities. The only key points to focus on next are whether the production capacity and service network of the new series can keep up with the order rhythm, as well as new moves of Xiaomi's pure electric product line.
XPeng delivered 50,237 units in October, with a month-on-month increase of 22% and a year-on-year increase of 20%, hitting a new monthly high; the bigger surprise came from the overseas market, where its overseas deliveries reached 13,326 units, also setting a new record. For XPeng, it has taken the lead in crossing the threshold of "walking on two legs in both domestic and overseas markets" among the former "Wei Xiao Li" camp. The good news is that the MONA L05, which was launched at the end of October, has a limited-time starting price of 139,800 yuan. After delivery starts in November, it will open up a new mainstream price range for XPeng and bring better-looking sales numbers.
Behind the "Leapmotor, XPeng, Xiaomi" camp, 30,000 units has become a subtle threshold. It is not easy to stand on it, but falling off it will be very bad.
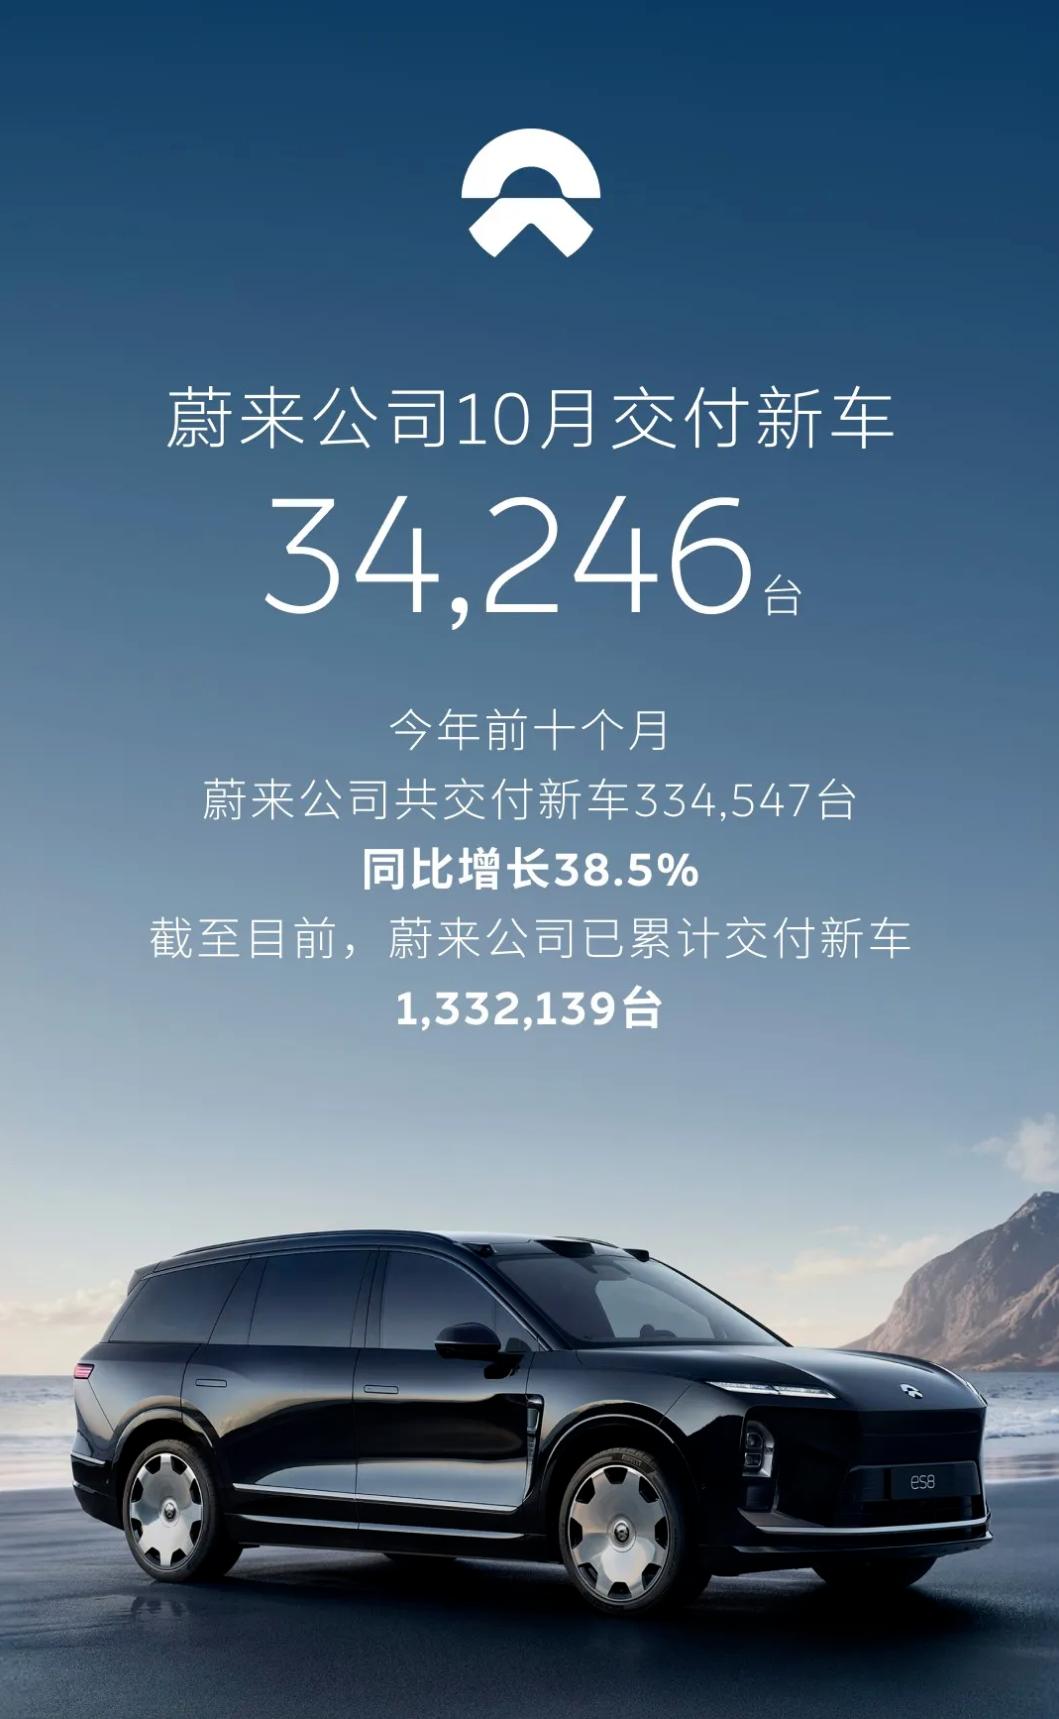
NIO delivered 34,246 units in October, including 18,125 units of the NIO brand, 8,383 units of Le Dao, and 7,738 units of Firefly. The cumulative delivery in the first ten months reached 334,547 units, up 38.5% year-on-year. NIO's three brands have expanded user coverage, but the month-on-month decline in October also reminds Li Bin that the popularity of NIO's flagship SUV needs new models to continue. Whether the supplement of Firefly's long-range version and battery-swapping models can form stable incremental sales remains to be observed. The recent problems such as the ceiling glue peeling off of Firefly products have also plunged this exquisite small car into quality control disputes. As a volume-selling brand, Le Dao's monthly delivery of less than 10,000 units is far from satisfactory. Perhaps this is the root cause of NIO's anxiety even with monthly sales of 30,000 units.
HarmonyOS Intelligent Mobility, which has encountered many troubles in the past two months, delivered 33,537 units in October, with a month-on-month decline. What is more noteworthy than the sales volume is the off-site turmoil of HarmonyOS Intelligent Mobility. First, the cooperation model with AITO changed, Seres took back the core voice of AITO, and Huawei Terminal will take full charge of the other "Four Jie" product lines. Just after this turmoil subsided, right after the National Day holiday, the brake pedal bracket incident of Zunjie V800 plunged HarmonyOS Intelligent Mobility into a bigger public opinion storm, and the truth still awaits the official investigation conclusion. But it is certain that AITO is still an indispensable sales pillar of HarmonyOS Intelligent Mobility. After the turmoil, how the "Four Jie + AITO" camp will develop in the future will become the focus of continuous attention in the industry.
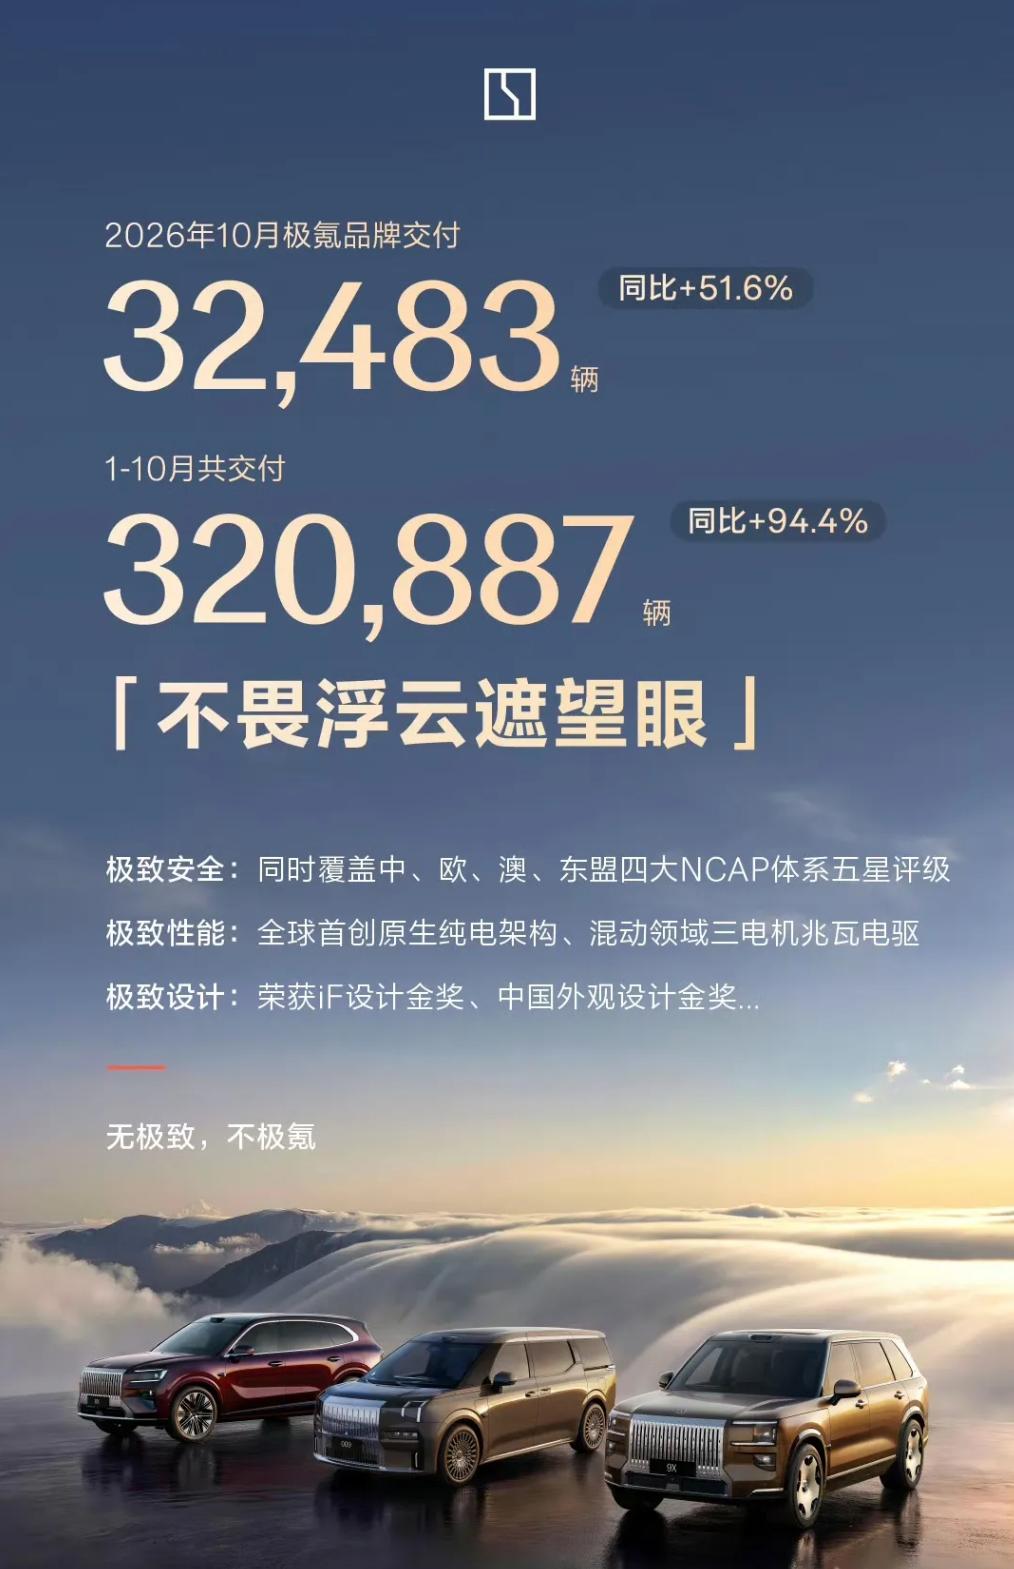
Zeekr delivered 32,483 units in October, surging 51.6% year-on-year. The cumulative delivery in the first ten months reached 320,887 units, with a year-on-year increase of 94.4%, which has already crossed the annual target of 300,000 units in advance. After a series of adjustments to the organizational structure and product lineup, Zeekr has returned to the track of rapid growth. In the view of Node Auto, the market recognition of its high-end products is its most solid asset. As long as it stabilizes the product delivery rhythm, relying on Geely Group's layout in overseas markets, Zeekr is expected to return to the first echelon.
Of course, there are also accidents. The "straight-A student" Li Auto seems to have underperformed this time. After delivering 31,817 units in September, the delivery volume in October dropped to 29,025 units, falling below 30,000 units for the first time. This is obviously not the level that Li Auto should have, but on November 1, Li Auto still generously released its sales poster, as if it was not affected by the "underperforming exam".
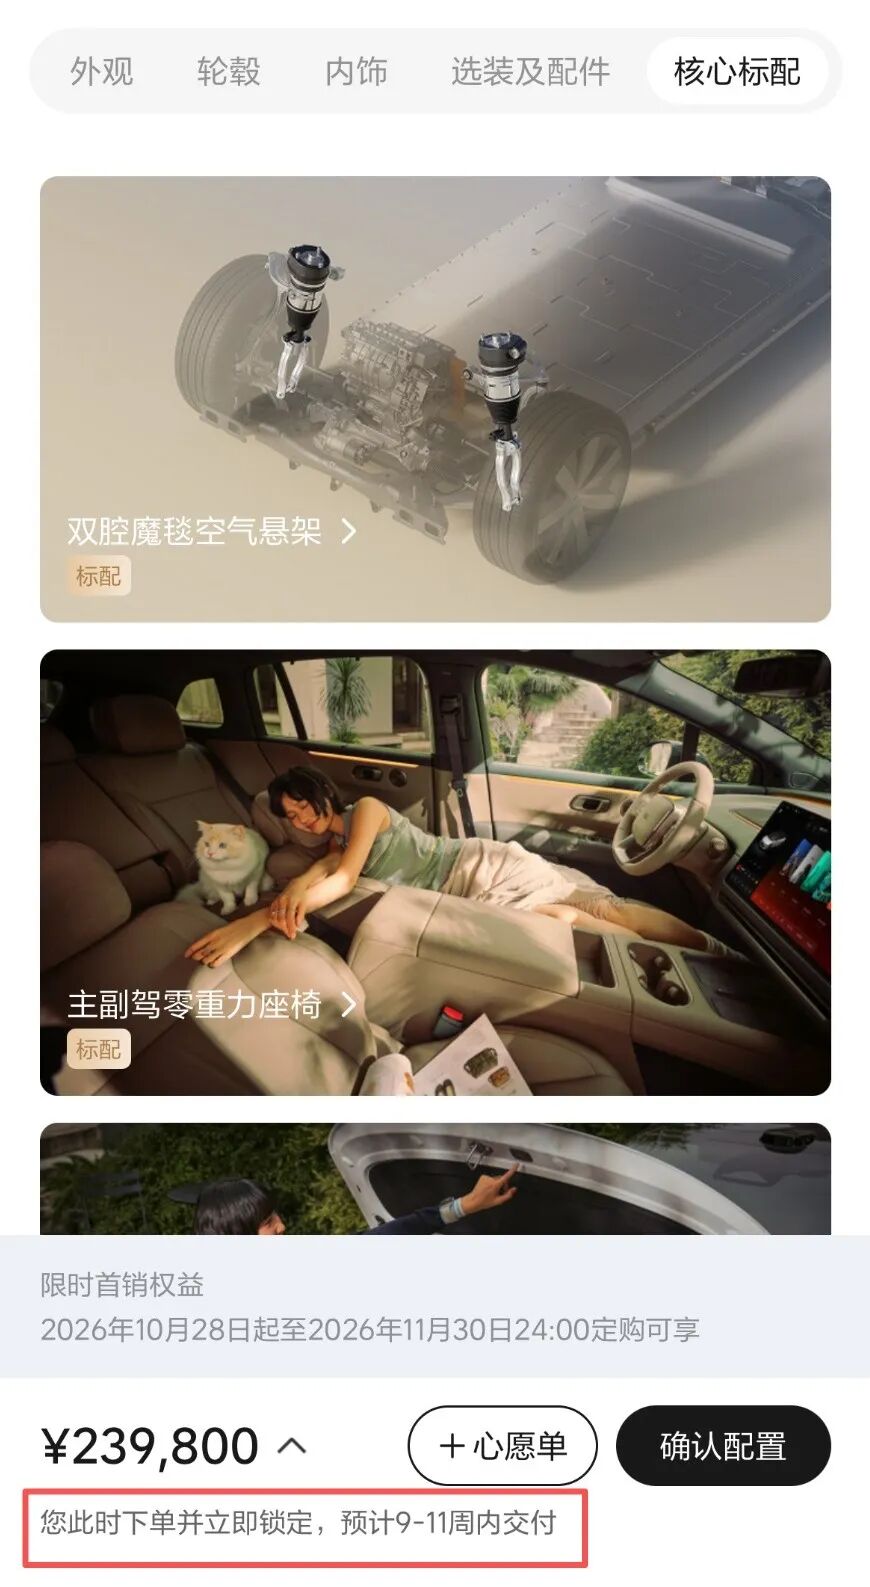
(Orders for the new Li Auto i6 placed on November 10 are scheduled to be delivered within 9-11 weeks)
Li Auto's calmness is actually well-founded. First of all, in the second half of 2026, Li Auto has significantly accelerated the speed and frequency of product iteration. In recent months, it has completed the product updates of Li Auto L9, L8 and L6 successively, and launched Li Auto i9, the new generation MEGA Home version and the new i6 based on the brand-new pure electric platform. Both the extended-range and pure electric product lines have entered a concentrated renewal period. Secondly, the new Li Auto i6 has received a large number of orders, and the next two months will enter a high-intensity delivery period. Although Li Auto's official only disclosed that "orders in 72 hours have far exceeded the same period last year", according to rough estimates by third parties based on the delivery cycle and monthly production capacity on the Li Auto App, the total orders of the new Li Auto i6 are at the level of about 50,000 to 55,000 units. On November 10, Node Auto tried to place an order for the new i6 on the Li Auto App and the system showed that the estimated delivery cycle was 9-11 weeks. From this time calculation, the latest delivery window of some orders may be scheduled to early 2027.
Conclusion
At the end of the year, the biggest suspense in the auto market is the completion rate of annual targets. Under the trend that "Golden September and Silver October" has become the past, there may not be many brands that can achieve great results this year.
As Node Auto mentioned earlier, judging from the cumulative deliveries in October, Zeekr is currently the only brand that has clearly completed its annual target: the cumulative delivery in the first ten months is 320,887 units, which has exceeded its annual target of 300,000 units.
Leapmotor, which has maintained consecutive 100,000+ monthly deliveries, has a 2026 target of hitting 1 million units. The cumulative delivery in the first ten months is about 772,700 units, leaving about 227,300 units to complete. Calculated over two months, the average monthly delivery