Tokens have even found their way into the sales scenarios of Li Jiaqi's live stream. Why are companies represented by "Silicon Flow" still operating at a loss?
On the evening of November 2, the personal monthly pass of Qianwen Office was put on sale in Li Jiaqi's live stream at a promotional price of 0.01 yuan. Nearly 100,000 copies were sold within half an hour, with the total corresponding AI computing power quota reaching approximately 2 trillion Tokens.
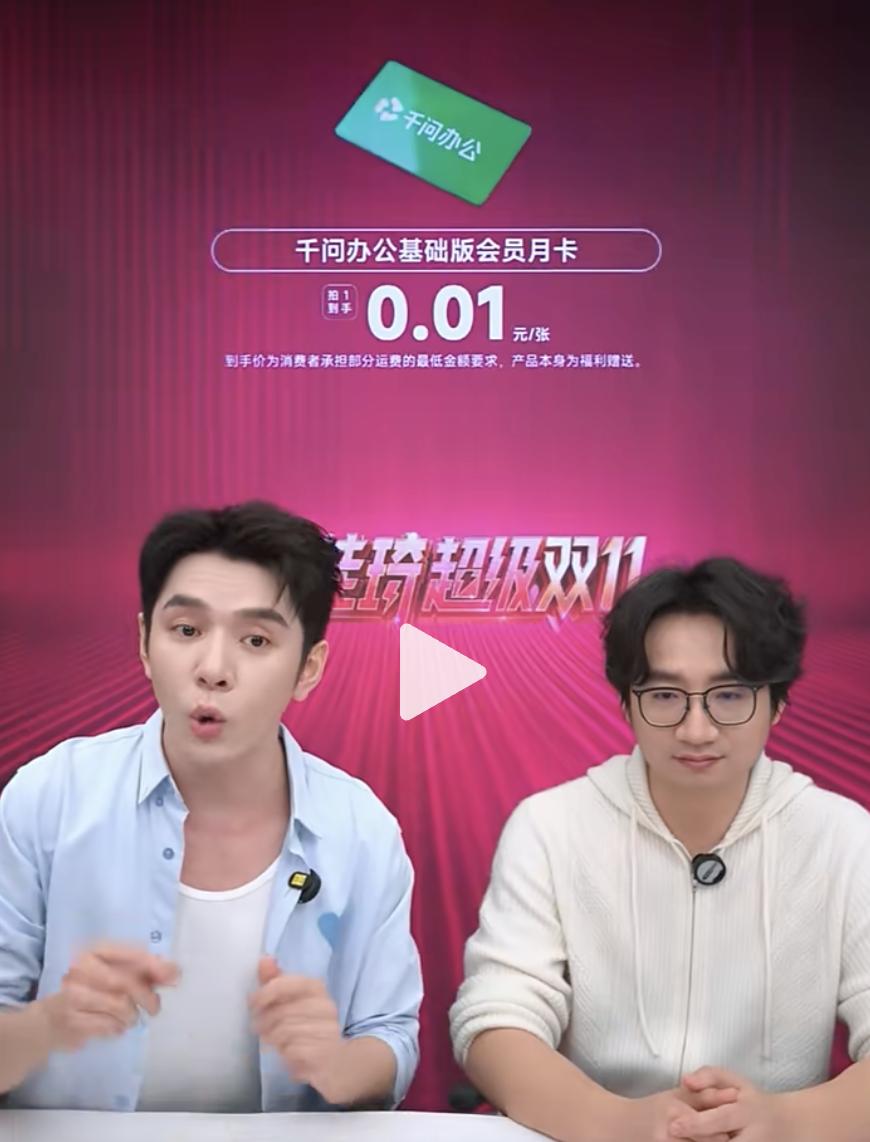
Although what is sold is a service, what users purchase is an office application membership, and these Tokens can be used for office tasks such as document writing, data processing and PPT production. The skyrocketing popularity of Token sales in the live stream has raised a practical question: when consumers pay for AI to process spreadsheets, can the enterprises providing model inference services in the background make profits from it?
Two companies that are seeking to go public provide observation samples for this question. Recently, two enterprises that have laid out Token services are pushing forward their listing plans in Hong Kong. On October 30, the official website of the China Securities Regulatory Commission showed that the status of overseas listing filing materials of Silicon Flow was "received". Another enterprise, JiuZhang Yunji, which is transforming to a Token factory, also submitted its listing application to the Hong Kong Stock Exchange on September 29.
The two companies took different paths to enter this business, but both are making layouts to transform into Token factories. According to the financial data disclosed by the two companies, the Token business that has high expectations placed on it has not yet delivered a report card of sustained profitability.
For every 1 yuan of revenue a Token factory earns, it incurs 2.19 yuan in costs
In Li Jiaqi's live stream, users care about whether the service they buy can actually complete their work. Token is a usage quota or a background measurement unit here, not a commodity that can be used independently without being tied to applications.
The so-called Token factory mainly provides model inference services for developers and enterprises. What it delivers is the result after the model processes the request, and Token is usually used to measure the input, output and corresponding fees.
Different from the mode of direct login at the AI product end, developers submit tasks through interfaces, and the platform is responsible for deploying models, scheduling computing power and returning results, so customers do not need to purchase GPUs and maintain the entire operating environment on their own. Compared with directly using office applications, developers also need to integrate these capabilities into their own products. The difference lies in the service level: Token factories usually provide multiple models for developers to choose from.
Even within the same Token service provider, revenue sources are not the same.
Silicon Flow mainly provides three types of services: developers and small and medium-sized enterprises can directly call the model and pay according to usage; enterprises with higher requirements for performance and stability can reserve exclusive computing power; large institutions can deploy the model service system to the institution's data center through Silicon Flow.
The first two types of services are continuously provided by the platform on the cloud, and the latter type mainly charges fees for software licensing, implementation and maintenance. All the above services are centered on model inference, but they bear different computing power costs and adopt different charging methods.
The differences in finance are also very obvious. In 2025, Silicon Flow recorded a revenue of 55.33 million yuan, of which the revenue of serverless Token service charged directly by Token usage was about 14.3 million yuan. This service, together with the dedicated instance service that reserves computing power for enterprises, constitutes the company's public cloud business, with a total revenue of 29.261 million yuan.
The other part of revenue comes from the on-premise deployment business, which deploys the model service system to the customer's own data center and charges fees for software licensing, deployment and maintenance. In 2025, this business generated a revenue of 26.069 million yuan, with a gross profit margin of 82.5%.
There is a huge gap in gross profit between the two types of businesses: the gross profit margin of on-premise deployment is 82.5%, while that of public cloud business is -119%. This means that for every 1 yuan of revenue earned by the entire public cloud segment in that year, it had to bear a direct cost of about 2.19 yuan.
The Token service of JiuZhang Yunji is at an earlier stage.
In 2025, the company's revenue was about 1.098 billion yuan, of which the intelligent computing infrastructure solution contributed about 1.002 billion yuan, accounting for 91.2%; in the first half of 2026, this business still accounted for 73.8% of the revenue. Although its Alaya Token service has signed about ten contracts, it has not contributed revenue in the disclosed data.
The company as a whole is still in a loss state. The net loss in 2025 was about 336 million yuan; the net loss in the first half of 2026 was about 1.095 billion yuan, of which the loss from changes in fair value of financial liabilities was about 1.068 billion yuan. According to the disclosed non-IFRS caliber, the adjusted net loss was 14.884 million yuan.
The two companies have different commercialization progress in the Token factory business. Silicon Flow has generated Token service revenue, but the relevant public cloud segment still faces gross loss. The main revenue of JiuZhang Yunji still comes from infrastructure delivery, and the financial contribution of Token service needs to be waited for subsequent disclosure.
Since revenue and profit are yet to be verified, why do both companies want to transform into Token factories? Perhaps they are optimistic about the continuous inference demand that occurs after the model is put into use.
Moving from intelligent computing centers to Token factories, what are enterprises competing for?
Every time an AI application processes a request, it may bring a new inference task. For computing power service providers, opportunities lie not only in building data centers, but also in continuously providing operation services for models after they go online.
The Frost & Sullivan data cited in the application documents of Silicon Flow points out that China's Token consumption will reach about 53.20 exabytes in 2030, with a compound annual growth rate of about 638.3% from 2025 to 2030.
Enterprises also expect that more computing power will be used for model inference in the future. In May, Yang Yuanqing, Chairman and CEO of Lenovo Group, mentioned that currently about 70%-80% of AI computing power is used for training, and 20%-30% for inference, but "this trend will be reversed in the future, and more than 70% of AI computing power will be used for inference".
For computing power service providers, this means that more potential revenue opportunities will come from the continuous inference demand generated after the model is put into use. JiuZhang Yunji and Silicon Flow are striving for this kind of continuous revenue from different starting points.
As early as 2024, Yuan Jinhui, founder of Silicon Flow, positioned the company as a "Token factory", hoping to provide directly callable model services for developers and enterprises through inference software and resource scheduling.
The path of JiuZhang Yunji has undergone several changes: it initially mainly provided AI basic software, turned to intelligent computing infrastructure construction in 2023, launched intelligent computing cloud services in September 2024, and then launched Alaya Token in 2026. From building intelligent computing centers and providing computing resources to charging by Token usage, the company has gradually extended to the model operation link.
Enterprises bet on Token factories not only because they are optimistic about market growth, but also because they hope to change their original profit model. Compared with earning revenue around project delivery, model inference services have the opportunity to generate continuous call revenue along with the operation of AI applications.
For example, the current business of JiuZhang Yunji is mainly divided into two parts: first, helping local governments and enterprises build intelligent computing centers, providing services such as hardware procurement, system integration and software deployment, and charging by project; second, obtaining computing power through long-term leasing and other methods, then providing computing resources to customers through JiuZhang Intelligent Computing Cloud, and charging by subscription period or actual usage.
For JiuZhang Yunji, Token service can allow the company to further extend from infrastructure delivery and computing power operation to continuous model services. This not only has the opportunity to break through the growth limit of the AIDC construction business that relies on new projects, but also can obtain continuous revenue through repeated calls to the model by customers, and expand the monetization channels of existing computing power resources.
On the side of Silicon Flow, its advantage lies in being able to integrate computing power and models from different manufacturers into the same platform. Small and medium-sized enterprises and developers do not need to buy GPUs and deploy models by themselves, and can call multiple models on demand; large enterprises can choose exclusive computing power or on-premise deployment according to performance, stability and data management requirements.
Silicon Flow is also looking for business for the upstream: helping chip manufacturers adapt to models, finding users for computing power suppliers, and allowing model manufacturers to reach more customers. The company hopes to gather scattered resources and demands, and through inference optimization and unified scheduling, make the same computing power process more tasks and reduce idleness, so as to reduce service costs.
However, the fact that output can be improved technically does not mean that there are enough customers paying continuously in business.
Token services need to reserve computing power to undertake requests submitted by customers at any time. When resources are obtained through fixed leasing, the platform also needs to pay fees when the servers are idle. Silicon Flow explained in its application documents that the negative gross profit of the public cloud business mainly comes from the direct computing power cost required to ensure capacity and service availability, and these expenditures exceed the early paid revenue. This means that whether expanding the call volume can improve business performance depends on whether the new paid revenue can cover the corresponding costs.
Even if the unit cost decreases, the platform still has to face competition. On the one hand, there are the subscription plans of model manufacturers themselves, and on the other hand, there are other Token manufacturers. Independent Token manufacturers need to prove that multi-model access, stability and deployment support are worth paying for.
In Li Jiaqi's live stream, the sales volume of the promotional monthly pass is still several steps away from actual usage and renewal. Token factories are also facing similar tests: whether registered users and call volume can be converted into continuous payment, and whether paid revenue can cover computing power, R&D and customer acquisition expenditures, etc.
The market judges whether the Token factory business is viable by looking at the changes in paid calls, customer renewal and gross profit of each business. Capital is betting on future growth, and Token factories need to deliver this expectation with sustained profitability.
This article is from the WeChat official account "The Fourth Wave", written by Wang Chen, and published with authorization from 36Kr.