Leading real estate developers are ramping up their efforts, and the gap between Poly and China Overseas in the competition for the top position is only 160 million yuan.
The peak sales season of "Golden September and Silver October" has passed, and subtle changes have emerged in the sales performance of leading real estate enterprises in October.
Among the top 10 leading real estate enterprises, 8 have seen their cumulative full-caliber sales growth rate outperform the overall market, of which China Overseas Land & Investment, China Resources Land, China Merchants Shekou, China Jinmao, Greenland Holdings have recorded positive growth.
Meanwhile, the number of real estate enterprises with sales exceeding 100 billion yuan and 10 billion yuan is still declining. From January to October 2026, there are only 5 real estate enterprises with full-caliber sales exceeding 100 billion yuan, 2 fewer than the same period last year. Focusing on leading real estate enterprises, the competition for scale has become increasingly fierce, especially the fight for the top position in the industry, which has entered a stage of close confrontation.
01
Looking at the full-caliber sales ranking alone, the gap between the top two leading enterprises has narrowed to a low level in recent years.
From January to October, Poly Developments and Holdings took the first place with full-caliber sales of 199.0 billion yuan, followed by China Overseas Land & Investment with 198.84 billion yuan, with a gap of only 160 million yuan between the two.
What does this mean? The property launch pace of any single project in the next two months may rewrite the final annual ranking.
The head-to-head seesaw battle between Poly and China Overseas Land & Investment has almost run through the whole year. In the first 8 months, relying on the concentrated launch of high-priced properties in core cities, China Overseas Land & Investment once overtook Poly by a narrow margin of 540 million yuan in full-caliber sales. In September, Poly relied on the concentrated property launch in multiple cities to take the lead again with a cumulative sales amount 200 million yuan higher, and the gap between the two narrowed to 160 million yuan from January to October.
The main reason why Poly's sales are gradually overtaken by China Overseas Land & Investment lies in the difference in investment rhythm and land reserve structure between the two leading enterprises.
Judging from the land acquisition situation of the two major real estate enterprises in the past two years, the proportion of China Overseas Land & Investment's land acquisition in first-tier cities has remained stable above 72%, while Poly's proportion in first-tier cities dropped sharply to 48% in 2025. Entering 2026, the proportion of Poly's investment amount in first-tier cities in the first three quarters rebounded to 69%, up 0.3 percentage points from the first half of the year, and its investment intensity in first-tier cities is increasing. In July, it won two plots in Yangpu and Xuhui, Shanghai through joint land acquisition with a total price of 23.18 billion yuan; at the end of September, it won the Pazhou South plot in Guangzhou with 3.817 billion yuan, and in October, it won the "Science City Plot" in Guangzhou with 1.665 billion yuan.
According to China Overseas Land & Investment's 2026 interim performance disclosure, from the beginning of 2026 to late August, the company added a total of 18 new land parcels in the year, with equity land price of 33.34 billion yuan. The equity land price of first-tier cities accounts for 79%, and the total proportion of first-tier cities and strong second-tier cities accounts for 95%, almost all funds are invested in high-energy-level cities. Thereafter, in September, China Overseas Land & Investment successively won 5 plots in the core areas of Shanghai, Shenzhen, Xi'an and Shenyang, including two scarce plots in Zhenru, Putuo and Laoximen, Huangpu in Shanghai, with a total land acquisition amount of 18.907 billion yuan, and it also spent 2.55 billion yuan at a high premium to acquire the core residential plot in Futian, Shenzhen.
The competition between the two top players will continue in the future.
Completely different from the stalemate in the full-caliber ranking, the pattern shows obvious differentiation when switching to the equity sales amount caliber.
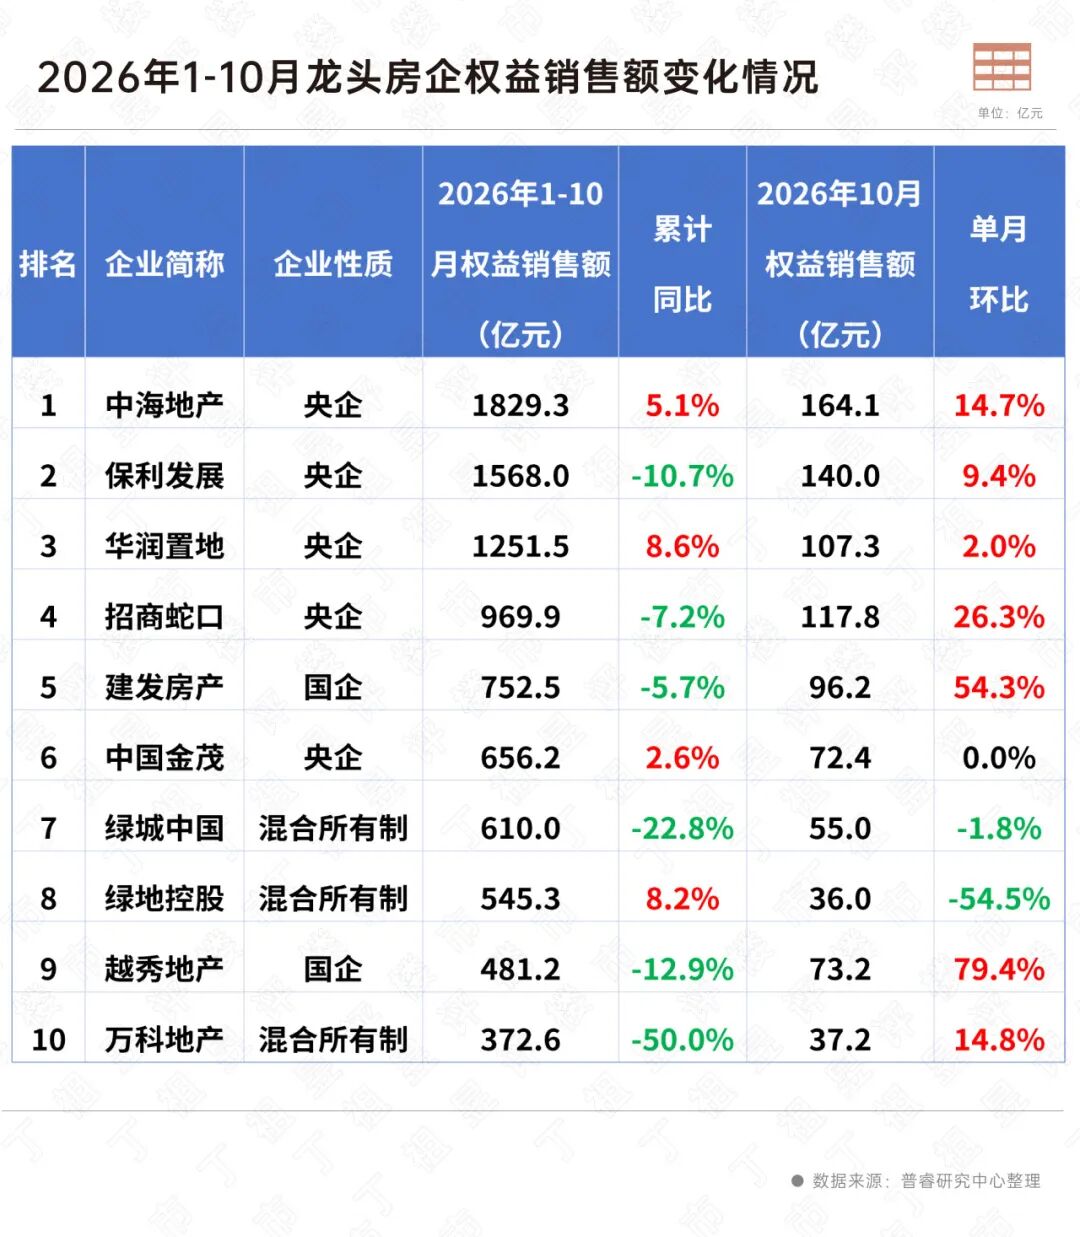
From January to October, China Overseas Land & Investment steadily ranked first in the industry with equity sales of 182.93 billion yuan, 26.13 billion yuan higher than the second-ranked Poly Developments and Holdings' 156.80 billion yuan, and its leading advantage has further expanded. Since the beginning of this year, most of the land acquired by China Overseas Land & Investment in typical cities across the country is obtained through sole proprietorship with 100% equity ratio, which is also an important reason for it to widen the gap in the equity sales ranking.
In terms of cumulative growth rate, China Overseas Land & Investment also maintains positive growth, up 5.1% year-on-year; Poly Developments and Holdings' cumulative year-on-year decline is 10.7%, showing a large growth difference between the two in terms of equity sales.
Judging from the performance of a single month in October, the trend of leading real estate enterprises sprinting for the year-end closing is very obvious.
Under the equity caliber, China Overseas Land & Investment achieved 16.41 billion yuan in a single month, ranking first in the industry, with a month-on-month sales growth of 14.7%; Poly's month-on-month growth was 9.4%, reaching 14.0 billion yuan.
In addition to the two top players, Yuexiu Property and C&D Real Estate recorded a sharp month-on-month increase of 79.4% and 54.3% respectively in their single-month equity sales amount, and China Merchants Shekou's month-on-month growth reached 26.3%. The single-month sales surge of leading real estate enterprises has also driven the cumulative decline to continue narrowing.
02
On the one hand, leading real estate enterprises are competing for scale, on the other hand, regional small and medium-sized real estate enterprises have become an important growth force.
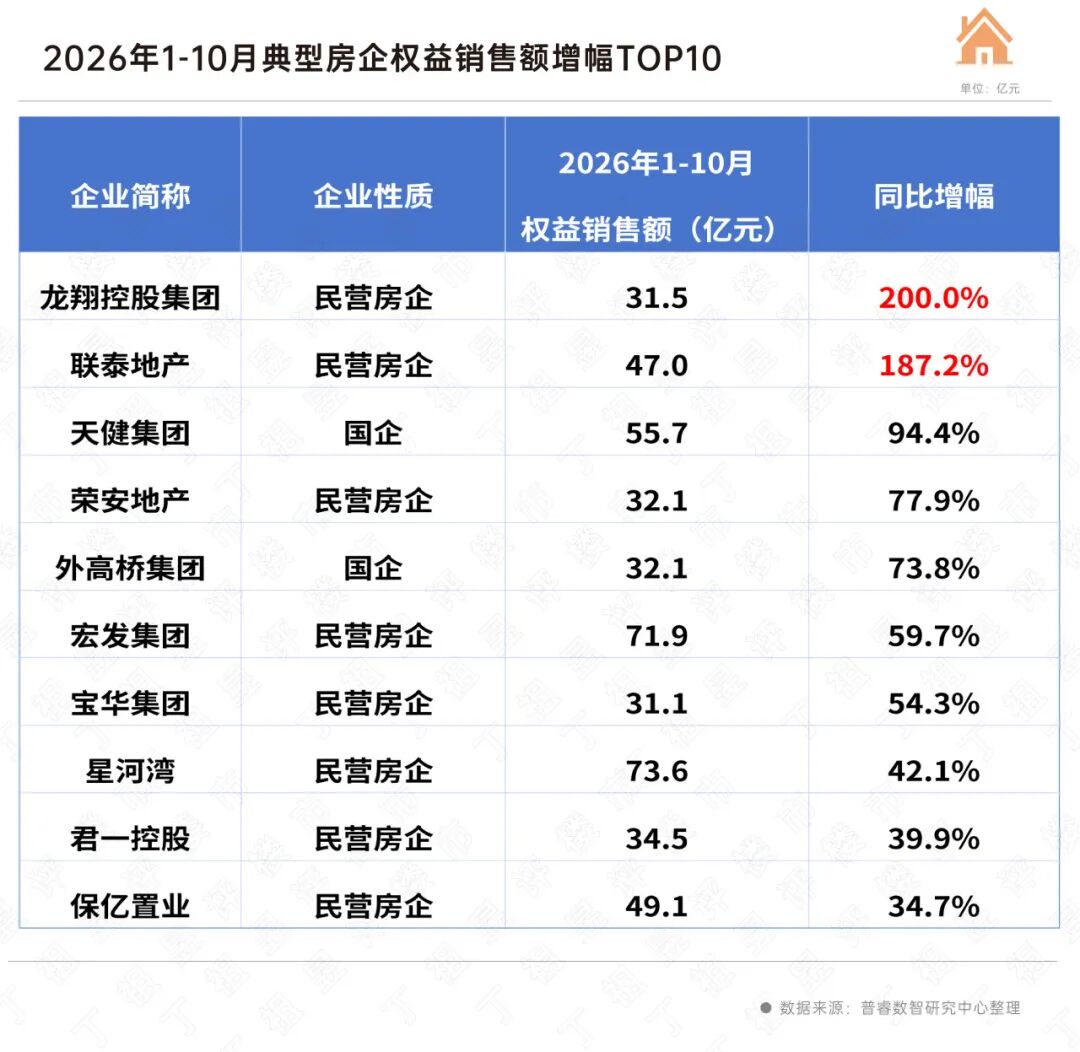
Among the 30 real estate enterprises that achieved positive growth in equity sales from January to October, 2 recorded a growth rate of over 100%, both of which are private enterprises. Longxiang Holdings Group led the way with 200.0% growth, and Liantai Real Estate grew by 187.2%.
In the top 10 of equity sales growth rate, private real estate enterprises occupy 8 seats. Among them, Rong'an Real Estate increased by 77.9% year-on-year, Hongfa Group increased by 59.7% year-on-year, Baohua Group's sales increased by 54.3% compared with last year, and Xinghewan's growth rate also reached 42.1%; state-owned enterprises occupy 2 seats, Tianjian Group grew by 94.4%, ranking third on the growth rate list, and Waigaoqiao Group grew by 73.8%, ranking fifth on the growth rate list.
Most of these high-growth real estate enterprises are deep-cultivating private enterprises in emerging regions, and they have a typical common feature: they do not pursue national scale expansion, most of their equity sales are less than 10 billion yuan, and Xinghewan, the enterprise with the largest scale in the top 10 of equity sales growth, only recorded 7.36 billion yuan in equity sales in the first 10 months. They generally focus on local core regions, accurately target segmented customer groups, and build competitive barriers through product differentiation and local resources.
On the whole, the October sales ranking is essentially a concentrated reflection of the development logic of different echelons in the industry.
The camp of leading central state-owned real estate enterprises competes in urban layout, goods value structure and capital efficiency, and continuously occupies market share by virtue of scale advantages. The close fight for the top position is a direct manifestation of the improvement of industry concentration.
Regional small and medium-sized real estate enterprises, by virtue of deep local cultivation, product differentiation and flexible mechanisms, look for growth space in segmented tracks and explore different breakthrough paths.
In the last two months of the year, the battle for the "top spot" in the industry between Poly and China Overseas Land & Investment will remain stalemate. For more real estate enterprises, instead of competing for scale ranking, finding a suitable survival path for themselves is the most important thing.
This article is from the WeChat Official Account "Ding Zuyu's Real Estate Review", author: Editorial Department, released with authorization from 36Kr.