Five securities firms recorded net profits exceeding 10 billion yuan in the first three quarters.
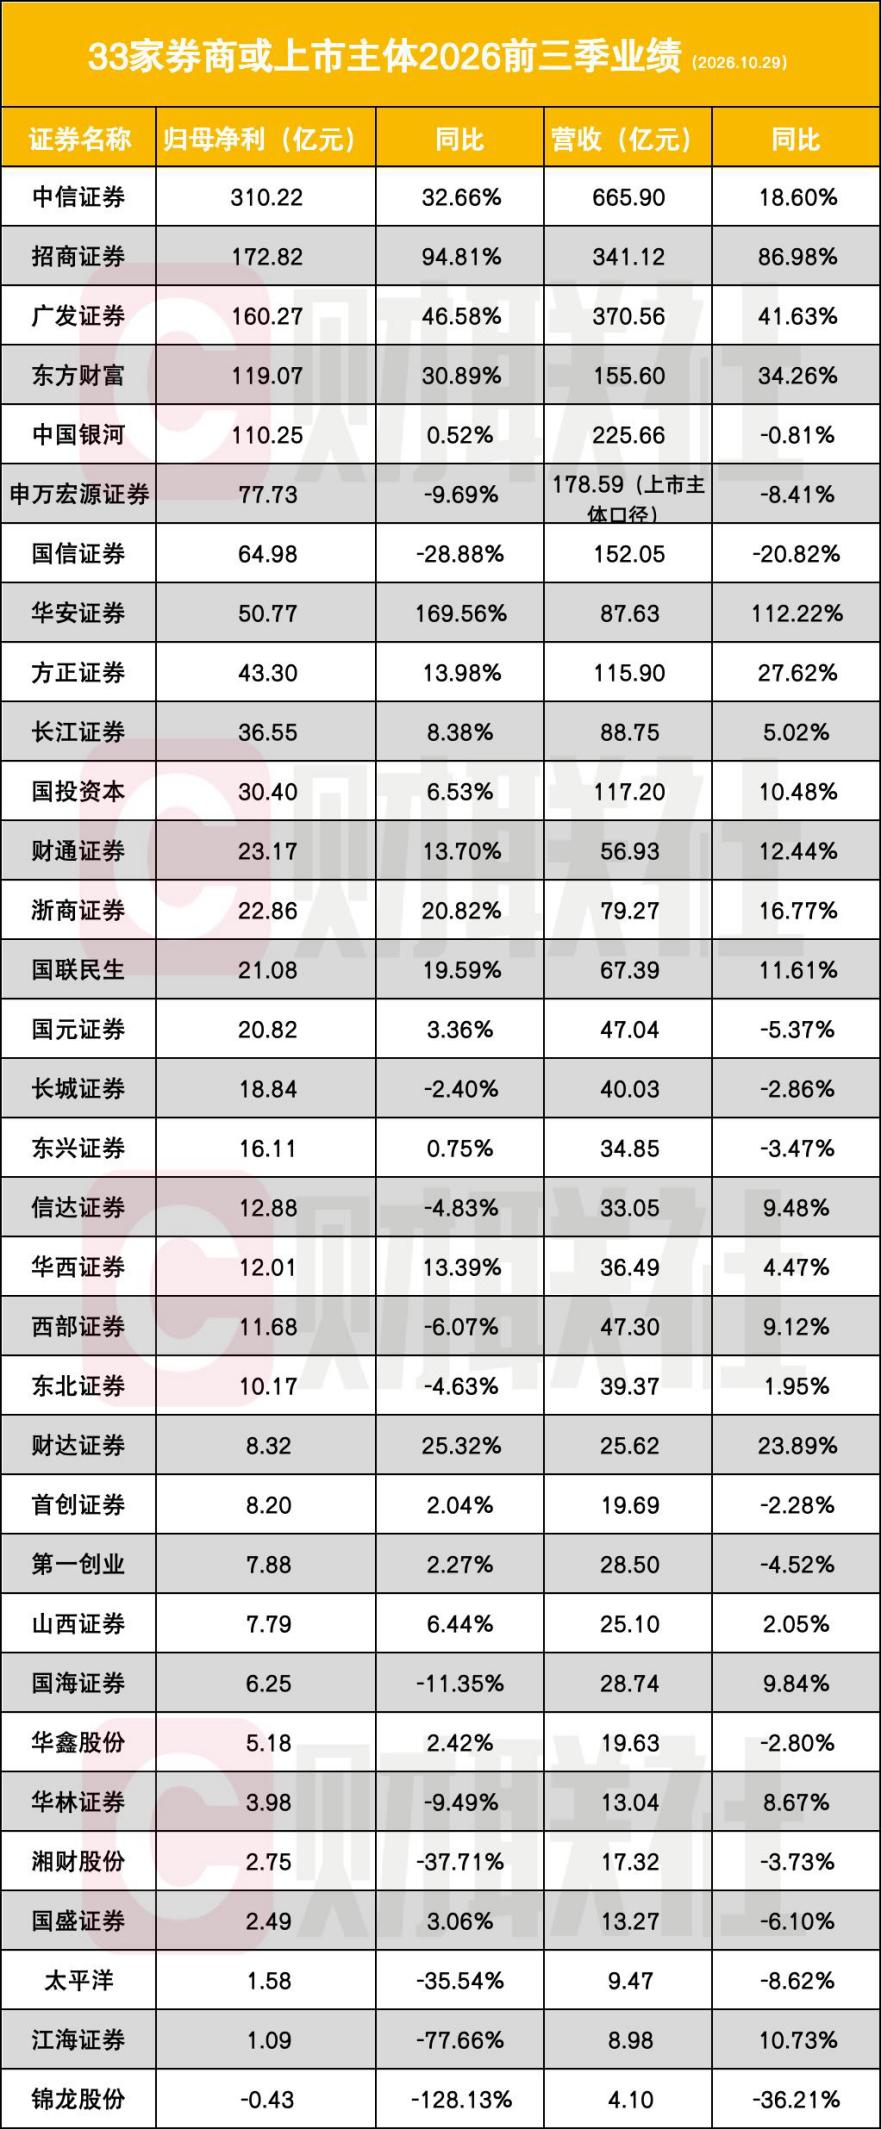
As the disclosure of 2026 Q3 financial reports draws to a close, the full picture of securities firms' performance is gradually becoming clear. On October 29, 16 more listed securities firms released their performance data for the first three quarters of 2026. Up to now, a total of 33 securities firms or listed entities have disclosed their performance for the first three quarters. The industry as a whole is characterized by "steady growth in the first three quarters, and sharp fluctuations in the standalone third quarter".
Among the 33 disclosed securities firms, 21 saw positive year-on-year growth in their net profit attributable to shareholders in the first three quarters, but in the standalone third quarter, only 6 maintained positive growth while 27 recorded a year-on-year decline, indicating that the test of market fluctuations on the profitability of securities firms is intensifying.
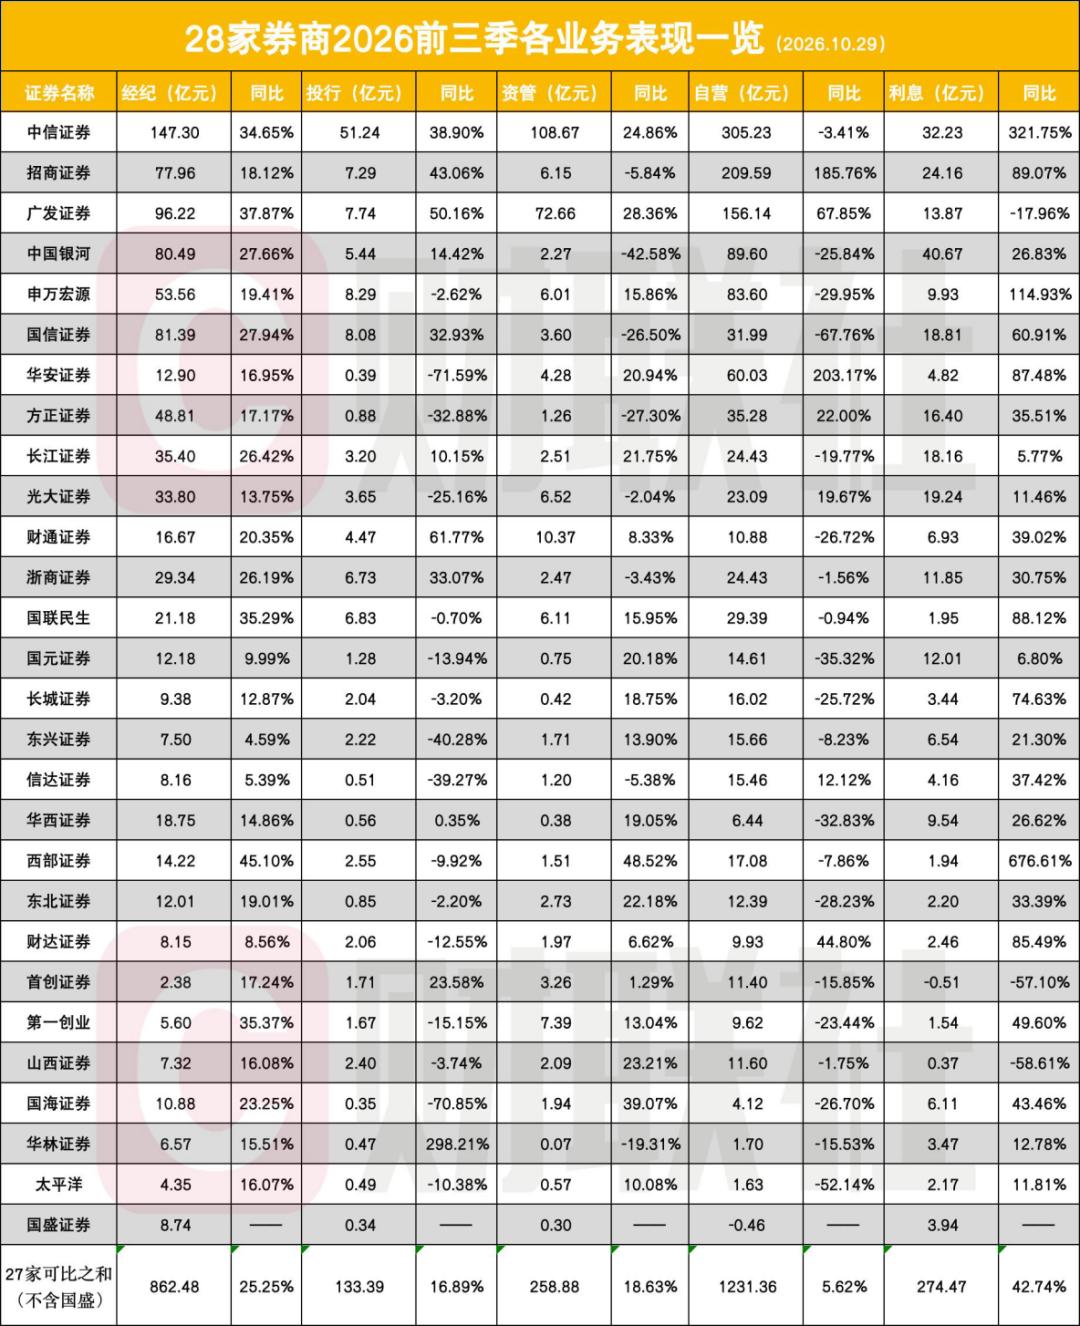
Based on the segmented business data of 27 comparable securities firms, the core logic driving performance differentiation can be clearly observed: the proprietary trading business presents an extreme "double-edged sword" effect, which becomes the main cause of the sharp performance volatility in the single Q3; the net interest income has collectively rebounded, becoming the most certain growth point in the first three quarters; the Matthew effect in the investment banking business has intensified, with resources further concentrated in leading firms; the brokerage and asset management businesses maintain steady growth, showing a differentiated pattern of uneven performance across the sector.
Net profit of 5 securities firms exceeded 10 billion yuan in the first three quarters
In terms of cumulative performance, the leading effect remains prominent. There are 5 firms in the "first echelon" with net profit attributable to shareholders exceeding 10 billion yuan in the first three quarters, namely CITIC Securities (31.022 billion yuan), China Merchants Securities (17.282 billion yuan), GF Securities (16.027 billion yuan), East Money (11.907 billion yuan) and China Galaxy Securities (11.025 billion yuan). Shenwan Hongyuan (7.773 billion yuan) and Guosen Securities (6.498 billion yuan) followed closely behind.
In terms of growth rate, the industry shows extreme differentiation. Huaan Securities became the biggest "dark horse" with a year-on-year growth rate of 169.56%, mainly benefited from the fair value change income brought by the listing of Changxin Technology equity held by its alternative investment subsidiary; China Merchants Securities also delivered a strong performance, with its net profit surging 94.81% year-on-year, nearly doubling. In addition, leading firms including GF Securities (+46.58%), CITIC Securities (+32.66%) and East Money (+30.89%) all recorded growth rates exceeding 30%, demonstrating strong anti-cyclical resilience.
For the third quarter, among the 33 samples, 27 securities firms recorded negative year-on-year growth in single-quarter net profit, 13 of which saw their year-on-year growth rate drop by more than 50%, and 3 firms turned from profit to loss year-on-year, namely Jinlong Co., Ltd., Jianghai Securities and Xiangcai Co., Ltd. 2 leading securities firms saw significant declines, namely Shenwan Hongyuan (-62.21%) and Guosen Securities (-79.66%); CITIC Securities (-20.19%) and China Galaxy Securities (-27.95%) also recorded considerable declines in the third quarter.
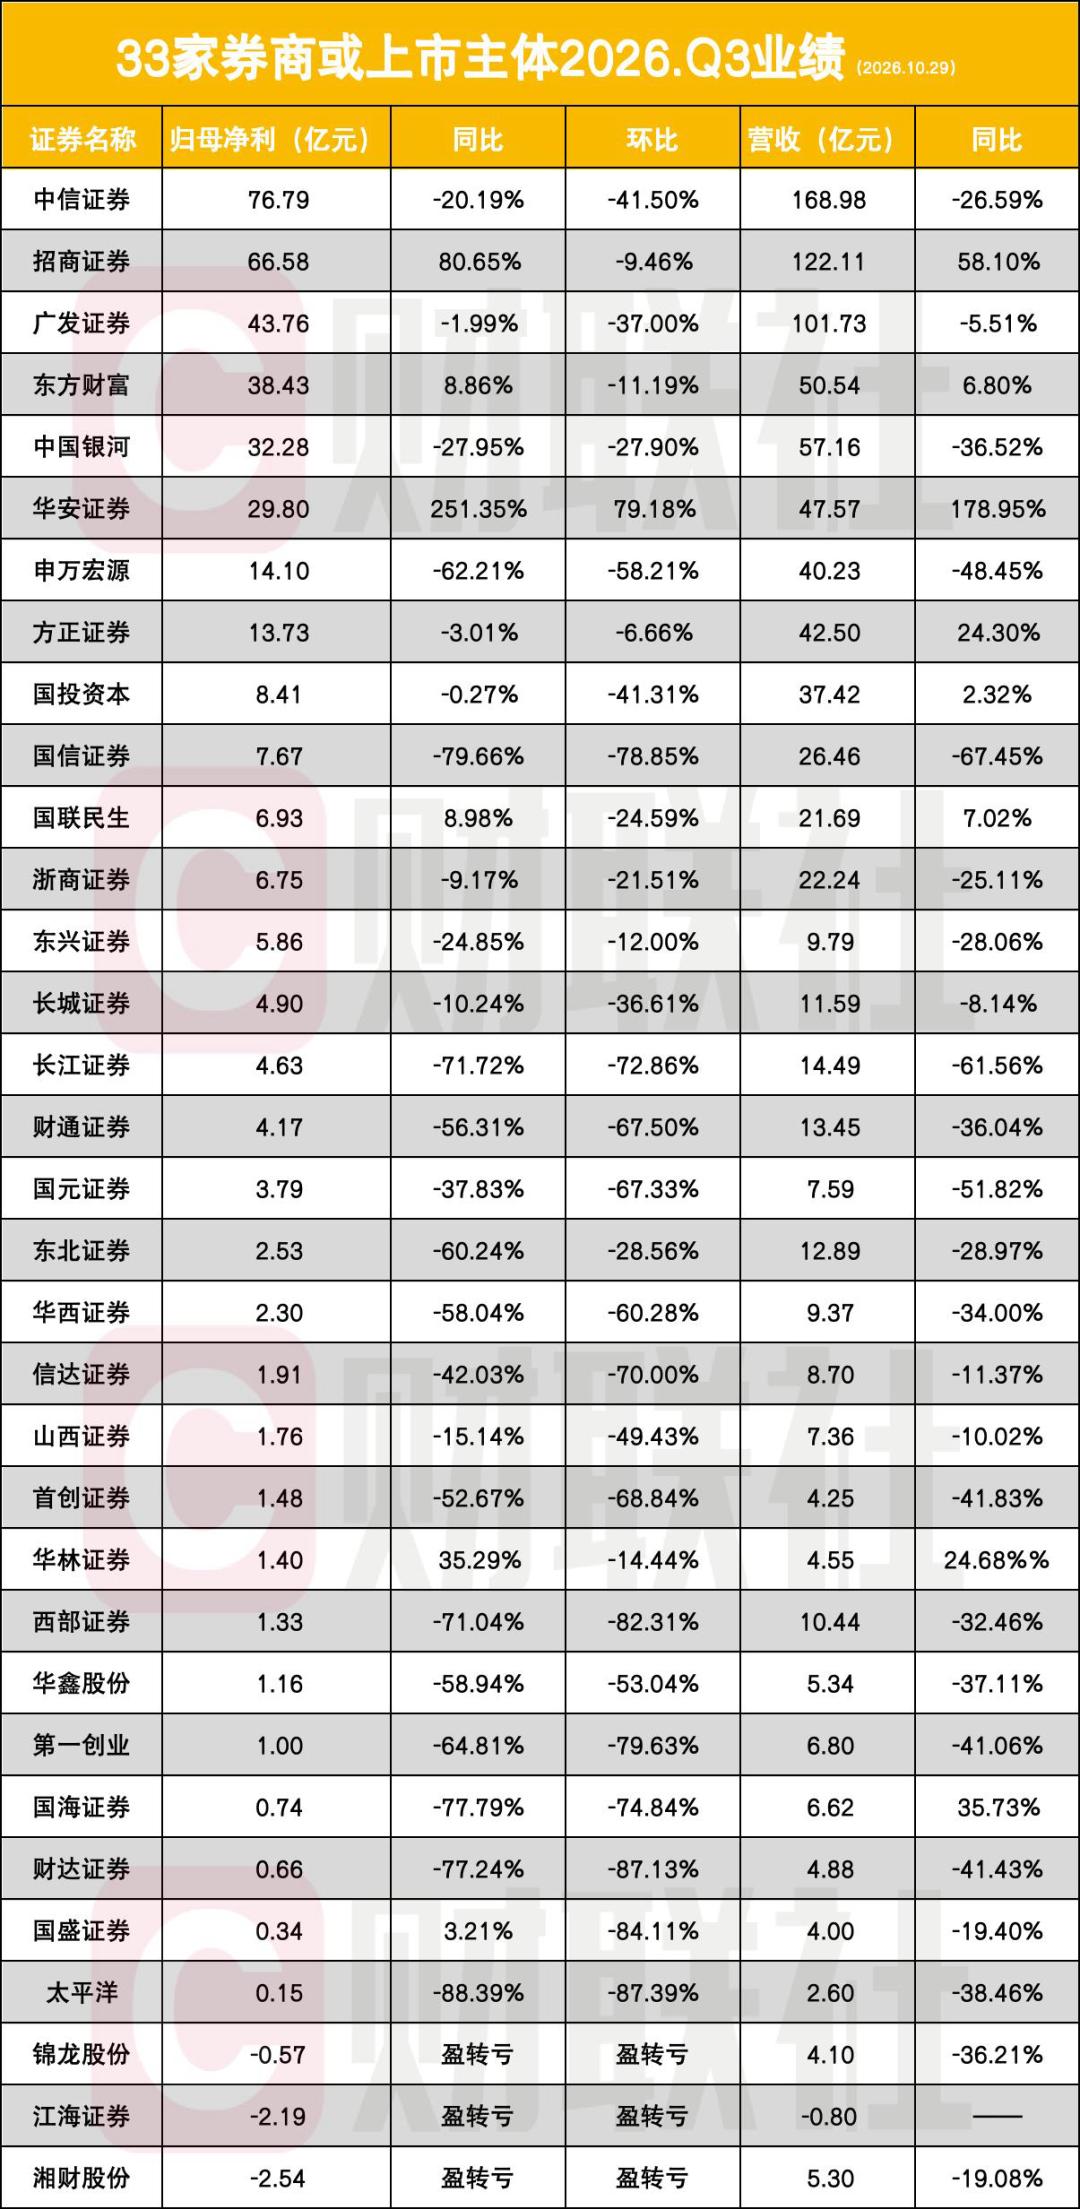
Meanwhile, 3 securities firms posted impressive growth rates in the third quarter, namely Huaan Securities (251.35%), China Merchants Securities (80.65%) and Hualin Securities (35.29%); the other 3 positive-growth firms are East Money (8.86%), Guolian Minsheng (8.98%) and Guosheng Securities (3.21%).
Uneven performance across all business lines
Breaking down the segmented business data of 27 securities firms (total operating revenue reached 294.837 billion yuan), the core logic driving performance differentiation can be clearly observed.
First, the proprietary trading business presents an extreme "double-edged sword" effect. Proprietary trading is the main cause of the sharp performance volatility in the single Q3. Although the overall proprietary income of the above-mentioned securities firms increased slightly by 5.62% year-on-year in the first three quarters, the internal differentiation is extremely severe, with only 7 firms recording positive growth. China Merchants Securities (+185.76%), Huaan Securities (+203.17%) and GF Securities (+67.85%) drove explosive performance growth relying on accurate investment judgments or one-off gains; while Guosen Securities (-67.76%) and Pacific Securities (-52.14%) saw their income cut by half due to poor investment performance.
It is worth noting that facing the sharp fluctuations of the proprietary trading business, some securities firms seem to have begun to take the initiative to shrink their defense lines.
On October 29, Pacific Securities announced in its public notice that the proposals reviewed and approved by the company's board of directors include adjusting the company's risk appetite and adjusting the company's risk tolerance.
Second, the net interest income has achieved a strong collective rebound. This is the most certain growth point in the first three quarters of this year. Among the 27 comparable securities firms, the overall net interest income increased by 42.74% year-on-year, and only 3 firms including GF Securities, Capital Securities and Shanxi Securities recorded a decline. Western Securities (+676.61%), CITIC Securities (+321.75%) and Shenwan Hongyuan (+114.93%) all achieved multiple-fold growth. This is mainly benefited from the recovery of the margin trading market scale and the reduction of securities firms' liability cost. Leading securities firms with the advantage of low-cost capital have achieved "making up for lower margins with larger volume" by expanding the scale of capital intermediary business.
Third, the Matthew effect in the investment banking business has intensified, with leading firms achieving prominent expansion. The overall net income of investment banking increased by 16.89%, but resources are further concentrated in leading firms. CITIC Securities firmly ranks first with 5.124 billion yuan, and leading firms including China Merchants Securities (+43.06%) and GF Securities (+50.16%) recorded significant growth rates. In contrast, the investment banking business of small and medium-sized securities firms such as Huaan Securities (-71.59%) and Guohai Securities (-70.85%) shrank sharply. This indicates that against the backdrop of stricter supervision, project resources are accelerating to gather to leading securities firms with comprehensive strength, squeezing the living space of small and medium-sized securities firms.
In addition, brokerage income has grown steadily, with an overall year-on-year increase of 25.25%, and all 27 comparable securities firms recorded positive growth in net brokerage income in the first three quarters; the overall net income of asset management increased by 18.63% year-on-year, among the 27 comparable securities firms with available data, 19 recorded positive year-on-year growth in net asset management income, and 8 recorded negative growth.
This article is from the WeChat official account "CLS.cn", author: Gao Yanyun, published by 36Kr with authorization.