"72% of token consumption accounts for merely 27% of the total expenditure": The key topic in the bull-bear debate over AI
AI demand data is sparking a rare market divergence: with the same set of figures, bulls and bears each pick what suits their narrative, and both sides claim victory. At the core of this debate lies a disturbing structural contradiction — Token consumption is exploding, but the vast majority of the increment flows to the lowest-priced models, while the GPU cost to serve these Tokens is climbing simultaneously.
According to disclosure from Bobby Molavi of Goldman Sachs in his latest report, OpenRouter data shows that open-weight models processed 72% of Token traffic in the second week of September, yet only accounted for 27% of the platform's total expenditure; meanwhile, closed-source models, despite their share dropping from 89% in early January to 73%, still firmly control the vast majority of monetization gains.
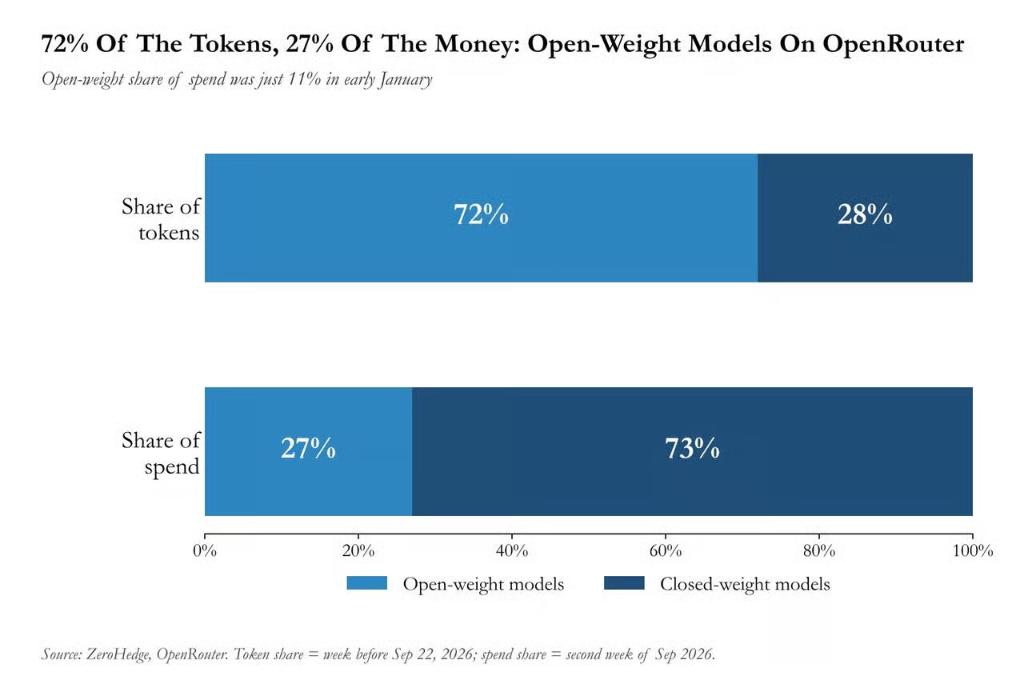
What deserves more attention is that around 69% of Tokens on the OpenRouter platform in mid-September came from Chinese AI laboratories. Molavi characterizes the current market as "unplayable" and points out that the AI productivity dividend has so far left no quantifiable traces outside the technology industry.
This structural contradiction is reshaping the market's expectations for AI return on investment. With GPU rental prices continuing to rise and Token selling prices continuing to fall, the simultaneous pressure on both ends means that computing power suppliers are reaping rental dividends, while enterprise customers and ultimate shareholders who pay for them are facing the dilemma that ROI is difficult to deliver. Meta recently raised up to $95 billion from shareholders for AI capital expenditure, with its chip suppliers taking stakes at the same time, marking that "supplier financing" has evolved from a debt form to an equity form, and questions over the sustainability of the capital cycle are becoming increasingly urgent.
01 Token Demand Explosion: The Real Picture Behind 250x Growth
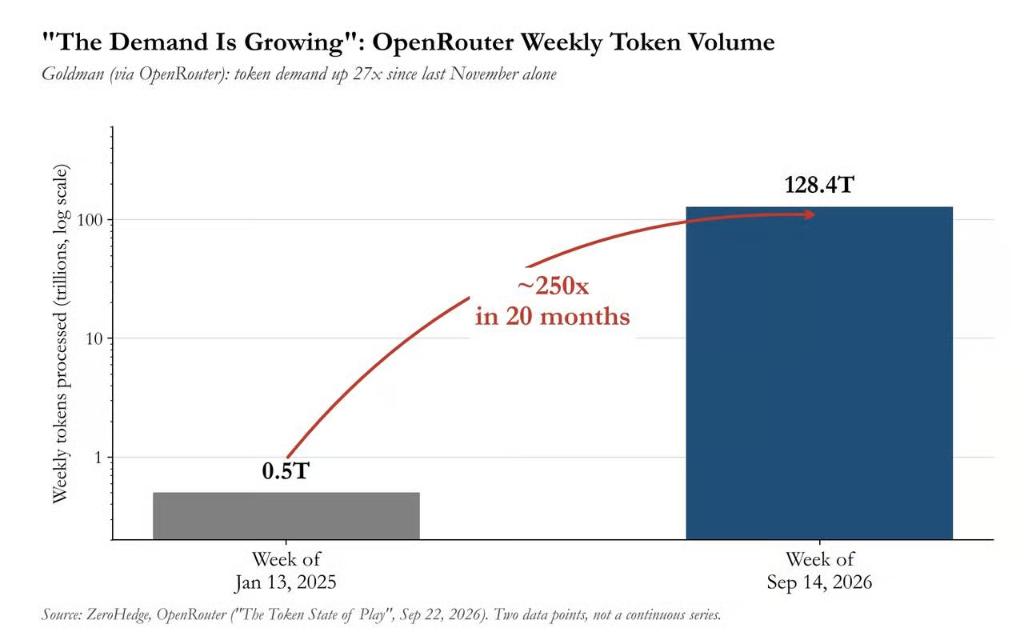
The growth in demand itself is beyond doubt. Citing OpenRouter data, Molavi points out that Token demand has surged 27 times since last November, and open-weight models currently account for 72% of the Token share. From a longer-term perspective, the weekly Token processing volume on the OpenRouter platform soared from 0.5 trillion in mid-January 2025 to 128.4 trillion in the week of September 14, representing an approximately 250-fold increase in 20 months.
GPU pricing also confirms the authenticity of demand. The rental price of H200 has risen by 160% within the year, B200 by 120%, and H100 by 35%. More convincing is that the current rental price of A100 chips produced in 2020 is higher than the level at the beginning of the year, which directly impacts the previous core assumption about the GPU depreciation cycle — if a chip can still generate higher returns six years after production, the pessimistic depreciation forecast based on a three-year benchmark will no longer hold, and the long-term profit potential of hyperscalers also needs to be re-evaluated.
For the bulls, this is the most powerful argument: demand is real, and the economic life of computing power assets is longer than the bears expected.
02 Free Fall of Token Price: The Fastest Deflation in History
However, the other side of the demand explosion is that Token prices are collapsing at an unprecedented speed. According to the research report "The Plunging Price of Thought" released by Epoch AI on September 22, since 2023, the cost of reaching the same level of AI performance has dropped by about 47% per quarter, that is, about 13 times per year; in the field of frontier models, this speed is even faster, with an average quarterly drop of 66%, that is, about 75 times per year.
The most intuitive case given by Epoch AI:
In January 2025, OpenAI's o3 model answered 75% of the doctoral-level scientific questions in the GPQA Diamond benchmark test correctly, with a cost of about $0.30 per question; now GPT-5.6 Luna achieves the same score, with a cost of only $0.0004 per question, and the price has dropped 725 times within 18 months — equivalent to a $50,000 car falling in price to $69.
From a historical horizontal comparison, the decline rate of large language model inference prices is 4 times that of DNA sequencing, 6 times that of the improvement speed of computing power from 1940 to 2001, 18 times that of lithium-ion batteries, and 54 times that of electricity.
However, the actual price drop paid by customers is much slower than the marked price. Data on nearly 2 quadrillion annualized Tokens tracked by YipitData shows that the effective Token pricing of API services dropped by 39% in the second half of 2025 (44% on OpenRouter), but only dropped by 6% year-to-date as of May 2026.
The reason is that: Developers are constantly chasing cheaper models, while enterprise customers are increasing the proportion of high-end models used. Frontier labs temporarily support their revenue side with the premium capability of the latest models — but Epoch's data shows that the half-life of this premium is calculated in quarters, because open-source clones can quickly complete the same task at extremely low cost.
03 The Core of the Bull-Bear Divergence: Who Is Making Money and Who Is Paying the Bill
This is exactly the core of the "same data, two interpretations" dilemma described by Molavi.
The logic of the bulls is: demand continues to expand, the total addressable market (TAM) is still growing, and the explosive growth of Token consumption proves that AI is being widely adopted.
The logic of the bears is: the cost per Token is rising, the revenue per Token is falling, and the main body of incremental traffic is those lowest-priced open-source models. OpenRouter data clearly presents this picture: open-weight models process 72% of Tokens but only take 27% of expenditure; Chinese AI laboratories contribute nearly 70% of the platform's Token traffic. The Goldman Sachs momo basket peaked at the end of June, a time node that highly coincides with the large-scale influx of Chinese open-weight models into the AI market.
Molavi summarizes this contradiction as: The rise in GPU rental prices and the fall in Token selling prices are the results of the same squeeze presented from both ends. It is good news for GPU holders; for enterprises paying the rent, it is a different story.
04 Absence of Productivity Dividend: The Silence of S&P 493
The ultimate logic of AI capital expenditure is to drive benefits for the whole society through productivity improvement. But at present, this logic has not been verified by data outside the technology industry.
Citing a strategist report, Molavi points out that AI "has not shown quantifiable productivity gains in key data outside the tech universe": the revenue per employee and profit margin of Mag 7 (the seven major tech giants) have both improved, but the corresponding indicators of S&P 493 (the remaining 493 companies in the S&P 500) are almost flat.
This reality is changing the AI decision-making logic in the business world. Molavi observes that a large number of enterprises are shifting from the correlation between "Token expenditure and growth and productivity" to the review framework of "the impact of Token expenditure on costs and profit margins". CFOs have found this AI budget line, and they want to know what they have bought for the money spent.
05 The "Boom Cycle" and the Question of Capital Sustainability
Underpinning the current AI capital expenditure boom is a "boom cycle" described by Molavi: the more capital expenditure hyperscalers make, the more income flows into the AI ecosystem, which in turn attracts venture capital and growth equity capital to pour in, forming a two-way capital flow — and the anchor of all this is the initial AI capital expenditure itself.
The fatal weakness of this cycle lies in its sustainability: once capital expenditure slows down, can the income of the entire ecosystem be self-sustaining?
The private equity market is also not immune. Molavi points out that the current exit cases are "numerous but extremely concentrated" (SpaceX, Cerebras, Cursor, Hugging Face), and the valuation revaluation of some projects "has no catalyst other than a letter of intent for investment", and the transaction logic of the entire private equity market is "as if the Token era will never end and everything will be disrupted".
On the financing side, as the debt window narrows, Meta recently announced that it will raise up to $95 billion from shareholders for AI capital expenditure, with its chip suppliers participating in the equity investment at the same time. Supplier financing has evolved from a debt form to an equity form, and the boundary of income and financing between providers and users is increasingly blurred.
Molavi attributes the essence of the entire debate to four questions: What is the construction cost, who will pay the bill, whether the pain is worth it, and how long it will take to see revenue returns.
The current data landscape is: Token demand has grown 250 times, but incremental gains flow to the lowest-priced models; GPU rents are rising, but the bills are ultimately passed on to shareholders; productivity dividends are nowhere to be seen outside the technology industry.
Molavi's conclusion is that the authenticity of demand is beyond doubt, but "demand has grown 250 times, while capital flows to the cheapest models, rents flow to GPU holders, and bills are passed on to shareholders", which is not the ROI story promised by the original capital expenditure. In this bull-bear tug of war, the bears may hold the more powerful half of the rope.
This article is from the WeChat official account "Hard AI", written by a researcher focusing on technology production and R&D, and published with authorization from 36Kr.