Vanke has secured several consecutive loans within five days, how many more financing channels are still available?
According to reports on October 19, China Vanke Co., Ltd. announced in its public filing that three of its holding subsidiaries, Shenzhen Chengxu Enterprise Management Co., Ltd., Shenzhen Jingyi Enterprise Management Co., Ltd., and Huizhou Shenguotou Commercial Real Estate Co., Ltd., have applied for bank loans from OCBC Bank Shenzhen Branch, with a maximum principal of 365 million yuan and a maximum loan term of 120 months.
Five days prior, Fuzhou Huilan Real Estate Development Co., Ltd., a holding subsidiary of Vanke, applied for a 150 million yuan loan with a term of 36 months from Fuzhou High-tech Sub-branch of Fujian Haixia Bank Co., Ltd.
The amount is not large. In the context of Vanke's nearly trillion-yuan total assets and hundreds of billions of yuan in interest-bearing liabilities, the 365 million yuan fund is just like a ladle of water poured into a swimming pool.
However, the market is still willing to interpret this ladle of water as a signal. This troubled property enterprise that is still making losses and has not yet stabilized its sales can still obtain funds from banks, indicating that its financing channels are not completely frozen. In other words, Vanke still has a chance to climb out of the mire.
For Vanke, the significance of every new loan at present is to gently push a certain critical date one step back. If it can be pushed, the company will get a breathing space; if it cannot, that is the real problem.
How Many Financing Channels Are Still Available
Since the end of 2023, Vanke has gradually exposed problems such as tight liquidity and heavy debt pressure, and its financing channels have also narrowed step by step. The possibility of obtaining funds through onshore and offshore bonds, offshore syndicated loans, equity financing and various non-standard financing is very low.
Up to now, there are not many financing channels that Vanke can still use on a rolling basis, which are mainly concentrated in the following three methods:
The first one is onshore bank loans. Vanke had strong credit advantages in the past, and has long maintained head-office-to-head-office strategic cooperation with large banks represented by Industrial and Commercial Bank of China. For example, in November 2022, the head office of Industrial and Commercial Bank of China signed a Strategic Cooperation Agreement with Vanke Group.
However, since the end of 2023, Vanke's bank financing model has shifted from the past "unified borrowing and unified repayment" head-office-to-head-office credit model to a new model of "project-based, mortgage-backed, closed-loop supervision". This means that banks no longer issue loans based on Vanke Group's overall credit, but require each loan to correspond to specific project assets and be supported by sufficient collateral.
The above-mentioned several bank loans are implemented under this framework, which are operating loans with clear mortgage and guarantee arrangements.
In terms of joint and several liability guarantee for the 365 million yuan loan from OCBC Bank, Yinli Commercial Real Estate Co., Ltd. assumes joint and several liability for all debts of the borrower, and at the same time sets up debt subordination and transfer guarantee with its creditor's rights over Huizhou Shenguotou.
In terms of mortgage and pledge, Changshu Yinli Enterprise Management Group Co., Ltd. pledged 100% of the equity it holds in Shenzhen Chengxu and Shenzhen Jingyi.
Shenzhen Chengxu pledged its own accounts receivable and 60% equity of Huizhou Shenguotou, Shenzhen Jingyi also pledged its accounts receivable and 40% equity of Huizhou Shenguotou, while Huizhou Shenguotou provided mortgage and pledge guarantee with the Yangli Impression Hui shopping mall it holds and the accounts receivable of this asset.
It is understood that the commercial volume of Yangli Impression Hui is about 40,000 square meters, which is a mature existing commercial project that opened as early as 2007.
As for the 150 million yuan loan from Haixia Bank, Fuzhou Jiangtu Investment Co., Ltd., a holding subsidiary of Vanke, provided pledge guarantee for this financing with 100% equity of Fuzhou Huilan it holds. At the same time, Fuzhou Huilan provided mortgage guarantee for the loan with the land use right and construction in progress under its name.
According to public data, the land under Fuzhou Huilan's name refers to the plot No. 2026-02 in Minhou that Vanke won with 134 million yuan in May 2026, corresponding to the real estate project "Vanke Yaoguang".
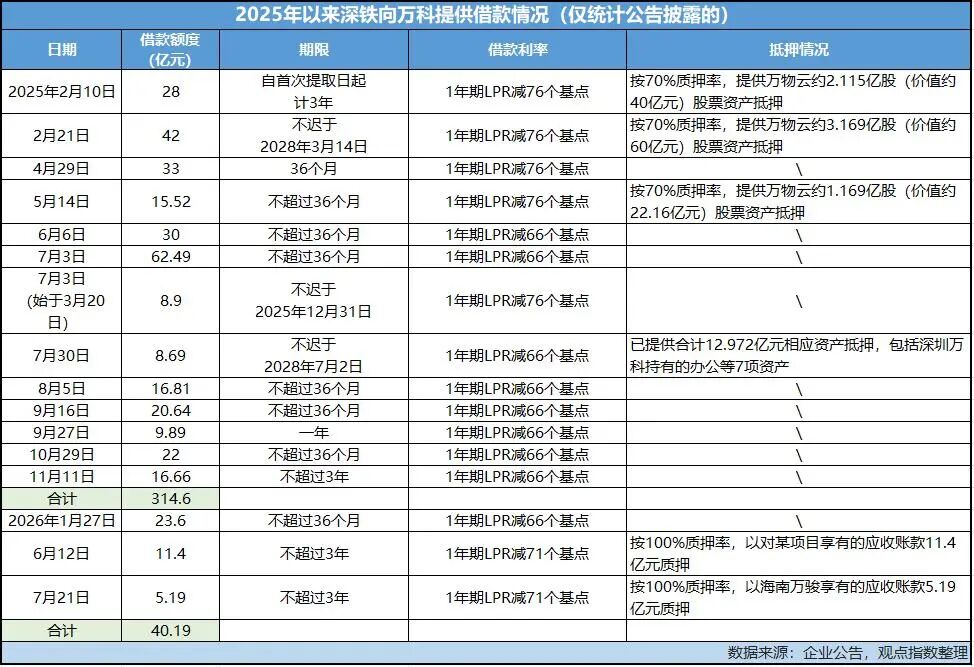
The second type is shareholder loans. Since the crisis broke out at Vanke, the most direct assistance method from Shenzhen Metro Group is to provide capital support.
Loans from Shenzhen Metro Group, the largest shareholder, are currently the most critical and certain source of liquidity for Vanke. These loans have low interest rates, and although some are backed by collateral, they generally have relatively few restrictions, allowing Vanke to use the funds precisely for public bond redemption.
It is reported that Shenzhen Metro Group provided more than 30 billion yuan in shareholder loans to Vanke in the whole year of 2025, involving 13 loan transactions.
Since 2026, Shenzhen Metro Group has provided 3 more loans to Vanke, with a disclosed amount of 4.019 billion yuan, but the actual amount may be higher. According to Vanke's interim performance report: "During the reporting period, Shenzhen Metro Group provided 4.518 billion yuan in loans to the company."
The third type is asset disposal. In 2025, Vanke completed 31 bulk asset transactions of projects, with a total transaction value of 11.3 billion yuan, and at the same time promoted the exit and delivery of its ice and snow business in an orderly manner.
Among them, China Travel International acquired the Songhua Lake Resort and the entire ice and snow management platform held by Vanke for 300 million yuan, and assumed 755 million yuan of bank debt of Vanke's ice and snow business, totaling about 1.055 billion yuan.
Another part of asset disposal is REITs. Vanke has promoted the securitization of operating properties such as rental housing, commercial properties and logistics properties under its umbrella.
Although no product has been listed at the public offering REITs level, Vanke has set up 3 Pre-REITs funds, namely the Jianwan Rental Fund, CITIC Vanke Consumer Infrastructure Fund, and Wanxin Jinshi (Xiamen) Housing Rental Fund.
Vanke's Fundamentals
In the first half of 2026, Vanke is still making losses, but the net cash flow generated from operating activities has shown signs of recovery.
According to Vanke's 2026 interim performance report, the company achieved operating revenue of 70.17 billion yuan (of which revenue from real estate development and related asset operation business was 48.7 billion yuan), down 33.4% year on year; the net loss attributable to shareholders of listed companies was 14.95 billion yuan, expanding 25.2% over the same period of the previous year.
However, at the same time, the net cash flow generated from operating activities surged 116.28% year on year to 495 million yuan, and the operational "hematopoietic capacity" has partially recovered.
In addition, Vanke is still acquiring land. According to the financial report, in the first half of 2026, Vanke obtained 8 new projects mainly through land revitalization and other methods, with a total planned floor area of 750,000 square meters, equity attributable floor area of 363,000 square meters, and equity land price of about 2.71 billion yuan, distributed in core cities such as Shanghai, Chengdu, Zhengzhou and Qingdao.
This shows that Vanke's management has not given up bringing the company's operation back to the right track.
The work of extending bond maturity is also progressing smoothly. According to disclosures, Vanke has completed the maturity extension of 10 bonds in 2026, including "21 Vanke 02", "22 Vanke MTN004" and "22 Vanke MTN005". On August 20, Vanke clearly responded that all public bonds maturing since 2026 have been fully extended.
In terms of offshore bonds, Vanke currently has two US dollar bonds outstanding, with a total issuance size of 1.3 billion US dollars, due on November 9, 2027 (involving 1 billion US dollars) and November 12, 2029 respectively.
After completing the maturity extension of a HK$3.38 billion loan of Vanke Properties (Hong Kong) in May 2026, the redemption pressure of Vanke's offshore debts will mainly extend to 2027 and later.
Therefore, at least at the current stage of 2026, Vanke still has quite a lot of room for maneuver, even though the reality that sales have not yet stopped falling is still in front of it.
According to public data, in the first half of 2026, Vanke achieved a contracted sales amount of 35.8 billion yuan, down 48.2% year on year, and the corresponding sales area was 2.93 million square meters, down 45.6% year on year.
As of the end of June 2026, Vanke's total interest-bearing liabilities amounted to 351.26 billion yuan; among them, interest-bearing liabilities maturing within one year reached 178.86 billion yuan, accounting for 50.9%. Correspondingly, the monetary funds held at the end of the period were 59.05 billion yuan, and the short-term debt repayment pressure is still relatively large.
For Vanke, stopping the bleeding itself is a kind of capability, but between stopping the bleeding and generating new cash flow lies the recovery of the entire market, which is a variable beyond the control of the enterprise.
In any case, being able to borrow money to promote business operations is good news.
This article is from the WeChat official account "Viewpoint", written by Viewpoint New Media, and authorized for release by 36Kr.