Want to fabricate chips with AI? Chip engineers laughed.
Is AI4Chip the next Coding scenario?
The exact same question receives two "diametrically opposed" answers.
The first respondent is Duojiangjiang, a researcher at a foundational large model vendor (hereinafter referred to as "foundation model factory"). From the perspective of large model companies looking at chip design: as AI intelligence keeps improving, the essence of human division of labor stems from "limited context", a restriction that AI does not have. The collaboration of thousands of people in chip design will sooner or later be compressed by a sufficiently intelligent AI. He judges that AI4Chip is exactly the next Coding scenario — starting from helping engineers boost efficiency by 30%, then moving on to end-to-end design of simple chips, and finally evolving to self-improving chip design. He even posted a bold assertion on social platforms: Foundation model factories will all have their own fabs sooner or later.
The second respondent is Saige, a digital chip design practitioner with nearly ten years of experience, who is also a knowledge content creator in the AI chip design field. His first reaction to the statement "the next Coding scenario" is to laugh. Then he gives a blunt judgment: "It is not the next vibe coding scenario. Because chip design itself is far more than just a small amount of code."
Both of their arguments hold water. And this divergence itself is exactly the best entry point to understand AI4Chip.
But before diving into their views, there is one background that must be made clear first — Why is the statement "AI4Chip is the next Coding scenario" being brought up at this point in 2026?
01
After Coding, why do foundation model vendors set their sights on AI4Chip?
The answer lies in the success of the Coding scenario, the ceiling of the Coding scenario, and even more in the computing power bills of foundation model vendors.
The success of large model vendors in the Coding scenario no longer needs to be demonstrated. Claude Code can write code, Codex can modify "repositories", and coding agents have become the most solid implementation scenario for large models in the past two years — tasks are verifiable, data is accessible, willingness to pay is clear, and usage frequency is high.
However, the market capacity of the Coding scenario has a ceiling. As model capabilities continue to improve, foundation model factories must answer a question: Where is the next high-value task domain that can support revenue of the same magnitude?
AI4Chip being pushed to the forefront is no accident. It meets several core characteristics of "the next Coding": high task value, intensive expert experience, verifiable results, a large amount of process data that can be learned, and the paying parties are highly profitable chip and EDA companies. More importantly, chips are upstream of computing power — for foundation model factories, doing AI4Chip is not just selling tools, but going one step deeper into the industrial chain.
This signal is already very clear in the recruitment market. On social platforms, job postings for chip-related talents from foundation model manufacturers appear intensively, covering RTL and verification for digital front-end, layout wiring and timing for digital back-end, and even explicitly stating "AI-native newbies who are passionate about chips are welcome". The industry generally believes that this is essentially the same group of people doing two things: first, training AI to master chip design capabilities, and second, developing chips on their own.
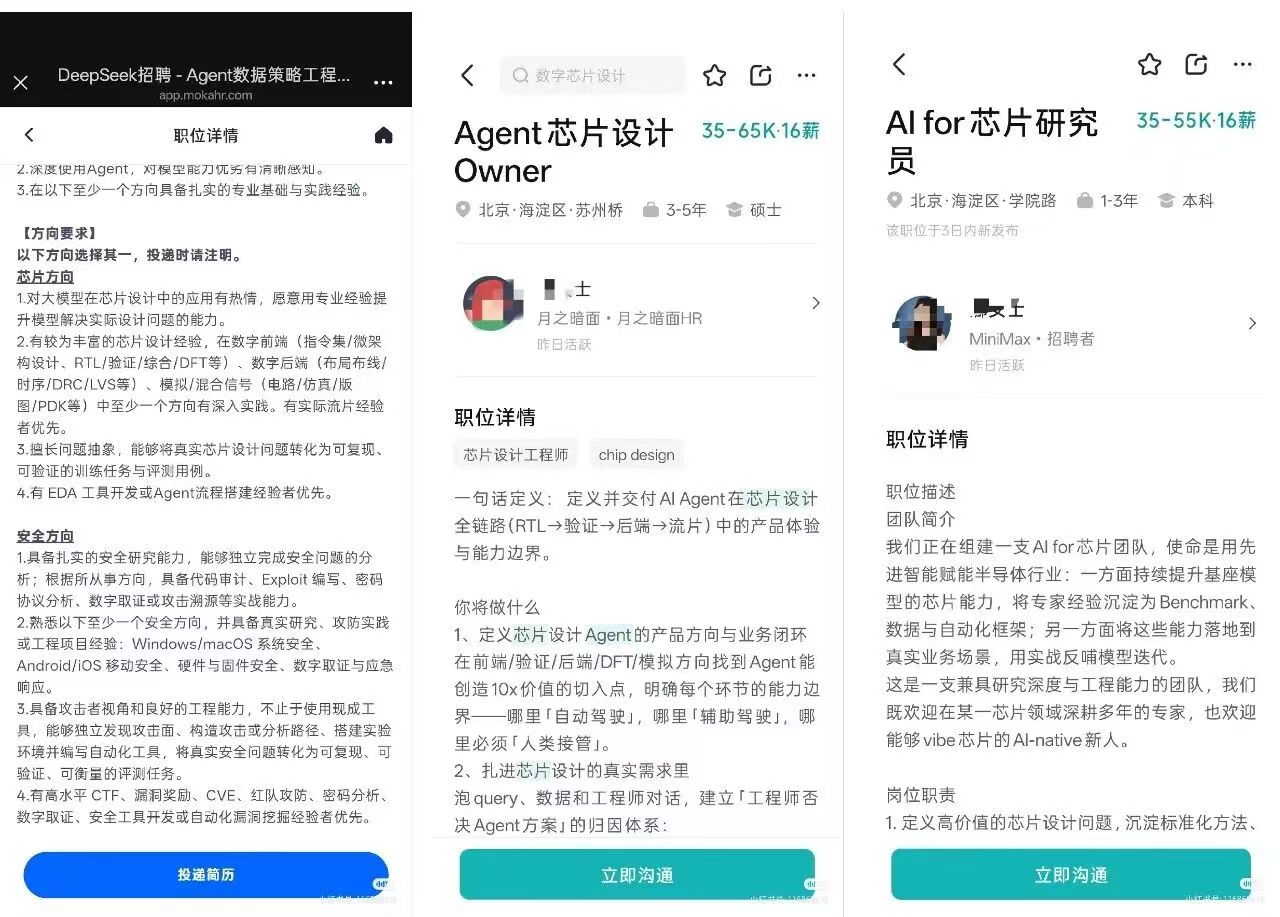
Recruitment information of various domestic foundation model factories is widely discussed on social platforms
Why do foundation model factories insist on doing these two things?
On the one hand, it is for "training". Chip design is one of the longest industrial chains at present — specifications, RTL, verification, synthesis, layout wiring, timing, physical inspection, and tape-out are closely linked. If large models can be verified in this extreme chain, what other scenarios cannot be "conquered"?
On the other hand, the reason is extremely realistic: the computing power bill. Duojiangjiang says: "If you have a model with overwhelmingly superior intelligence, why would you still buy cards from others? Since it is AGI, why not make your own cards?" This rhetorical question points directly to the core — foundation model factories developing chips is not just to sell tools, but to get rid of dependence on upstream computing power giants. For domestic manufacturers, there is an additional driving force caused by "card shortage": "If the root cause is the lack of computing power, why optimize trivial details instead of directly optimizing this fundamental constraint?"
Saige fully agrees with this judgment, and adds the final link from the perspective of business endgame. In his view, the product provided by model providers is model capabilities, just like electricity, which will eventually move towards oligopolistic competition and strong national regulation. The profit of "power plants" is relatively fixed, and the price of basic energy cannot be unreasonably high. If foundation model factories still want to pursue growth, they must have their own hardware products.
Therefore, AI4Chip being pushed to the forefront is not only a technological evolution, but also a business necessity: large models need the next cash flow, foundation model factories need to get rid of computing power dependence, the chip industry needs efficiency, and policies need a starting point for curve overtaking. The superposition of motivations from all parties makes it an inevitable step for foundation model manufacturers to "enter the market on their own".
But motivation is one thing, whether the scenario is feasible at present is another. This goes back to the core question below, which is also the starting point of the divergence between the two respondents.
02
Is AI4Chip the next Coding scenario?
Do not rush to take sides: the "AI4Chip" mentioned by the two people are not the same thing.
Duojiangjiang's logic is top-down.
His starting point is the evolution rhythm of AI capabilities. In his view, producing a large chip today requires the collaboration of hundreds or even thousands of people, and each person only understands a small part of it — This is essentially not because the division of labor is naturally like this, but because "the intellectual bandwidth of individuals is limited, and the context that individuals can process is extremely limited, so the workflow has to be split into very fine pieces". AI does not have this restriction. A sufficiently intelligent AI can be replicated infinitely, and can master front-end, back-end, verification, and physical design at the same time. Therefore, in the long run, chip design will definitely be accelerated by AI, and it will not only accelerate a certain link, but the entire cycle of hardware and software co-design, "AI for Chip, Chip for AI, it keeps this loop running on its own." He sets this timeline in the next 5 to 10 years.
The current path is much more pragmatic, and directly draws on the experience of Coding: The first step is to let AI learn the knowledge of chip engineers; the second step is to learn the experience of architects; the third step is to gradually learn co-design. In the early stage, it is an efficiency tool that helps engineers save 30% of the work; in the middle stage, it can complete end-to-end design of some relatively simple chips; and finally it reaches the cutting-edge self-iterating stage.
The reason why he thinks this path is "feasible" is that the Coding scenario has already gone through this process. The evolution of large models in code generation gives him transferable confidence: As long as the task can be split into verifiable steps, AI can gradually "take it over".
In his view, the current state of AI4Chip is similar to "the state of Coding one or two years ago" — "Everyone already feels that it can basically write large chunks of code for you. You can assign tasks to it, but it leaves the 10% to 20% most difficult parts for you."
Saige draws a clear line between "the present" and "the future": "AI4Chip is a very cutting-edge topic, and there are many discussions in the industry, but it is not the next vibe coding scenario yet."
What he faces every day are RTL, verification, PPA, and wafers. He admits that AI is already helping hardware engineers do work — writing some front-end code, generating small scripts, and querying tool usage. But he emphasizes that this is just the tip of the iceberg. The real difficulty of chip design does not lie in that small amount of code, it ultimately returns to a physical entity. "You also have to consider physical design, testing, and the PPA (power consumption, performance, area) impossible triangle... Purely outputting code is actually a very simple task, and we are already doing it now. But AI4Chip in the overall sense is actually a systematic consideration. Code is only the very first small part."
His evaluation of AI tools in the current chip design process uses a very specific classification: L0 to L1. Most of the so-called "EDA Agent" on the market are still stuck between L0 and L1 — "Connecting a shell to the model, they dare to call themselves an Agent". Even the AI tool released by one of the three EDA giants, in his view, "is more like a small assistant that can help you look up information and generate small scripts, it has not even reached the semi-automation level".
In other words, what Duojiangjiang talks about is "whether AI can learn chip design", while what Saige talks about is "what proportion of the part AI has learned at present occupies in real chip delivery". These two are not the same thing.
But the two actually have a common understanding: AI will continue to penetrate deeper into chip design. The divergence is not in the direction, but in the rhythm and focus — Duojiangjiang looks at the extension of the capability curve, while Saige looks at the landing point of the capability curve in real delivery. Since motivation is not a problem, the key lies in the implementation progress. So the question naturally shifts to: what stage have we actually reached now?
03
What stage have we reached? Is there a gap between China and foreign countries?
Duojiangjiang's judgment on domestic progress is very restrained: Everyone is working underwater. What can be seen on the surface is the Kimi K3 previously released by Moonshot AI, which uses open source EDA tools and the Nangate 45nm process library to complete the design of a chip with an area of about 4mm². In September, Qwen officially announced two production-oriented experiments respectively: in chip design, Qwen3.8-Max started from a NoC module specification and completed RTL, verification and physical implementation; in another independent experiment, Qwen3.8-Max deployed Qwen3.8-Flash-Next to T-Head Xuan Tie M890, and continuously optimized end-to-end inference performance.
Foreign company Anthropic has also officially announced the formation of a dedicated chip design team, and has begun to use Claude for engineering development and design of custom chips. OpenAI and Synopsys announced a multi-year strategic cooperation to jointly develop a dedicated AI model GPT-Synopsys for chip design. At the same time, compared with foreign AI4Chip combinations, China is relatively weak in both EDA and model aspects. But in general, whether in China or abroad, there is still a certain distance on this road before commercialization.
He also clearly states the difficulties. A lot of experience in chip companies is not on paper, but in the minds of engineers and in confidential documents. The only solution he can think of at present is to hire experts — there is no better option. The evaluation criteria for the quality of AI4Chip results also need to be established by industry experts, "just like pulling a bunch of top scholars in basic disciplines to do benchmarks in AI4Science". At present, the difficulty he encounters in daily work is also "how to better scale high-quality data", and this problem is "piled up by countless details", making it hard to define which link is particularly difficult.
Saige's perspective starts from the implementation dilemmas.
He describes a widespread contradiction in the industry: "Attitude is very open, but actions are very cautious": Bosses want to make achievements in this field, but they do not want to be the first to eat crabs. Companies will not set up a project and invest hundreds of millions to support the tape-out of a fully AI-native chip project at present. Engineers can make demos, but if the demo does not tape out, it is just a demo; moreover, many demos use non-commercial EDA tools, which are open source and contrary to the world's mainstream processes. The results are not recognized by the mainstream, so they will not enter the real production environment.
So how big is the gap between China and foreign countries? Saige gives a more specific scale: About 6 months.
He thinks that top foreign models are relatively leading, but the leading extent is "only 6 months". More importantly, he believes that this 6-month gap can be remedied by engineering measures — for example, instead of continuing to stack model parameters, we can build a better Harness.
But chips are ultimately a combination of software and hardware. When asked whether the long-term accumulated gap between China and foreign countries will expand as foreign EDA and manufacturing chains are complete and advanced, Saige is optimistic. He anchors China's advantages in the application side and market demand. After applications are widely deployed, product shipment volume can positively guide the direction of improvement and upgrading, instead of relying on old data and old indicators to guide improvement. The same applies to AI4Chip: real application scenarios bring positive feedback from the application side, which guides AI4Chip to further strengthen. He emphasizes that this is actually a "very long chain and evaluation system", not a test-taking style where you get full marks as soon as you finish answering.
This explains why he summarizes China's overtaking path into six words: Surround the cities from the countryside. He believes that China's willingness to promote AI4Chip is actually stronger — because China has always been a follower on the chip track, and it is unlikely to achieve curve overtaking by following the old European and American routes. "If you want to surpass them, there may be another new track, similar to the new energy vehicle industry." AI4Chip is exactly that new track.
Domestic policies are also catching up at this point in time.
In August, the Beijing Economic and Technological Development Area (hereinafter referred to as "Beijing E-Town") officially released the "AI4Chip Action Plan for Leapfrog Development of Integrated Circuit Industry Empowered by Artificial Intelligence (2026-2028)" (hereinafter referred to as "20 AI4Chip Policies"). As the first special AI4Chip policy across the country, the 20 AI4Chip Policies will focus on five major actions for the integrated circuit industry: "AI-native full-chain empowerment", "AI + Intelligent Design" to revitalize chips, "AI + Manufacturing and Packaging & Testing" to build chips, "AI + Equipment and Materials" to strengthen chips, and "AI + Industrial Ecology" to nurture chips. The goal is that by 2028, Beijing E-Town will basically build an integrated circuit industry AI integrated development system, cultivate 3 to 5 leading ecological AI4Chip enterprises with international influence, and form more than 10 benchmark applications with industry promotion capabilities.
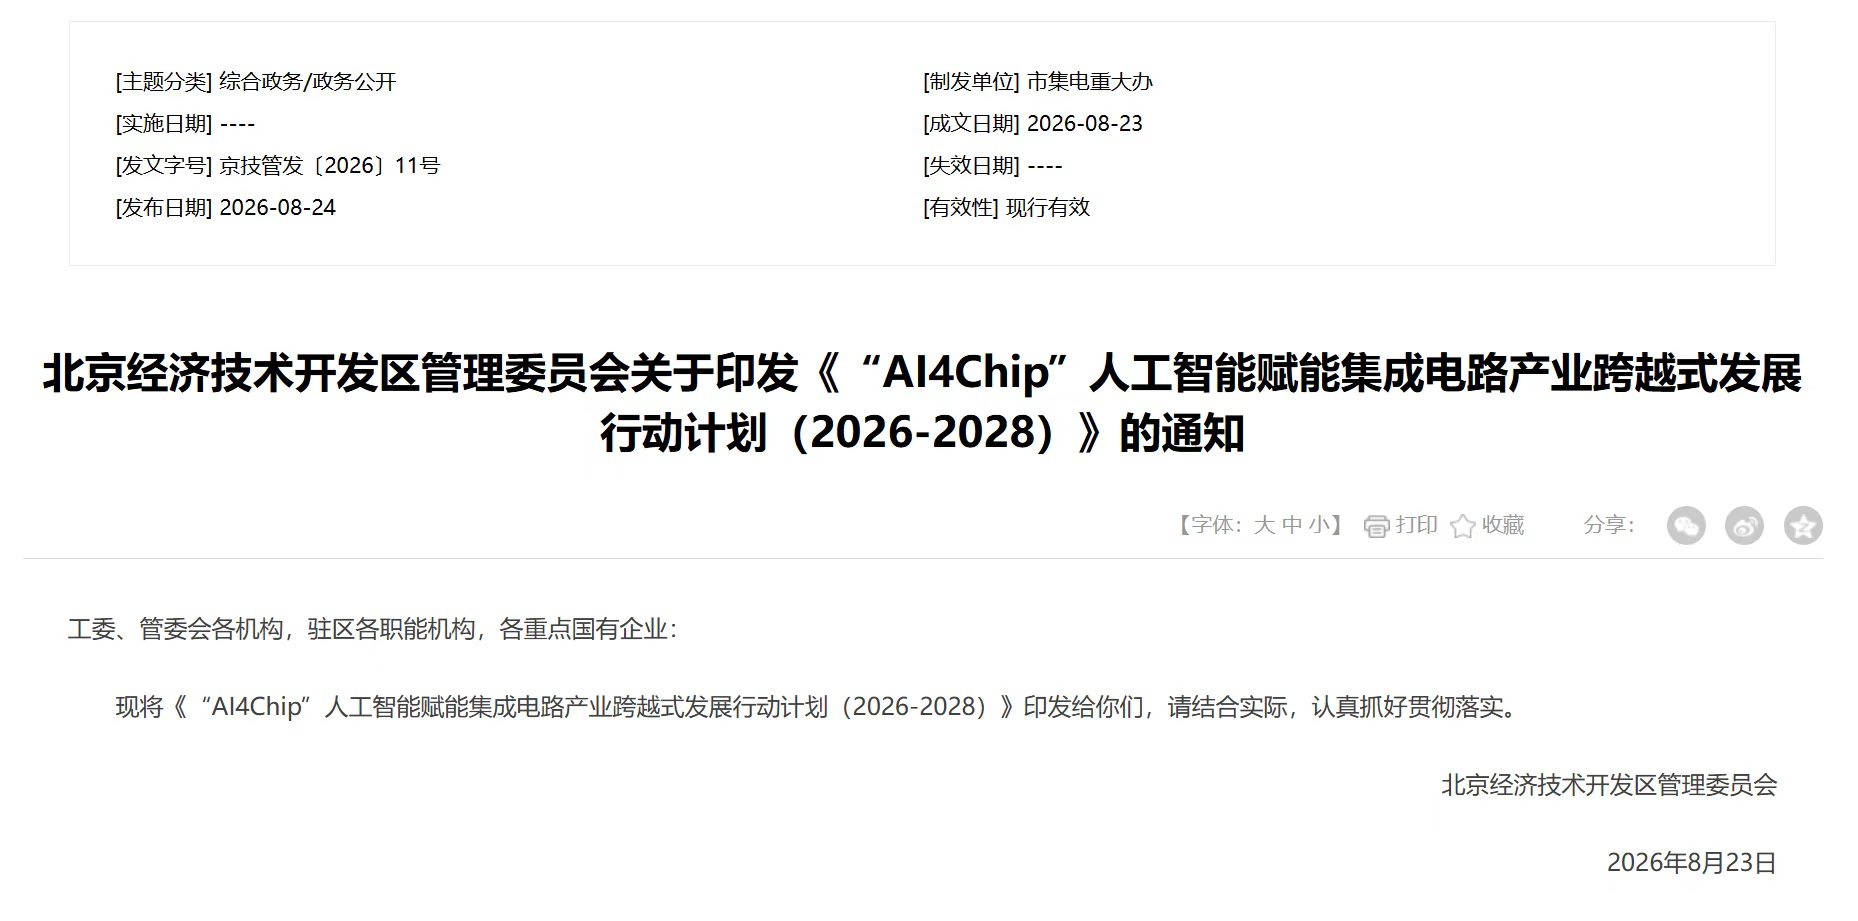
Source: Official website of Beijing Economic and Technological Development Area
But can policies solve the problem of "the first person to eat crabs"? The answer is still cautious. The risk-reward ratio of tape-out is a business decision, which cannot be directly replaced by policies. The real inflection point is not the day the policy is released, but the day when a company is willing to use a real project and a real tape-out budget to complete the entire AI-native process and succeed.
Therefore, the current situation is "there are demos, there are policies, there are recruitments, but real tape-out and commercial closed loops are missing". So if the path is really fully implemented, how will the chip industry be reshaped?
04
Chip design companies caught in the middle: will they be squeezed flat, or forced into a new shape?
Since the two respondents have reached an intersection on one judgment in the previous part — AI will continue to penetrate deeply into chip design, but in the short term it is far from "generate to deliver", and the real constraints lie in verification, tape-out and liability — then