The "seven-year itch" after divorce: The entrepreneurial "ex-wife" intends to seize the 7.6 billion yuan controlling stake of Sotong Development
Seven years have passed since the divorce. When the public thought the two parties had gone their separate ways, the ex-wife of the actual controller of Sunstone Development (603612.SH) has taken action, with the explicit goal of "fighting for the control of the listed company".
On the evening of November 10, Sunstone Development released an announcement stating that Lang Guanghui, the controlling shareholder and actual controller, has received the litigation notice of the post-divorce property dispute case filed by his ex-wife Wang Ping. Wang Ping petitioned to terminate the *Concerted Action and Voting Right Entrustment Agreement*, and requested to be additionally allocated 23.7187 million shares of the company; in addition to the above request, the total amount of other litigation claims put forward by Wang Ping is approximately 393 million yuan. At present, the People's Court of Chaoyang District, Beijing has filed the case.
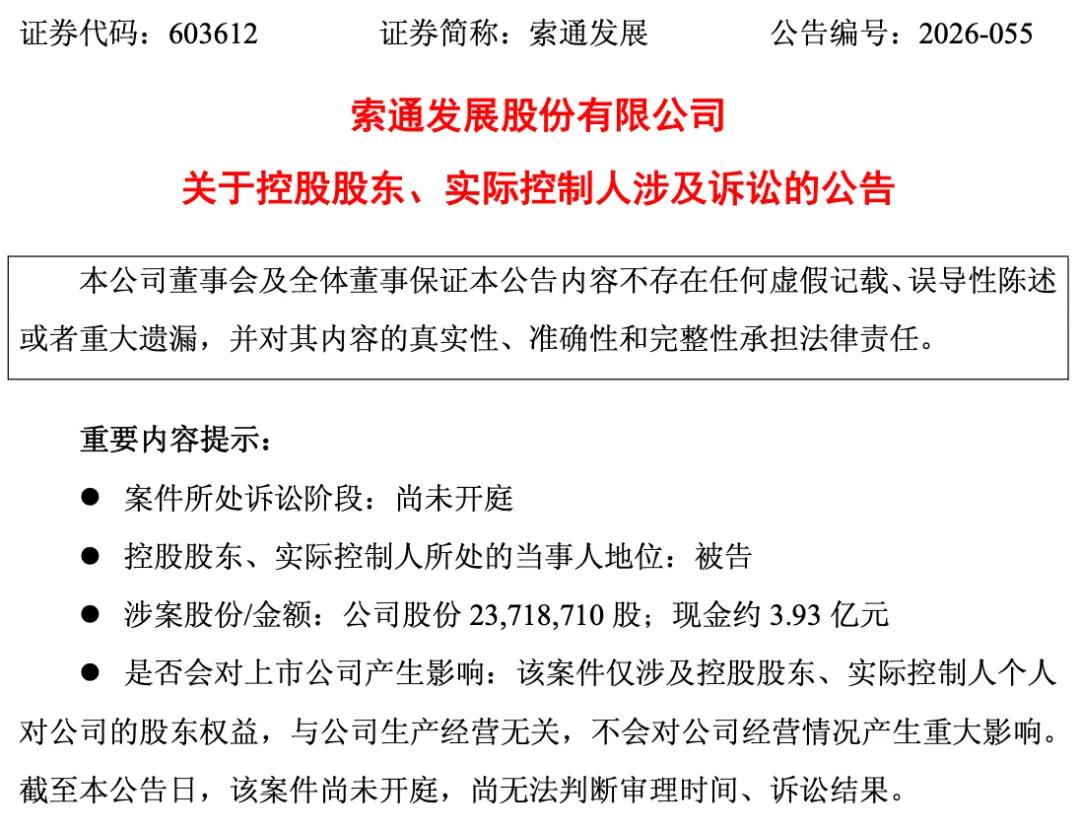
Source: Sunstone Development
Calculated based on the closing price of Sunstone Development at 16.72 yuan per share on November 10, the market value corresponding to these 23.7187 million shares is about 397 million yuan, accounting for about 4.7% of the total share capital of Sunstone Development. More critically, if Wang Ping's claim is supported, the concerted action relationship between Lang Guanghui and Wang Ping may change, and the position of the largest shareholder of Sunstone Development may change hands.
In March 2019, seven years ago, Lang Guanghui and Wang Ping divorced and carried out share split, Lang Guanghui's shareholding dropped from 46.47% to 30%, and Wang Ping received 16.47% of the equity. The two chose to "split shares without splitting control" and signed the *Concerted Action and Voting Right Entrustment Agreement* at the same time. Now, more than a year before the agreement expires, this agreement that was used to maintain the balance has first ushered in a "falling-out" lawsuit.
As of November 12, Sunstone Development closed at 15.24 yuan per share, down 4.99%, with a total market value of 7.591 billion yuan.
Ex-wife claims nearly 800 million yuan, battle for control behind the property dispute
In this litigation, Wang Ping is claiming Sunstone Development shares with a market value of about 397 million yuan on one hand, and demanding a total of 393 million yuan in cash on the other. The sum of the two claims makes the total equity claim scale close to 800 million yuan.
Sunstone Development stated in the announcement that this case only involves the individual shareholder rights and interests of the controlling shareholder and actual controller in the company, has nothing to do with the company's production and operation, and will not have a significant impact on the company's operating conditions.
This "strike" from the ex-wife not only targets Lang Guanghui's personal property rights and interests, but also disturbs the stability of the listed company.
Sunstone Development is mainly engaged in prebaked anodes, lithium battery anode materials, and film capacitors. It is the world's largest commercial prebaked anode manufacturer and one of the world's largest petroleum coke purchasers. In the current equity structure, Lang Guanghui directly holds 72.473 million shares, accounting for 14.55%, and is the controlling shareholder and actual controller of the company; Wang Ping holds 56.053 million shares, accounting for 11.25%, and is the second largest shareholder. The two are concerted parties, holding a total of 25.8%. If Wang Ping terminates the *Concerted Action Agreement* and adds additional shares, although the total shareholding of her and Lang Guanghui remains unchanged, the equity structure of this company is already highly concentrated, the remaining shareholders hold no more than 3% of the shares, and the third largest shareholder Zhu Qing holds only 2.45%, any internal variable will be amplified.
Once Wang Ping terminates the *Concerted Action Agreement* and is additionally allocated shares, the balance may tip. If 23.7187 million shares are transferred out from Lang Guanghui's name, his direct shareholding will drop to about 9.79%, while Wang Ping's shareholding will rise to about 16.02%, surpassing Lang Guanghui to become the largest shareholder.
Sunstone Development stated directly in the announcement that based on the current shareholding, this litigation may cause a change in the largest shareholder of Sunstone Development.
Source: Canstock
Lawyer Ling Guoming from Shandong Shunyao Law Firm told the media that once the entrustment agreement is ordered to be terminated by the court, Lang Guanghui's direct shareholding is only 14.55%, and he no longer has the voting right of Wang Ping's 11.25%, so the foundation of control is greatly weakened. If the court supports Wang Ping's claim to be additionally allocated 23.7187 million shares of the company, Lang Guanghui's control over the company will be further weakened.
That means, if the *Concerted Action Agreement* between Lang Guanghui and Wang Ping becomes invalid, and he loses the support of Wang Ping's voting rights, Lang Guanghui will have far less bargaining chips in hand.
Prebaked anode is a heavy-asset, long-cycle business. Most downstream aluminum electrolysis enterprises will sign long-term supply agreements with suppliers for several years or even longer. Once the control of Sunstone Development falls into a tug of war, even if production continues as usual for the time being, it is likely to shake the trust of large downstream customers, the performance expectation of original long-term agreements, supporting orders for new production capacity, and subsequent in-depth cooperation negotiations may all face pressure.
The case is currently in the mediation stage and has not yet been heard in court, and there is no answer yet as to when the trial result will be released. At present, neither of the two people's shares are pledged, marked or frozen, which means that if the division is to be carried out, there are no additional obstacles in execution.
This unheard mediation case has already pushed the control of this listed company to the edge of uncertainty.
Seven years after divorce, old grievances remain unresolved
The "seed" of this dispute was sown seven years ago.
In 2019, when Sunstone Development had just been listed for two years, Lang Guanghui was still the sole actual controller holding 46.47% of the shares. In that year, he divorced his wife Wang Ping by agreement, signed the *Divorce and Listed Company Share Split Agreement* and the *Concerted Action and Voting Right Entrustment Agreement*, and transferred 56.053 million shares (accounting for 16.47% of the total share capital) to Wang Ping through non-transaction transfer.
According to the agreement, property rights such as dividends, share transfer and pledge still belong to Wang Ping, and rights such as attending general meetings of shareholders, proposing motions, voting, nominating and voting for the election of directors and supervisors are irrevocably entrusted by Wang Ping to Lang Guanghui; when the two parties have different opinions, Lang Guanghui's opinion shall prevail. The purpose of the agreement is to ensure Lang Guanghui's actual control over Sunstone Development.
After the transfer is completed, Lang Guanghui's direct shareholding drops to 30%, and Wang Ping gets 16.47% of the equity. "Splitting property without splitting control" was the most decent arrangement at that time: the shares were given to the ex-wife, but the voting right remained in the hands of the actual controller Lang Guanghui.
It is worth noting that Wang Ping does not hold any position in Sunstone Development and its subsidiaries, does not enter the management layer or the board of directors, and does not participate in daily production management. She was born in March 1964, and serves as executive director and manager of Beijing Yiyun Feiyang International Culture Communication Co., Ltd.
Wang Ping was an important supporter on Lang Guanghui's entrepreneurial journey, before and after Sunstone Development went public, the two were still in a marital relationship. Wang Ping accompanied Lang Guanghui to start from scratch, witnessing the whole process of the company's listing, wealth appreciation, and becoming a wealthy man.
Source: Canstock
In the following years, Lang Guanghui's shareholding continued to decline. In 2022, he transferred shares to two Xuanyuan private equity funds as his concerted parties, later he reduced his holdings through block trading, and the two Xuanyuan funds withdrew one after another. In 2024, Lang Guanghui transferred 24.6054 million shares (accounting for 4.55% of the total share capital) by agreement. From September to October 2025, he reduced his holdings by a total of about 9.9619 million shares (accounting for 2% of the total share capital). After layers of dilution, his current direct shareholding is only 14.55%.
Lawyer Xu Yang, partner of Guohao Law Firm, once analyzed that the concerted action agreement is a relationship of concerted action formed by relevant shareholders of the company linked by agreement, and all parties promise to take concerted action when proposing motions and voting at the general meeting of shareholders or the board of directors of the listed company. The concerted action agreement between the actual controller and the major shareholder who are husband and wife also falls into this category.
Xu Yang further pointed out that whether to take concerted action and its validity status have an important impact on the governance of listed companies, so the stock exchange has many regulations on this, and the purpose of the regulation is to prevent the risk of governance chaos and sudden change of business logic of listed companies caused by sudden control changes. Xu Yang also reminded that this method of voting right entrustment also has certain hidden dangers. Once the voting right entrustment is lifted, new disputes may arise.
According to the terms of the concerted action agreement disclosed by Sunstone Development, it is not easy to unilaterally terminate the entrustment, and it is necessary to confirm that there is a breach of contract, the agreement cannot be performed, or continuing to perform will damage the interests of one party.
Now Wang Ping takes the initiative to sue for termination of the concerted action agreement, which is equivalent to submitting this written agreement that has maintained the balance for many years to the court for ruling. The biggest pain point of litigation is that it is full of variables, and it may continue to disturb the expectation of control, which is also the situation that listed companies try their best to avoid.
Who will take charge of the listed company?
Lang Guanghui was born in Jincheng, Shanxi in 1963. He graduated from Northeastern University with a postgraduate degree in 1987, and is a professor-level senior engineer.
In 1998, he founded Sunstone International Industry and Trade Co., Ltd. in Tianjin, starting from the import and export trade of metallurgical materials. At the beginning, there were only three people in the company: he was both the boss and the salesman, and also worked as a porter. In 1999, the company exported 500 tons of prebaked anodes, and by 2007, its turnover reached 1 billion yuan.
In 2003, he acquired the Lubei Carbon Plant in Linyi, Shandong, and plunged into the prebaked anode business. This business, though not eye-catching, is the lifeblood of the aluminum industry.
On July 18, 2017, Sunstone Development was listed on the main board of the Shanghai Stock Exchange, becoming the first listed company in the aluminum carbon industry, which was a great glory for a time.
In 2021, Lang Guanghui was on the Hurun Rich List with a wealth of 3.9 billion yuan, ranking 1781st.
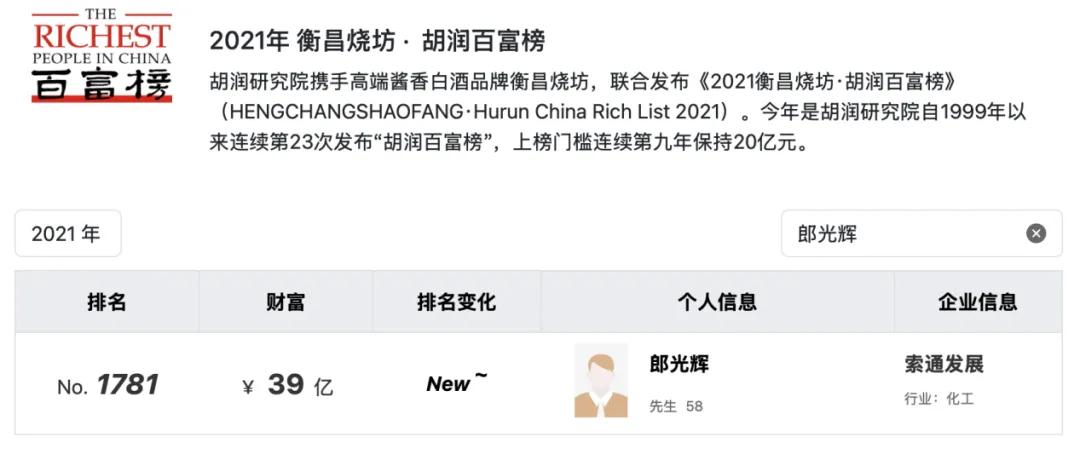
Source: Hurun Rich List
Prebaked anode is a key consumable for aluminum electrolysis, and the scale of this business follows the capacity of aluminum electrolysis, so the cyclical feature is engraved in the financial statements. Financial reports show that from 2022 to 2025, Sunstone Development's operating revenue was 19.401 billion yuan, 15.311 billion yuan, 13.75 billion yuan and 17.693 billion yuan respectively, and the net profit attributable to shareholders was 905 million yuan, a loss of 723 million yuan, 272 million yuan and 747 million yuan respectively, going through a full year of loss in the middle.
The 2026 three-quarter report shows that Sunstone Development achieved operating revenue of 16.324 billion yuan in the first three quarters, a year-on-year increase of 27.91%; the net profit attributable to shareholders was 657 million yuan, a year-on-year increase of 0.48%. Looking at the third quarter of 2026 alone, Sunstone Development's operating revenue was 5.91 billion yuan, a year-on-year increase of 32.65%; the net profit attributable to shareholders was 251 million yuan, a year-on-year increase of 91.93%; the deducted non-net profit attributable to shareholders was 265 million yuan, a year-on-year increase of 121.81%. The company explained that the strong demand in the primary aluminum industrial chain drove the year-on-year increase in the prices of petroleum coke and prebaked anodes, the sales volume increased by 8% year-on-year, and the gross profit rose accordingly.
